SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Copper Clad Laminate (CCL) and Prepreg Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
DIELECTRIC MATERIALS Semiconductor Market Research

Copper Clad Laminate (CCL) and Prepreg Market

Emerging Trends, Technological Advancements, and Business Strategies 2026-2034

◷
UPDATED 25 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 6d6e8337b13d
▯
FORMATS PDF

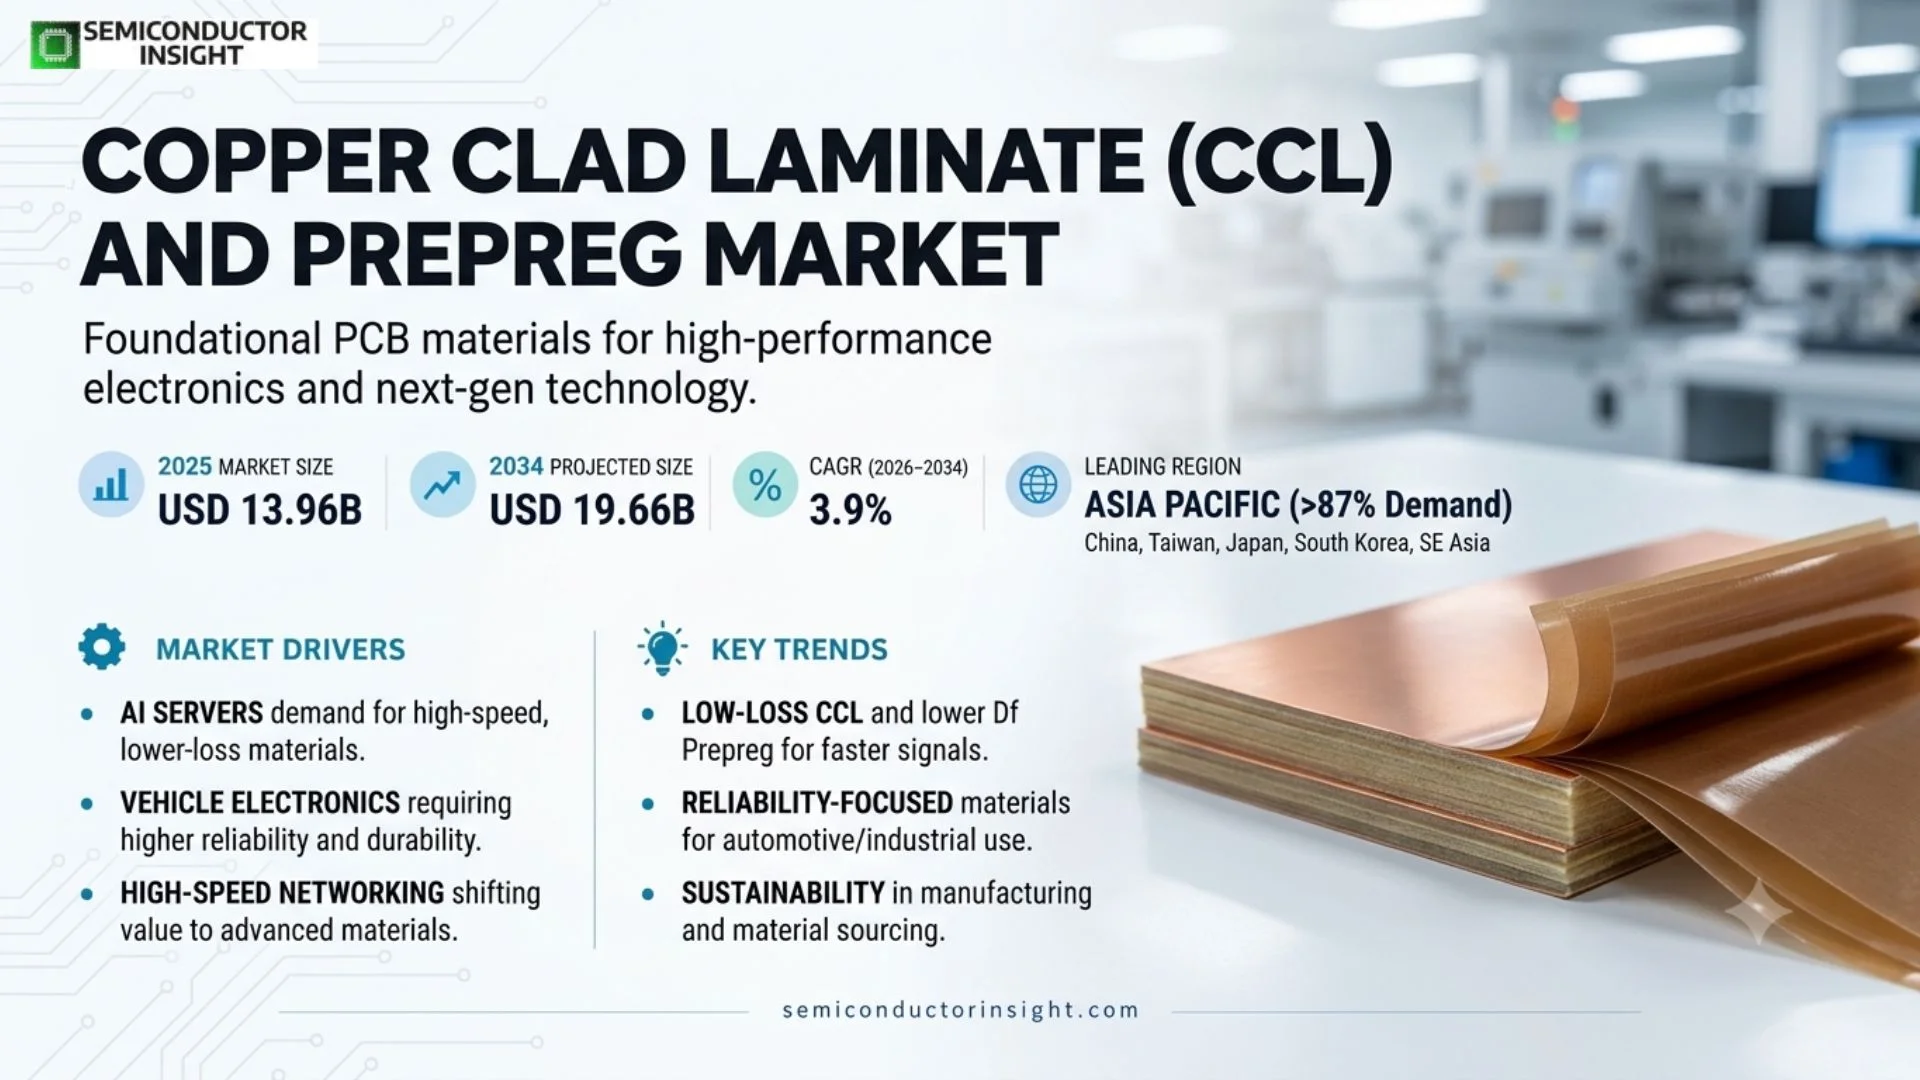
Copper Clad Laminate (CCL) and Prepreg Market is projected to reach USD 19.66 billion by 2034, expanding at a 3.9% CAGR during 2026–2034. Asia Pacific accounts for more than 87% of demand, reflecting the concentration of PCB fabrication, electronics assembly and laminate production in China, Taiwan, Japan, South Korea and Southeast Asia. Communications remains the largest application, while AI servers, high-speed networking and vehicle electronics are shifting value toward lower-loss and higher-reliability materials.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 13.96 billion
2034 Projected Size
USD 19.66 billion
CAGR (2026–2034)
3.9%
Largest Market in 2025
Asia Pacific (>87% share)

Key Takeaways

  • Asia Pacific holds more than 87% of global demand, making regional manufacturing scale and customer proximity central to cost, lead time and qualification support.
  • Copper clad laminate represents close to four-fifths of product demand, reflecting its foundational role in PCB construction, while prepreg is essential to multilayer build-up and lamination.
  • Communication contributes more than one-third of application demand, supported by servers, switches, routers, base stations and other high-speed networking hardware.
  • AI infrastructure is shifting the product mix toward low-loss, high-layer-count materials; Panasonic announced new MEGTRON capacity in Thailand and China to serve this demand.
  • Automotive electrification broadens demand for thermally stable and high-reliability PCB materials as power electronics, ADAS and zonal architectures increase electronic content per vehicle.
  • Qualification and raw-material control remain structural barriers because resin systems, glass cloth, copper foil and PCB process parameters must work as a tightly controlled stack-up.

Copper Clad Laminate (CCL) and Prepreg Market Overview

Copper Clad Laminate (CCL) and Prepreg Market was valued at USD 13.96 billion in 2025 and is projected to reach USD 19.66 billion by 2034, expanding at a 3.9% CAGR during 2026–2034. Asia Pacific accounts for more than 87% of demand, reflecting the concentration of PCB fabrication, electronics assembly and laminate production in China, Taiwan, Japan, South Korea and Southeast Asia. Communications remains the largest application, while AI servers, high-speed networking and vehicle electronics are shifting value toward lower-loss and higher-reliability materials.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless stated otherwise

Copper clad laminate is the rigid or flexible dielectric base onto which copper foil is bonded to create the electrical foundation of a printed circuit board, while prepreg is the resin-impregnated reinforcement layer used to bond cores and build multilayer structures. Together they determine electrical insulation, signal loss, thermal stability, dimensional control and mechanical reliability before a PCB fabricator adds circuitry through imaging, etching, drilling, plating and lamination.

The commercial market spans standard FR-4 materials used across mainstream electronics and premium formulations engineered for high frequency, high data rates, high temperature or harsh environments. Product qualification is application-specific: a networking platform may prioritize dielectric loss and skew control, an automotive inverter may emphasize thermal endurance and CAF resistance, and aerospace programs can require traceability and long qualification. This creates a wide value spread even when nominal laminate thickness and copper weight look similar.

Demand is changing because PCB performance is becoming a system-level constraint. AI servers and switches require more layers and lower transmission loss, electric vehicles place electronics close to heat and vibration, and communications infrastructure uses higher frequencies that expose dielectric weakness. Suppliers therefore compete not only on volume and price but also on resin chemistry, glass weave, copper-foil profile, thickness control and the ability to support PCB process windows at customer sites.

Segment Analysis: By Type

By type, the market is segmented into Copper Clad Laminate (CCL) and Prepreg. CCL is the dominant product and represents close to 80% of demand, while prepreg remains indispensable to multilayer PCB construction because it bonds cores and fills spaces around copper features during lamination.

Type Technical / functional role Market position and purchasing logic
Copper Clad Laminate (CCL) A copper foil bonded to a cured dielectric laminate forms the starting panel for PCB imaging and etching. The material system controls dielectric behavior, dimensional stability, thermal endurance and mechanical support, making it the primary performance-bearing substrate in rigid and many high-frequency circuit boards. Largest type, near 80% share. Standard FR-4 supplies large volumes, while low-loss, high-Tg, low-CTE and thermally conductive grades command higher value. AI servers, networking and automotive electronics are pulling more revenue toward premium formulations rather than simply increasing commodity panel area.
Prepreg Partially cured resin impregnated into glass cloth or other reinforcement is placed between laminate cores and copper layers, then flows and cures during lamination. Resin content, flow, gel behavior, glass style and dielectric properties directly affect multilayer thickness, registration, impedance and reliability. Prepreg demand follows multilayer board complexity and layer count. High-end systems often require tightly matched laminate and prepreg families so electrical and mechanical properties remain consistent through the stack-up. Suppliers with strong application engineering can therefore capture value through complete material platforms rather than isolated sheets.

Pricing and product-mix logic

Commodity FR-4 remains price-sensitive, but premium value grows when customers require lower dissipation factor, tighter dielectric consistency, high glass-transition temperature, low Z-axis expansion or specialized copper-foil interfaces. Qualification costs encourage PCB fabricators to stay with proven material families once a stack-up is validated. As a result, premium CCL and matched prepreg can sustain stronger margins than undifferentiated laminate even when total area growth is moderate.

Segment Analysis: By Application

By application, demand covers Communication, Computer, Consumer Electronics, Vehicle Electronics, Industrial and Medical, Military and Space, and Others. Communication is the largest application at more than 33% of demand, while AI computing and vehicle electronics are among the strongest sources of higher-specification material requirements.

Application Demand characteristics
Communication Largest application, above 33% of demand. Base stations, routers, switches, optical transport and data-center networking require low-loss PCB materials as data rates and operating frequencies rise. Signal integrity becomes more sensitive to resin chemistry, glass weave and copper roughness, so material qualification increasingly involves full stack-up performance rather than a single laminate property.
Computer Servers, AI accelerators, storage and high-performance computing systems use high-layer-count boards with demanding power distribution and high-speed interconnects. Generative-AI infrastructure is raising the value of low-loss laminates because switch fabrics and processor-to-memory links operate at higher data rates, while thermal density places additional stress on board materials and plated interconnects.
Consumer Electronics Smartphones, PCs, wearables and appliances provide large unit volumes but impose intense cost and form-factor pressure. Thin materials, dimensional control and reliable high-density interconnect processing matter most. Demand can be cyclical, yet short product cycles continually refresh PCB designs and create opportunities for materials that support thinner, denser and more power-efficient electronics.
Vehicle Electronics EV power electronics, ADAS, infotainment and zonal controllers require materials that tolerate heat, vibration, humidity and long service life. Higher voltages and faster in-vehicle links increase the value of low-CTE, high-Tg, CAF-resistant and low-loss systems. Qualification is long, but design wins can remain in production across vehicle platforms for years.
Industrial and Medical Industrial automation, robotics, instrumentation and medical equipment favor reliable materials with long availability, controlled electrical properties and robust manufacturing windows. Unit volumes are lower than consumer electronics, but customer switching costs are higher because certifications, validation and field reliability can outweigh small differences in material price.
Military and Space Radar, avionics, satellites and secure communications use high-frequency and high-reliability PCB materials under severe environmental conditions. Volumes are modest, but specifications and traceability create premium pricing. Suppliers compete on documented performance, stable long-term formulations and the ability to meet controlled sourcing requirements.
Others Other uses include power conversion, test equipment, specialty instrumentation and emerging electronics systems. These applications can create attractive niches when they require unusual dielectric, thermal or mechanical properties that mainstream FR-4 cannot provide, allowing specialist laminate suppliers to compete on engineering depth rather than scale alone.

Additional segmentation dimensions

Axis Source-defined segments Commercial interpretation
By End User PCB Manufacturers; Composite Material Fabricators; OEMs PCB manufacturers are the core buyers because they laminate, image, drill and plate the material into finished boards. OEM specifications strongly influence approved material lists, while composite fabricators participate where prepreg is used beyond conventional electronics.
By Performance Requirement Standard Performance; High-Frequency / High-Speed; High-Thermal Reliability Standard grades compete on scale and consistency, while high-speed and high-thermal systems command greater technical value. The mix is shifting toward performance grades as AI servers, automotive electronics and high-frequency communications raise electrical and reliability requirements.
By Material Composition FR-4 Epoxy; Polyimide; Ceramic-based FR-4 provides the broad volume base. Polyimide and ceramic-filled or ceramic-based systems serve higher-temperature, high-frequency or specialty reliability requirements where conventional epoxy cannot deliver the required electrical or thermal performance.

Copper Clad Laminate (CCL) and Prepreg Market Size

Regional Analysis

Asia Pacific leads with more than 87% of global demand because PCB fabrication, electronics assembly and laminate production are concentrated in the region. North America and Europe remain important high-value design and specialty-material markets, while South America and the Middle East & Africa are smaller and more dependent on imported laminate and PCB supply.

How does the commercial logic differ by region?

The regional pattern reflects where PCBs are fabricated as much as where end equipment is designed. Asia Pacific captures most volume through integrated manufacturing clusters. North America has a smaller material-production footprint but strong demand from data centers, aerospace, defense, medical and advanced electronics. Europe is weighted toward automotive and industrial reliability. South America and the Middle East & Africa generate selective demand through automotive, telecom, industrial and defense projects but rely heavily on global supply chains.

Region Position Growth outlook Demand profile Evidence-led market logic
Asia Pacific Largest, >87% share Strongest volume base Manufacturing-led China, Taiwan, Japan, South Korea and Southeast Asia combine laminate plants, PCB fabricators and electronics OEMs; Panasonic is expanding MEGTRON capacity in Thailand and Guangzhou.
North America High-value secondary market Moderate Design- and specialty-led IPC reported North American PCB shipments up 19.9% year over year in January 2025, while AI data centers, aerospace, defense and medical electronics support higher-specification materials.
Europe Specialty market Moderate Automotive and industrial Automotive electronics, industrial control, aerospace and communications create demand for high-reliability and low-loss materials even though much PCB fabrication is sourced from Asia.
South America Smaller Selective Import-led Brazil and Mexico-linked supply chains drive electronics and automotive demand, but regional laminate production is limited and material availability depends on global distributors and imported PCBs.
Middle East & Africa Smallest base Project-led Telecom, defense and industrial Telecom infrastructure, aerospace/defense programs and industrial electronics create selected opportunities, while most laminate and PCB requirements are supplied through imported materials or assemblies.
Asia Pacific LARGEST · >87% SHARE

Why does Asia Pacific dominate CCL and prepreg demand?

Asia Pacific dominates because it contains the deepest concentration of PCB fabrication and electronics manufacturing globally. This creates local demand for standard FR-4 at very large scale and for advanced low-loss materials near server, telecom, automotive and semiconductor customers. Panasonic’s new MEGTRON investments in Thailand and Guangzhou reinforce how suppliers are adding premium capacity close to Asian PCB fabricators.

Market positionLargest; >87% share
Product mixCCL-led, premium grades rising
Demand anchorPCB & electronics manufacturing
Key signalNew MEGTRON capacity in China/Thailand
Country / market Position Commercial evidence
China Largest manufacturing base China combines extensive PCB fabrication, networking equipment, consumer electronics and vehicle production. Panasonic announced a 7.5 billion yen Guangzhou MEGTRON line in March 2026, with initial operation planned for April 2027, directly expanding premium circuit-board-material supply for Chinese customers.
Taiwan Advanced PCB ecosystem Taiwan hosts major PCB and electronics supply-chain companies serving servers, networking, notebooks and semiconductor infrastructure. High-density and high-speed products support demand for low-loss laminates and tightly controlled prepreg systems.
Japan Technology and materials hub Japan combines high-end materials expertise with automotive, industrial and communications customers. Panasonic and other Japanese material suppliers compete on low-loss resin systems, reliability, application engineering and global manufacturing support.
South Korea Electronics and memory hub South Korea’s semiconductor, display and consumer-electronics industries create demand for advanced PCBs and related laminate. High-speed computing and premium devices increase the importance of electrical performance and fine stack-up control.
Southeast Asia Fast-growing manufacturing location Thailand, Vietnam and other Southeast Asian markets are gaining electronics and PCB investment. Panasonic’s 17 billion yen Ayutthaya project is designed to support PCB customers in the region and forms part of a plan to double MEGTRON capacity over five years.

Market instances shaping regional demand

Panasonic Guangzhou MEGTRON expansion – March 2026
Panasonic Industry announced a 7.5 billion yen investment in a new Guangzhou production line for MEGTRON circuit-board materials, with initial operation targeted for April 2027. The project raises local availability of low-loss materials for AI-server and networking PCB customers in China.
Panasonic Thailand expansion – September 2025
Panasonic Industry announced a 17 billion yen new building and MEGTRON line at Ayutthaya, with a plan to double total MEGTRON production capacity over five years. This provides a concrete capacity signal for premium CCL demand in Southeast Asia.
China EV scale supports automotive PCBs
IEA reported China sold more than 13 million electric cars in 2025. Each EV contains power electronics, battery management, infotainment and control systems, expanding the installed base of PCBs that require thermal, insulation and reliability performance.

The full report provides country-level revenue, demand and competitive detail within this region.

North America HIGH-VALUE MARKET

What supports North American demand despite Asia’s production dominance?

North America remains commercially important because advanced server, aerospace, defense, medical, telecom and automotive electronics are designed and qualified in the region. Many laminate volumes are imported or converted through global PCB supply chains, but material specifications and approved vendor lists are often set by North American OEMs. Strong PCB bookings in early 2025 also indicated a firmer local demand environment.

Market positionHigh-value secondary
PCB indicatorJan 2025 shipments +19.9% YoY
Book-to-bill1.24 in Jan 2025
Demand profileAI, aerospace, defense, medical
Country / market Position Commercial evidence
United States Largest regional market The United States anchors AI data centers, cloud hardware, defense, aerospace, medical technology and automotive electronics. These industries specify high-reliability and low-loss materials and can influence global PCB stack-ups even when fabrication occurs offshore.
Canada Specialty electronics Canada contributes telecom, aerospace, industrial and research demand. Volumes are smaller, but engineering-led applications value certified materials and stable long-term supply.
Mexico Electronics manufacturing corridor Mexico’s electronics and automotive assembly base creates demand for PCBs and materials through regional manufacturing supply chains. Much laminate remains imported, so logistics and approved distributor relationships are important.

Market instances shaping regional demand

North American PCB shipments rose 19.9% – January 2025
IPC reported January 2025 North American PCB shipments up 19.9% year over year and bookings up 44.1%, with a 1.24 book-to-bill ratio. The data indicates strong underlying PCB demand, which supports laminate consumption through local and imported board supply.
AI-server buildout raises material value
High-speed switches and accelerator platforms require low-loss multilayer boards, increasing the value per PCB panel even if regional laminate tonnage remains below Asia. This mix effect is strategically important for suppliers of premium resin and copper systems.
Aerospace and defense sustain qualification barriers
Long product lifecycles and environmental requirements make approved laminate changes costly. Suppliers that maintain stable formulations and traceability can retain programs for many years, supporting defensible specialty demand.

The full report provides country-level revenue, demand and competitive detail within this region.

Europe AUTOMOTIVE & INDUSTRIAL

Why is Europe a specialty-oriented CCL market?

Europe’s value is concentrated in automotive, industrial automation, power electronics, aerospace and communications equipment. These applications use lower volumes than Asian consumer-electronics production but demand strong thermal, electrical and lifecycle performance. The region’s vehicle electrification also increases PCB count and power-electronics content, favoring materials that can withstand heat, vibration and long service lives.

Market roleSpecialty / high reliability
EV signalEurope sold >4M EVs in 2025
Demand anchorAutomotive & industrial
Supply modelMix of local and imported PCBs
Country / market Position Commercial evidence
Germany Automotive and industrial leader Germany’s automotive OEMs, Tier 1 suppliers and industrial automation companies support demand for high-Tg, low-CTE and reliability-focused materials. Qualification and traceability can matter more than lowest unit price.
France Aerospace and industrial France adds aerospace, defense, telecom and industrial electronics demand, creating niches for low-loss and high-reliability laminate systems.
United Kingdom Design and specialty electronics The United Kingdom contributes aerospace, defense, communications and technology design activity. Material demand is often routed through global PCB suppliers while specifications are controlled locally.

Market instances shaping regional demand

European EV sales exceeded 4 million – 2025
IEA reported electric car sales in Europe exceeded 4 million during 2025. Electrification increases inverters, battery management, charging and control electronics, supporting higher PCB content and stricter thermal and reliability requirements.
Industrial automation supports long-life materials
European machinery and control-system OEMs often maintain products for years, making stable laminate formulations and long-term availability commercially important.
Aerospace programs reward specialty performance
High-frequency communications and avionics can use premium laminates with low loss and controlled thermal behavior, sustaining niche value even when board volumes are modest.

The full report provides country-level revenue, demand and competitive detail within this region.

South America IMPORT-LED

What defines the South American opportunity?

South America is a smaller, import-dependent market where CCL demand is largely embedded in automotive, telecom, industrial and consumer-electronics supply chains. Brazil is the principal regional electronics base, but much of the PCB and laminate value is sourced internationally. Supplier success therefore depends on distribution, landed cost, local technical support and the ability to service qualified global OEM platforms.

Market positionSmaller
Demand profileAutomotive, telecom, industrial
Supply structureImport dependent
Key marketBrazil
Country / market Position Commercial evidence
Brazil Largest regional opportunity Brazil’s automotive, telecom, industrial and electronics sectors create the deepest regional PCB demand. Local customers rely on international laminate and PCB supply, so distributors and global approved-vendor relationships are important.
Argentina Selective industrial demand Argentina supports smaller industrial, automotive and electronics requirements, with demand sensitive to investment cycles and import conditions.
Rest of South America Project-led Mining, energy, telecom and industrial projects create PCB demand, but volumes are fragmented and typically supplied through imported electronic assemblies.

Market instances shaping regional demand

Telecom modernization creates selected demand
Network upgrades require routers, radios and power systems containing multilayer PCBs, but laminate purchasing is often captured upstream by Asian or North American PCB fabricators.
Automotive electronics remain an anchor
Regional vehicle assembly supports control modules and power electronics, creating demand for reliable PCBs even when materials are imported.
Distribution determines availability
Because the local laminate production base is limited, stock position, lead time and freight cost can matter as much as material list price for smaller PCB fabricators.

The full report provides country-level revenue, demand and competitive detail within this region.

Middle East & Africa PROJECT-LED

Where does demand arise in the Middle East and Africa?

Demand is concentrated in telecom infrastructure, aerospace and defense, industrial control, energy systems and selected electronics manufacturing initiatives. Most CCL and prepreg are imported directly or arrive embedded in PCBs. The market is therefore less about commodity laminate volume and more about ensuring approved materials, documentation and supply continuity for projects with specific reliability or high-frequency requirements.

Market positionSmallest base
Demand profileTelecom, defense, industrial
Supply structureImported materials/PCBs
Commercial triggerProject qualification
Country / market Position Commercial evidence
Israel Advanced electronics niche Aerospace, defense, communications and technology companies create demand for high-reliability and high-frequency PCBs, often sourced through global qualified supply chains.
Turkey Industrial and defense Turkey’s industrial, automotive and defense electronics sectors support selected PCB demand and regional distribution opportunities.
Gulf states Telecom and infrastructure Data-center, telecom, energy and industrial projects create demand for electronic systems, although most laminate value is captured by imported PCBs and equipment.

Market instances shaping regional demand

Data-center investment increases high-speed PCB content
Cloud and AI infrastructure projects use switches, servers and power equipment that depend on multilayer boards. Premium laminate demand may be realized in the exporting PCB country, but regional project specifications influence material qualification.
Defense electronics support high-reliability niches
Radar, communications and avionics applications can require low-loss or high-temperature PCB materials with traceable quality.
Energy infrastructure broadens industrial electronics demand
Grid, renewable-energy and oil-and-gas systems use control and power electronics, supporting long-life PCB requirements across harsh operating environments.

The full report provides country-level revenue, demand and competitive detail within this region.

Competitive Landscape

Competition combines very large Asian laminate producers with global specialty-material companies. Scale is important in commodity FR-4, but premium programs are won through electrical performance, reliability, consistent resin and glass systems, copper-foil control, application engineering and the ability to qualify products across multiple PCB fabricators. The top three suppliers-Kingboard Laminates Group, SYTECH and Panasonic-collectively represent roughly one-third of the market.

Kingboard Laminates Group and major Asian producers compete with broad product portfolios, manufacturing scale and close proximity to PCB customers. Their cost base and regional supply density matter most in mainstream materials, where utilization and procurement scale influence margin. At the same time, they are moving into higher-speed grades to prevent premium niches from being captured entirely by specialty suppliers.

Panasonic, Rogers, Isola, AGC and other technology-led suppliers differentiate through low-loss materials, controlled dielectric properties and application-specific reliability. In high-speed networking, customers evaluate insertion loss, skew, copper roughness, glass weave and processability together. A material that delivers better electrical performance but creates lamination or drilling problems can still lose qualification, making field engineering a meaningful competitive asset.

Approved material lists create stickiness. Changing a laminate can require impedance redesign, reliability tests and customer requalification, especially in automotive, aerospace and networking equipment. This protects incumbents after design-in but also raises the cost of entering a new platform. Suppliers use second-source strategies, regional plants and matched laminate/prepreg systems to reduce customer risk and improve the odds of long-term program retention.

Competitive tier Representative companies How they compete
Scale leaders Kingboard Laminates Group; SYTECH; Nan Ya Plastic; EMC; ITEQ Compete through large Asian production footprints, broad FR-4 portfolios, customer proximity and increasingly capable high-speed material systems.
Premium technology leaders Panasonic; Rogers Corporation; Isola; AGC Focus on low-loss, high-frequency, high-reliability and application-engineered material platforms used in networking, aerospace, automotive and other demanding electronics.
Regional / specialist suppliers DOOSAN; TUC; Wazam New Materials; Ventec International Group; others Compete through selected performance niches, local service, cost positions or approved relationships with PCB fabricators and OEMs.

Key Participants

Kingboard Laminates GroupSYTECHPanasonicNan Ya PlasticEMCITEQDOOSANTUCGDM International Technology Ltd.Hitachi Chemical (Showa Denko Materials)IsolaNanya New Material Technology Co., Ltd.Rogers CorporationWazam New MaterialsChang Chun GroupMitsubishi ElectricGuangdong Goworld Lamination PlantVentec International GroupSumitomoAGC

Production Capacity Analysis

Production capacity is concentrated in Asia Pacific because laminate manufacturing benefits from proximity to copper foil, glass cloth, resin suppliers and high-volume PCB fabricators. Capacity is not interchangeable: a standard FR-4 line cannot automatically serve an AI-server material program because resin formulation, glass handling, cleanliness, copper treatment, pressing control and customer qualification can differ substantially. Recent MEGTRON investments illustrate that suppliers are adding dedicated premium capacity rather than treating all square meters of laminate as equivalent.

Panasonic’s announced Guangzhou and Ayutthaya investments show how premium capacity is being positioned close to Chinese and Southeast Asian PCB customers. The company plans to double total MEGTRON capacity over five years, indicating that high-speed infrastructure is driving a capacity cycle distinct from ordinary FR-4 demand.

Raw materials can constrain performance even when press capacity is available. Low-profile copper foil, specialty glass cloth, resin monomers and fillers affect electrical loss, dimensional behavior and reliability. Qualification of an alternative input can take time because the PCB stack-up is a coupled system, making upstream consistency as important as nominal factory throughput.

Yield and process control determine effective capacity. Tight thickness tolerance, resin flow, surface quality, cleanliness and registration must remain consistent across large panels. Premium materials also require customer-specific technical support, so engineering and laboratory capability can become a bottleneck before physical press capacity is exhausted.

Market Dynamics

The market is growing through a mix of moderate electronics-volume expansion and a more important value shift toward premium materials. AI servers, high-speed communications and vehicle electronics increase layer count, data rate, heat and reliability requirements, while standard consumer products remain cost-sensitive. This creates two simultaneous markets: a scale-driven commodity business and an engineering-led performance business where qualification, material consistency and process support determine share.

Market Drivers

Growth drivers and directional market impact

Driver Directional impact* Why it matters
AI servers and high-speed networking High Data-center switches, accelerator platforms and optical networking operate at higher data rates, increasing insertion-loss sensitivity and the need for lower-loss laminate systems. Panasonic’s new MEGTRON lines in Thailand and China are direct evidence that suppliers are committing capital to this demand.
Automotive electrification and ADAS Medium-High Electric vehicles add inverters, battery management, charging systems, sensors and computing. IEA reported more than 20 million electric cars sold globally in 2025, increasing the installed base of electronics that require thermal endurance, insulation reliability and long product lifecycles.
5G and communications infrastructure Medium Higher-frequency radios, routers and transmission equipment place greater demands on dielectric loss and impedance consistency. Communication already represents more than one-third of market demand, so performance upgrades within the segment can move mix and margins even when infrastructure unit growth is moderate.
Rising PCB complexity Medium More layers, finer routing and higher power density increase prepreg usage and make material behavior more critical during lamination. As designs become harder to manufacture, PCB fabricators value stable resin flow, dimensional control and technical support, strengthening supplier relationships.

AI servers and high-speed networking

Data-center switches, accelerator platforms and optical networking operate at higher data rates, increasing insertion-loss sensitivity and the need for lower-loss laminate systems. Panasonic’s new MEGTRON lines in Thailand and China are direct evidence that suppliers are committing capital to this demand.

Automotive electrification and ADAS

Electric vehicles add inverters, battery management, charging systems, sensors and computing. IEA reported more than 20 million electric cars sold globally in 2025, increasing the installed base of electronics that require thermal endurance, insulation reliability and long product lifecycles.

5G and communications infrastructure

Higher-frequency radios, routers and transmission equipment place greater demands on dielectric loss and impedance consistency. Communication already represents more than one-third of market demand, so performance upgrades within the segment can move mix and margins even when infrastructure unit growth is moderate.

Rising PCB complexity

More layers, finer routing and higher power density increase prepreg usage and make material behavior more critical during lamination. As designs become harder to manufacture, PCB fabricators value stable resin flow, dimensional control and technical support, strengthening supplier relationships.

Market Restraints

Constraints and directional market impact

Restraint Directional impact* Commercial effect
Electronics-cycle volatility Medium CCL utilization tracks PCB and electronics production, so inventory corrections can move quickly through the supply chain. Commodity producers face the greatest exposure because excess capacity can trigger price competition before end-market demand recovers.
Raw-material and energy cost exposure Medium Copper foil, glass cloth, resins and energy are major inputs. Sudden cost changes can compress margins when customer contracts lag, and qualification requirements can limit a supplier’s ability to substitute lower-cost materials immediately.
Long qualification cycles for premium grades Medium High-speed networking, automotive and aerospace customers require extensive validation. Qualification protects successful incumbents but slows the revenue conversion of new products and raises the cost of switching materials in an existing PCB stack-up.
Commoditization of standard FR-4 Medium-High Mainstream grades face strong regional competition and limited differentiation. Suppliers must maintain scale and utilization while investing in premium technology, creating capital-allocation pressure for companies that lack either a clear cost advantage or a differentiated performance portfolio.

Electronics-cycle volatility

CCL utilization tracks PCB and electronics production, so inventory corrections can move quickly through the supply chain. Commodity producers face the greatest exposure because excess capacity can trigger price competition before end-market demand recovers.

Raw-material and energy cost exposure

Copper foil, glass cloth, resins and energy are major inputs. Sudden cost changes can compress margins when customer contracts lag, and qualification requirements can limit a supplier’s ability to substitute lower-cost materials immediately.

Long qualification cycles for premium grades

High-speed networking, automotive and aerospace customers require extensive validation. Qualification protects successful incumbents but slows the revenue conversion of new products and raises the cost of switching materials in an existing PCB stack-up.

Commoditization of standard FR-4

Mainstream grades face strong regional competition and limited differentiation. Suppliers must maintain scale and utilization while investing in premium technology, creating capital-allocation pressure for companies that lack either a clear cost advantage or a differentiated performance portfolio.

Market Opportunities

Low-loss materials for 224 Gbps-class infrastructure

As switches and servers migrate to higher serial data rates, dielectric loss, skew and copper roughness become more critical. Suppliers that offer validated low-loss laminate and prepreg platforms can capture higher value per board and deepen relationships with networking OEMs and advanced PCB fabricators.

Automotive high-voltage and high-reliability PCBs

EV platforms create opportunities for materials with higher thermal endurance, insulation reliability and low expansion. The strongest beneficiaries are suppliers that can meet automotive quality systems and sustain formulations across long vehicle lifecycles.

Regional second sourcing

OEMs increasingly want resilient supply for strategic electronics. A supplier with qualified plants in multiple Asian countries, or with strong distributor and technical coverage outside Asia, can win share by reducing geopolitical and logistics concentration without forcing customers to redesign the material stack.

Thermally enhanced and specialty substrates

Power conversion, industrial systems and high-density computing create niches for ceramic-filled, metal-backed or otherwise thermally enhanced laminate systems. These categories are smaller than FR-4 but support better differentiation and pricing because the customer is solving a specific thermal or reliability problem.

Supply Chain Analysis

1. Raw materials

Copper foil, glass cloth, resins, fillers and additives

2. CCL & prepreg manufacturing

Resin formulation, impregnation, lamination and copper bonding

3. PCB fabrication

Imaging, etching, drilling, plating and multilayer lamination

4. OEM / system integration

Servers, telecom, vehicles, industrial, consumer and aerospace systems

Raw materials

Performance starts with upstream materials. Copper profile affects conductor loss, glass weave influences skew and resin chemistry controls dielectric, thermal and flow behavior. Specialty inputs require tighter specifications and can be harder to second-source without requalification.

CCL & prepreg manufacturing

Manufacturers convert raw materials into controlled sheets and prepreg rolls. Value capture depends on formulation know-how, uniformity, yield and the ability to supply matched systems across thicknesses and glass styles.

PCB fabrication

PCB fabricators are the direct customers and determine whether a material behaves reliably in high-volume processing. Their feedback on lamination, drill wear, registration and yield strongly influences material adoption.

OEM / system integration

OEM electrical and reliability requirements ultimately define approved material lists. Once a stack-up is qualified, the laminate can remain locked into a platform for years, giving successful suppliers recurring revenue.

Recent Developments

04 Mar 2026

Panasonic announced a 7.5 billion yen MEGTRON line in Guangzhou

Panasonic Industry said it will add a production line for MEGTRON multi-layer circuit-board materials at its Guangzhou factory. Initial manufacturing is planned for April 2027, and the investment forms part of a broader strategy to serve growing AI-server and high-speed networking demand in China. Panasonic Newsroom

12 Sep 2025

Panasonic set a plan to double MEGTRON capacity over five years

Panasonic Industry announced a 17 billion yen investment for a new MEGTRON facility at Ayutthaya, Thailand, with operations planned from November 2027. The company stated a goal to double total MEGTRON production capacity over five years, providing a clear supply-side signal for premium high-speed materials. Panasonic Newsroom

20 Feb 2025

IPC reported North American PCB shipments up 19.9% year over year

IPC’s January 2025 statistical release showed shipments up 19.9%, bookings up 44.1% and a 1.24 book-to-bill ratio. The figures point to stronger PCB demand conditions in the United States and Canada, supporting material consumption across domestic and imported board supply chains. IPC

15 Jan 2025

Panasonic advanced high-speed circuit-board material positioning

Panasonic Industry highlighted MEGTRON material development for next-generation high-speed transmission, illustrating the industry’s continuing move toward lower-loss formulations as data-center network speeds increase. Panasonic Industry

Report Scope & Segmentation

Attribute Scope
Market Copper Clad Laminate (CCL) and Prepreg
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
2025 Market Size USD 13.96 billion
2034 Market Size USD 19.66 billion
CAGR 3.9% (2026–2034)
Largest Market Asia Pacific (>87% share)
By Type Copper Clad Laminate (CCL); Prepreg
By Application Communication; Computer; Consumer Electronics; Vehicle Electronics; Industrial and Medical; Military and Space; Others
By End User PCB Manufacturers; Composite Material Fabricators; OEMs
By Performance Requirement Standard Performance; High-Frequency / High-Speed; High-Thermal Reliability
By Material Composition FR-4 Epoxy; Polyimide; Ceramic-based
Regions North America; Europe; Asia Pacific; South America; Middle East & Africa
Key Companies Kingboard Laminates Group, SYTECH, Panasonic, Nan Ya Plastic, EMC, ITEQ, DOOSAN, TUC, GDM International Technology Ltd., Hitachi Chemical (Showa Denko Materials), Isola, Nanya New Material Technology Co., Ltd., Rogers Corporation, Wazam New Materials, Chang Chun Group, Mitsubishi Electric, Guangdong Goworld Lamination Plant, Ventec International Group, Sumitomo, AGC

Frequently Asked Questions

What is the Copper Clad Laminate (CCL) and Prepreg market size in 2025?

The global Copper Clad Laminate (CCL) and Prepreg market is valued at USD 13,961.0 million in 2025. The figure follows the consistent growth path defined by the published USD 13.44 billion market value for 2024 and USD 18.22 billion endpoint for 2032. Demand is anchored in PCB production for communications, computing, consumer electronics, vehicles, industrial systems and aerospace applications.

What will the market reach by 2034?

The market is projected to reach USD 19,660.1 million by 2034, with USD 14,502.3 million estimated for 2026 and a 3.9% CAGR during 2026–2034. Value growth reflects both electronics volume and a mix shift toward lower-loss, higher-thermal and higher-reliability materials used in AI infrastructure, advanced communications and vehicle electronics.

Which region is the largest market?

Asia Pacific is the largest region and represents more than 87% of global demand. The region contains the largest concentration of laminate producers, PCB fabricators and electronics assembly operations. China, Taiwan, Japan, South Korea and Southeast Asia provide a tightly connected supply chain that supports both high-volume standard materials and growing demand for premium high-speed grades.

Which product type leads the market?

Copper Clad Laminate is the dominant product and accounts for close to 80% of demand. CCL is the foundational copper-and-dielectric panel used to create PCB circuitry, while prepreg bonds layers during multilayer lamination. Although prepreg is smaller by revenue, its consumption rises with board layer count and its material behavior is critical to thickness, registration and reliability.

Which application is the largest?

Communication is the largest application and represents more than 33% of demand. Routers, switches, base stations, optical transport and data-center networking use multilayer PCBs and increasingly require low-loss materials as data rates rise. AI infrastructure is strengthening this segment because high-speed switch fabrics and server platforms place tighter constraints on dielectric loss and signal integrity.

How is AI changing the CCL market?

AI servers increase the number and value of high-speed circuit boards used in accelerators, switches, storage and power systems. Higher serial data rates make dielectric loss and copper roughness more important, while high layer counts require precise prepreg flow and dimensional control. Panasonic’s announced MEGTRON investments in Thailand and China show suppliers adding dedicated premium capacity for this demand.

Why is automotive electronics important?

Vehicle electrification and ADAS increase the number of power, sensing, communications and computing boards in each vehicle. These systems often operate under heat, vibration and long service lives, increasing demand for high-Tg, low-CTE, CAF-resistant and thermally robust materials. Long automotive qualification cycles create barriers to entry but can support durable revenue after a material is approved.

What are the main restraints?

The market faces electronics-cycle volatility, raw-material and energy cost exposure, strong price competition in standard FR-4 and long qualification cycles for premium grades. Copper foil, glass cloth and resin changes can affect electrical and manufacturing performance, so customers cannot always substitute inputs quickly. This makes working-capital management, yield and supplier qualification important alongside nominal production capacity.

Who are the major companies?

Key participants include Kingboard Laminates Group, SYTECH, Panasonic, Nan Ya Plastic, EMC, ITEQ, DOOSAN, TUC, Isola, Rogers Corporation, Wazam New Materials, Ventec International Group, AGC and other regional suppliers. Competition spans scale, cost, low-loss electrical performance, thermal reliability, matched prepreg systems, technical support and the ability to supply qualified material consistently across global PCB factories.

Where are the strongest opportunities through 2034?

The strongest opportunities are low-loss materials for AI servers and 224 Gbps-class networks, high-reliability automotive systems, thermally enhanced substrates and regional second-source strategies. Suppliers that can combine advanced resin chemistry with stable high-volume manufacturing and customer process support are positioned to capture more value than companies focused only on undifferentiated commodity laminate area.

Research Sources & Evidence Base

View research sources used for this overview
  1. IPC. North American PCB Industry Sales Up 19.9 Percent in January, North American PCB shipment, booking and book-to-bill evidence, 20 February 2025.
  2. International Energy Agency. Global EV Outlook 2026 – Trends in electric cars, 2025 global, China and Europe electric-car sales evidence.
  3. Panasonic Industry. Investment of 7.5 Billion yen for a New MEGTRON Production Line in Guangzhou, China premium circuit-board-material capacity expansion, 4 March 2026.
  4. Panasonic Industry. Double the Production Capacity of MEGTRON Over the Next Five Years, Thailand capacity investment and global MEGTRON expansion plan, 12 September 2025.
  5. Panasonic Industry. MEGTRON Series, low-loss multilayer circuit-board material technical context.
Copper Clad Laminate (CCL) and Prepreg Market, Emerging Trends, Technological Advancements, and Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Copper Clad Laminate (CCL) and Prepreg Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Copper Clad Laminate (CCL) and Prepreg Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Copper Clad Laminate (CCL) and Prepreg Overall Market Size
2.1 Global Copper Clad Laminate (CCL) and Prepreg Market Size: 2024 VS 2031
2.2 Global Copper Clad Laminate (CCL) and Prepreg Market Size, Prospects & Forecasts: 2020-2031
2.3 Key Market Trends, Opportunity, Drivers and Restraints
2.3.1 Market Opportunities & Trends
2.3.2 Market Drivers
2.3.3 Market Restraints
3 Company Landscape
3.1 Top Copper Clad Laminate (CCL) and Prepreg Players in Global Market
3.2 Top Global Copper Clad Laminate (CCL) and Prepreg Companies Ranked by Revenue
3.3 Global Copper Clad Laminate (CCL) and Prepreg Revenue by Companies
3.4 Top 3 and Top 5 Copper Clad Laminate (CCL) and Prepreg Companies in Global Market, by Revenue in 2024
3.5 Global Companies Copper Clad Laminate (CCL) and Prepreg Product Type
3.6 Tier 1, Tier 2, and Tier 3 Copper Clad Laminate (CCL) and Prepreg Players in Global Market
3.6.1 List of Global Tier 1 Copper Clad Laminate (CCL) and Prepreg Companies
3.6.2 List of Global Tier 2 and Tier 3 Copper Clad Laminate (CCL) and Prepreg Companies
4 Sights by Product
4.1 Overview
4.1.1 Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Market Size Markets, 2024 & 2031
4.1.2 Copper Clad Laminate
4.1.3 Prepreg
4.2 Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue & Forecasts
4.2.1 Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2025
4.2.2 Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue, 2026-2031
4.2.3 Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
5 Sights by Application
5.1 Overview
5.1.1 Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Market Size, 2024 & 2031
5.1.2 Computer
5.1.3 Communication
5.1.4 Consumer Electronics
5.1.5 Vehicle Electronics
5.1.6 Industrial and Medical
5.1.7 Military and Space
5.1.8 Others
5.2 Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue & Forecasts
5.2.1 Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2025
5.2.2 Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue, 2026-2031
5.2.3 Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
6 Sights by Region
6.1 By Region – Global Copper Clad Laminate (CCL) and Prepreg Market Size, 2024 & 2031
6.2 By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue & Forecasts
6.2.1 By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2025
6.2.2 By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue, 2026-2031
6.2.3 By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
6.3 North America
6.3.1 By Country – North America Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2031
6.3.2 United States Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.3.3 Canada Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.3.4 Mexico Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4 Europe
6.4.1 By Country – Europe Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2031
6.4.2 Germany Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4.3 France Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4.4 U.K. Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4.5 Italy Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4.6 Russia Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4.7 Nordic Countries Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.4.8 Benelux Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.5 Asia
6.5.1 By Region – Asia Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2031
6.5.2 China Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.5.3 Japan Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.5.4 South Korea Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.5.5 Southeast Asia Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.5.6 India Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.6 South America
6.6.1 By Country – South America Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2031
6.6.2 Brazil Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.6.3 Argentina Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.7 Middle East & Africa
6.7.1 By Country – Middle East & Africa Copper Clad Laminate (CCL) and Prepreg Revenue, 2020-2031
6.7.2 Turkey Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.7.3 Israel Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.7.4 Saudi Arabia Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
6.7.5 UAE Copper Clad Laminate (CCL) and Prepreg Market Size, 2020-2031
7 Companies Profiles
7.1 Kingboard Laminates Group
7.1.1 Kingboard Laminates Group Corporate Summary
7.1.2 Kingboard Laminates Group Business Overview
7.1.3 Kingboard Laminates Group Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.1.4 Kingboard Laminates Group Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.1.5 Kingboard Laminates Group Key News & Latest Developments
7.2 SYTECH
7.2.1 SYTECH Corporate Summary
7.2.2 SYTECH Business Overview
7.2.3 SYTECH Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.2.4 SYTECH Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.2.5 SYTECH Key News & Latest Developments
7.3 Panasonic
7.3.1 Panasonic Corporate Summary
7.3.2 Panasonic Business Overview
7.3.3 Panasonic Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.3.4 Panasonic Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.3.5 Panasonic Key News & Latest Developments
7.4 Nan Ya Plastic
7.4.1 Nan Ya Plastic Corporate Summary
7.4.2 Nan Ya Plastic Business Overview
7.4.3 Nan Ya Plastic Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.4.4 Nan Ya Plastic Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.4.5 Nan Ya Plastic Key News & Latest Developments
7.5 EMC
7.5.1 EMC Corporate Summary
7.5.2 EMC Business Overview
7.5.3 EMC Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.5.4 EMC Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.5.5 EMC Key News & Latest Developments
7.6 ITEQ
7.6.1 ITEQ Corporate Summary
7.6.2 ITEQ Business Overview
7.6.3 ITEQ Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.6.4 ITEQ Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.6.5 ITEQ Key News & Latest Developments
7.7 DOOSAN
7.7.1 DOOSAN Corporate Summary
7.7.2 DOOSAN Business Overview
7.7.3 DOOSAN Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.7.4 DOOSAN Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.7.5 DOOSAN Key News & Latest Developments
7.8 TUC
7.8.1 TUC Corporate Summary
7.8.2 TUC Business Overview
7.8.3 TUC Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.8.4 TUC Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.8.5 TUC Key News & Latest Developments
7.9 GDM International Technology Ltd.
7.9.1 GDM International Technology Ltd. Corporate Summary
7.9.2 GDM International Technology Ltd. Business Overview
7.9.3 GDM International Technology Ltd. Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.9.4 GDM International Technology Ltd. Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.9.5 GDM International Technology Ltd. Key News & Latest Developments
7.10 Hitachi Chemical
7.10.1 Hitachi Chemical Corporate Summary
7.10.2 Hitachi Chemical Business Overview
7.10.3 Hitachi Chemical Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.10.4 Hitachi Chemical Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.10.5 Hitachi Chemical Key News & Latest Developments
7.11 Isola
7.11.1 Isola Corporate Summary
7.11.2 Isola Business Overview
7.11.3 Isola Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.11.4 Isola Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.11.5 Isola Key News & Latest Developments
7.12 Nanya New Material Technology Co., Ltd.
7.12.1 Nanya New Material Technology Co., Ltd. Corporate Summary
7.12.2 Nanya New Material Technology Co., Ltd. Business Overview
7.12.3 Nanya New Material Technology Co., Ltd. Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.12.4 Nanya New Material Technology Co., Ltd. Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.12.5 Nanya New Material Technology Co., Ltd. Key News & Latest Developments
7.13 Rogers Corporation
7.13.1 Rogers Corporation Corporate Summary
7.13.2 Rogers Corporation Business Overview
7.13.3 Rogers Corporation Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.13.4 Rogers Corporation Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.13.5 Rogers Corporation Key News & Latest Developments
7.14 Wazam New Materials
7.14.1 Wazam New Materials Corporate Summary
7.14.2 Wazam New Materials Business Overview
7.14.3 Wazam New Materials Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.14.4 Wazam New Materials Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.14.5 Wazam New Materials Key News & Latest Developments
7.15 Chang Chun Group
7.15.1 Chang Chun Group Corporate Summary
7.15.2 Chang Chun Group Business Overview
7.15.3 Chang Chun Group Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.15.4 Chang Chun Group Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.15.5 Chang Chun Group Key News & Latest Developments
7.16 Mitsubishi
7.16.1 Mitsubishi Corporate Summary
7.16.2 Mitsubishi Business Overview
7.16.3 Mitsubishi Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.16.4 Mitsubishi Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.16.5 Mitsubishi Key News & Latest Developments
7.17 Guangdong Goworld Lamination Plant
7.17.1 Guangdong Goworld Lamination Plant Corporate Summary
7.17.2 Guangdong Goworld Lamination Plant Business Overview
7.17.3 Guangdong Goworld Lamination Plant Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.17.4 Guangdong Goworld Lamination Plant Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.17.5 Guangdong Goworld Lamination Plant Key News & Latest Developments
7.18 Ventec International Group
7.18.1 Ventec International Group Corporate Summary
7.18.2 Ventec International Group Business Overview
7.18.3 Ventec International Group Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.18.4 Ventec International Group Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.18.5 Ventec International Group Key News & Latest Developments
7.19 Sumitomo
7.19.1 Sumitomo Corporate Summary
7.19.2 Sumitomo Business Overview
7.19.3 Sumitomo Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.19.4 Sumitomo Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.19.5 Sumitomo Key News & Latest Developments
7.20 AGC
7.20.1 AGC Corporate Summary
7.20.2 AGC Business Overview
7.20.3 AGC Copper Clad Laminate (CCL) and Prepreg Major Product Offerings
7.20.4 AGC Copper Clad Laminate (CCL) and Prepreg Revenue in Global Market (2020-2025)
7.20.5 AGC Key News & Latest Developments
8 Conclusion
9 Appendix
9.1 Note
9.2 Examples of Clients
9.3 DisclaimerList of Tables
Table 1. Copper Clad Laminate (CCL) and Prepreg Market Opportunities & Trends in Global Market
Table 2. Copper Clad Laminate (CCL) and Prepreg Market Drivers in Global Market
Table 3. Copper Clad Laminate (CCL) and Prepreg Market Restraints in Global Market
Table 4. Key Players of Copper Clad Laminate (CCL) and Prepreg in Global Market
Table 5. Top Copper Clad Laminate (CCL) and Prepreg Players in Global Market, Ranking by Revenue (2024)
Table 6. Global Copper Clad Laminate (CCL) and Prepreg Revenue by Companies, (US$, Mn), 2020-2025
Table 7. Global Copper Clad Laminate (CCL) and Prepreg Revenue Share by Companies, 2020-2025
Table 8. Global Companies Copper Clad Laminate (CCL) and Prepreg Product Type
Table 9. List of Global Tier 1 Copper Clad Laminate (CCL) and Prepreg Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Copper Clad Laminate (CCL) and Prepreg Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2024 & 2031
Table 12. Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn), 2020-2025
Table 13. Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn), 2026-2031
Table 14. Segmentation by Application– Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2024 & 2031
Table 15. Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 16. Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 17. By Region– Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2024 & 2031
Table 18. By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 19. By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 20. By Country – North America Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 21. By Country – North America Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 22. By Country – Europe Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 23. By Country – Europe Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 24. By Region – Asia Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 25. By Region – Asia Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 26. By Country – South America Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 27. By Country – South America Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 28. By Country – Middle East & Africa Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2025
Table 29. By Country – Middle East & Africa Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2026-2031
Table 30. Kingboard Laminates Group Corporate Summary
Table 31. Kingboard Laminates Group Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 32. Kingboard Laminates Group Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 33. Kingboard Laminates Group Key News & Latest Developments
Table 34. SYTECH Corporate Summary
Table 35. SYTECH Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 36. SYTECH Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 37. SYTECH Key News & Latest Developments
Table 38. Panasonic Corporate Summary
Table 39. Panasonic Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 40. Panasonic Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 41. Panasonic Key News & Latest Developments
Table 42. Nan Ya Plastic Corporate Summary
Table 43. Nan Ya Plastic Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 44. Nan Ya Plastic Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 45. Nan Ya Plastic Key News & Latest Developments
Table 46. EMC Corporate Summary
Table 47. EMC Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 48. EMC Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 49. EMC Key News & Latest Developments
Table 50. ITEQ Corporate Summary
Table 51. ITEQ Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 52. ITEQ Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 53. ITEQ Key News & Latest Developments
Table 54. DOOSAN Corporate Summary
Table 55. DOOSAN Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 56. DOOSAN Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 57. DOOSAN Key News & Latest Developments
Table 58. TUC Corporate Summary
Table 59. TUC Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 60. TUC Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 61. TUC Key News & Latest Developments
Table 62. GDM International Technology Ltd. Corporate Summary
Table 63. GDM International Technology Ltd. Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 64. GDM International Technology Ltd. Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 65. GDM International Technology Ltd. Key News & Latest Developments
Table 66. Hitachi Chemical Corporate Summary
Table 67. Hitachi Chemical Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 68. Hitachi Chemical Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 69. Hitachi Chemical Key News & Latest Developments
Table 70. Isola Corporate Summary
Table 71. Isola Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 72. Isola Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 73. Isola Key News & Latest Developments
Table 74. Nanya New Material Technology Co., Ltd. Corporate Summary
Table 75. Nanya New Material Technology Co., Ltd. Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 76. Nanya New Material Technology Co., Ltd. Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 77. Nanya New Material Technology Co., Ltd. Key News & Latest Developments
Table 78. Rogers Corporation Corporate Summary
Table 79. Rogers Corporation Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 80. Rogers Corporation Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 81. Rogers Corporation Key News & Latest Developments
Table 82. Wazam New Materials Corporate Summary
Table 83. Wazam New Materials Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 84. Wazam New Materials Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 85. Wazam New Materials Key News & Latest Developments
Table 86. Chang Chun Group Corporate Summary
Table 87. Chang Chun Group Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 88. Chang Chun Group Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 89. Chang Chun Group Key News & Latest Developments
Table 90. Mitsubishi Corporate Summary
Table 91. Mitsubishi Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 92. Mitsubishi Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 93. Mitsubishi Key News & Latest Developments
Table 94. Guangdong Goworld Lamination Plant Corporate Summary
Table 95. Guangdong Goworld Lamination Plant Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 96. Guangdong Goworld Lamination Plant Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 97. Guangdong Goworld Lamination Plant Key News & Latest Developments
Table 98. Ventec International Group Corporate Summary
Table 99. Ventec International Group Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 100. Ventec International Group Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 101. Ventec International Group Key News & Latest Developments
Table 102. Sumitomo Corporate Summary
Table 103. Sumitomo Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 104. Sumitomo Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 105. Sumitomo Key News & Latest Developments
Table 106. AGC Corporate Summary
Table 107. AGC Copper Clad Laminate (CCL) and Prepreg Product Offerings
Table 108. AGC Copper Clad Laminate (CCL) and Prepreg Revenue (US$, Mn) & (2020-2025)
Table 109. AGC Key News & Latest Developments

List of Figures
Figure 1. Copper Clad Laminate (CCL) and Prepreg Product Picture
Figure 2. Copper Clad Laminate (CCL) and Prepreg Segment by Type in 2024
Figure 3. Copper Clad Laminate (CCL) and Prepreg Segment by Application in 2024
Figure 4. Global Copper Clad Laminate (CCL) and Prepreg Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Copper Clad Laminate (CCL) and Prepreg Market Size: 2024 VS 2031 (US$, Mn)
Figure 7. Global Copper Clad Laminate (CCL) and Prepreg Revenue: 2020-2031 (US$, Mn)
Figure 8. The Top 3 and 5 Players Market Share by Copper Clad Laminate (CCL) and Prepreg Revenue in 2024
Figure 9. Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2024 & 2031
Figure 10. Segmentation by Type – Global Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 11. Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2024 & 2031
Figure 12. Segmentation by Application – Global Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 13. By Region – Global Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 14. By Country – North America Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 15. United States Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 16. Canada Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 17. Mexico Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 18. By Country – Europe Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 19. Germany Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 20. France Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 21. U.K. Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 22. Italy Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 23. Russia Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 24. Nordic Countries Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 25. Benelux Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 26. By Region – Asia Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 27. China Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 28. Japan Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 29. South Korea Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 30. Southeast Asia Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 31. India Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 32. By Country – South America Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 33. Brazil Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 34. Argentina Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 35. By Country – Middle East & Africa Copper Clad Laminate (CCL) and Prepreg Revenue Market Share, 2020-2031
Figure 36. Turkey Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 37. Israel Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 38. Saudi Arabia Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 39. UAE Copper Clad Laminate (CCL) and Prepreg Revenue, (US$, Mn), 2020-2031
Figure 40. Kingboard Laminates Group Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 41. SYTECH Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 42. Panasonic Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 43. Nan Ya Plastic Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 44. EMC Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 45. ITEQ Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 46. DOOSAN Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 47. TUC Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 48. GDM International Technology Ltd. Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 49. Hitachi Chemical Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 50. Isola Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 51. Nanya New Material Technology Co., Ltd. Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 52. Rogers Corporation Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 53. Wazam New Materials Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 54. Chang Chun Group Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 55. Mitsubishi Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 56. Guangdong Goworld Lamination Plant Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 57. Ventec International Group Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 58. Sumitomo Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 59. AGC Copper Clad Laminate (CCL) and Prepreg Revenue Year Over Year Growth (US$, Mn) & (2020-2025)