Key Statistics
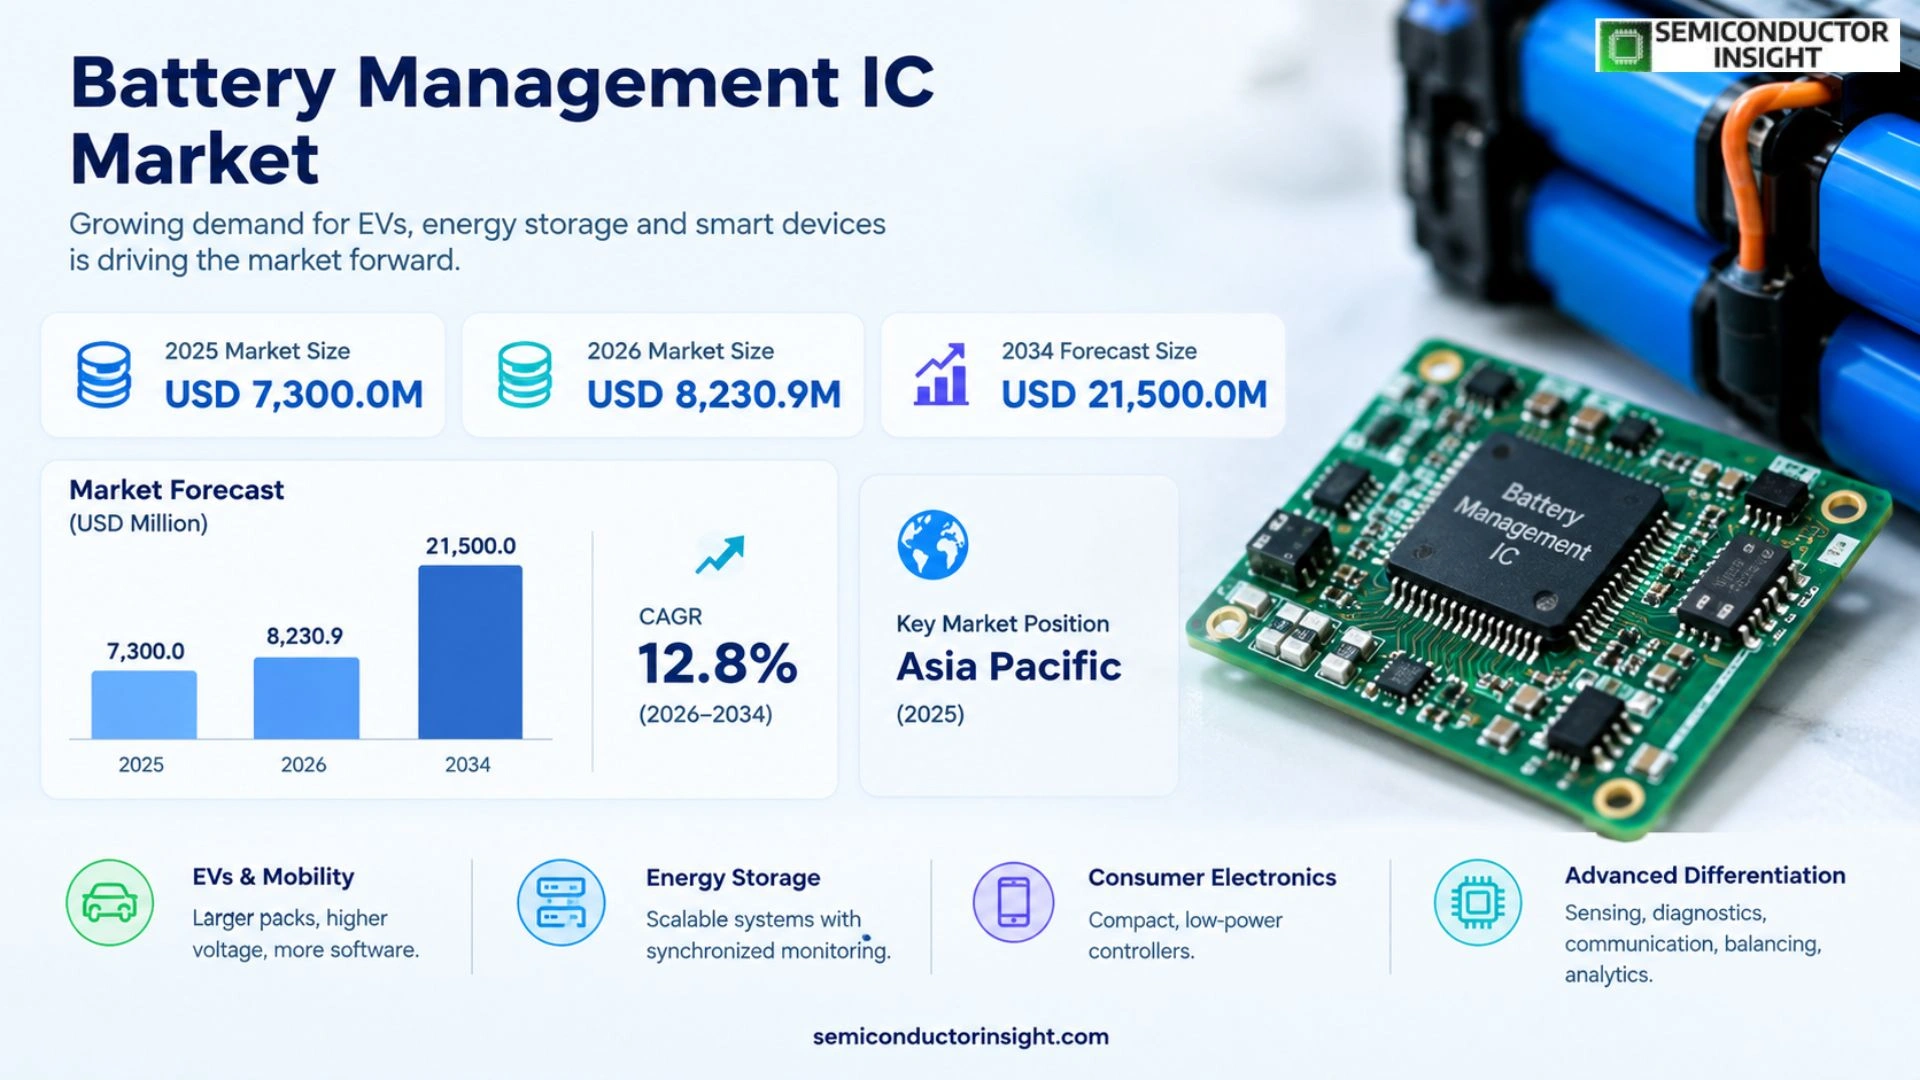
2025 Market Size
USD 7,300.0 million
2026 Estimated Size
USD 8,230.9 million
2034 Projected Size
USD 21,500.0 million
Largest Market in 2025
Asia Pacific
Key Takeaways
- Linear BMS ICs remain important where low noise, simple integration and predictable analog behavior are priorities, while switching and hybrid architectures gain value in larger and more complex battery systems.
- Electric Vehicles (EVs) are the leading application because high-voltage packs require precise cell measurement, balancing, fault detection and functional-safety support across hundreds of cells.
- Asia Pacific is the strongest regional demand center through EV production, battery manufacturing and energy-storage deployment in China, Japan and South Korea.
- System-on-Chip integration is strategically important because combining measurement, protection, communication and diagnostics reduces board area and shortens OEM development cycles.
- Electrochemical Impedance Spectroscopy is moving into the chipset. NXP’s BMA7418 platform brings synchronized EIS capability into automotive cell monitoring for more direct state-of-health diagnostics.
- Automotive safety remains a design gate. Current high-voltage BMS devices increasingly support ASIL-D-class system requirements, isolated daisy-chain communication and cell-level protection.
Battery Management IC Market Overview
Battery Management IC market is valued at USD 7,300.0 million in 2025, is estimated at USD 8,230.9 million in 2026, and is projected to reach USD 21,500.0 million by 2034, representing a CAGR of 12.8% during 2026–2034. Asia Pacific is the 2025 market-position reference used in this overview.
Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated
Battery management integrated circuits monitor rechargeable battery cells, estimate operating conditions, balance cell voltages and protect packs from unsafe voltage, current and temperature conditions. They are used in electric vehicles, consumer electronics, stationary energy storage, industrial equipment and other battery-powered systems where safety and usable energy depend on accurate measurement.
The market is expanding as battery packs become larger, higher voltage and more software defined. An electric vehicle can contain hundreds of series-connected cells, making synchronized voltage and temperature measurement essential to range estimation and fast charging. Stationary storage systems use similar functions at larger scale, while consumer products require compact low-power controllers for single-cell and small multi-cell packs.
Competitive differentiation is moving beyond basic voltage measurement toward synchronized sensing, diagnostics, communication, balancing and embedded analytics. NXP’s newest cell controllers add dedicated ADCs per channel and EIS capability, while Texas Instruments continues supporting stackable 16-cell monitoring with integrated protection and daisy-chain communication.
Segment Analysis: By Type
By type, the market is segmented into Linear BMS ICs, Switching BMS ICs, and Hybrid topology ICs. Linear BMS ICs lead the report’s type discussion because they offer low noise, straightforward design and minimal external circuitry.
| Segment Category |
Sub-Segments |
Key Insights |
| By Type |
Linear BMS ICs |
Favored where precise low-noise measurement and simple architecture matter. They are widely used in compact systems and legacy platforms with strong cost sensitivity. |
| By Type |
Switching BMS ICs |
Use switching conversion or control techniques to improve efficiency in charging, balancing and battery power management, especially as pack power rises. |
| By Type |
Hybrid topology ICs |
Combine linear precision with switching efficiency or integrate several control functions in one chipset, supporting higher-performance EV and energy-storage systems. |
Why are highly integrated BMS chipsets gaining share?
High-voltage packs need cell monitoring, pack current measurement, isolation, balancing, safety diagnostics and communication. Integrating more of these functions into a coordinated chipset reduces wiring and board area and simplifies the safety case. It also improves measurement synchronization, which is important for state-of-charge, state-of-health and impedance-based diagnostics.
Segment Analysis: By Application
By application, the market covers Electric Vehicles (EVs), Consumer Electronics, Renewable-Energy Storage, and Others. Electric Vehicles lead because battery safety, fast charging and usable range depend directly on accurate pack monitoring and protection.
| Application |
Demand characteristics |
Key Insights |
| Electric Vehicles (EVs) |
High-voltage packs use stacked cell monitors, pack controllers, communication gateways and safety logic to supervise hundreds of cells. |
The leading application and the main driver of ASIL-D-class monitoring, isolated communications and high-accuracy diagnostics. |
| Consumer Electronics |
Phones, laptops, wearables and portable devices use compact single-cell or small-stack battery-management ICs for charging, gauging and protection. |
A large-volume segment where low power, integration and cost are critical. |
| Renewable-Energy Storage |
Residential, commercial and grid batteries use multi-cell monitoring, balancing, temperature sensing and remote diagnostics. |
A major growth segment as energy storage scales with solar, wind and grid-stability investment. |
| Others |
Includes industrial vehicles, power tools, medical equipment, robotics, telecom backup and specialty battery systems. |
A diversified opportunity where safety, runtime and lifecycle requirements vary by end use. |
Why are EV battery-management ICs becoming more sophisticated?
Higher-voltage packs and faster charging narrow the allowable margin for cell imbalance, thermal excursions and measurement error. New devices add faster synchronized ADCs, stronger diagnostics, hardware protection and richer communication so OEMs can estimate battery health more accurately and detect faults earlier without adding excessive external sensing components.
Regional Analysis
Asia Pacific is the largest and fastest-growing Battery Management IC market, supported by EV and battery manufacturing in China, Japan and South Korea. North America and Europe remain major high-value markets for automotive, energy storage and semiconductor design.
What differentiates regional Battery Management IC demand?
Asia Pacific combines cell production, EV manufacturing and energy-storage deployment. North America is strong in EV platforms, grid storage and BMS semiconductor design. Europe has deep automotive safety and electrification requirements. South America and Middle East & Africa are smaller but gaining demand through renewable energy, commercial EVs and industrial battery systems.
| Region |
Position |
Growth outlook |
Demand profile |
What decides supplier selection |
| Asia Pacific |
Largest & fastest-growing |
Very strong |
EV, battery and ESS manufacturing |
Accuracy, cost, local support and safety qualification |
| North America |
Major high-value market |
Strong |
EV, grid storage and semiconductor design |
Functional safety, diagnostics and software ecosystem |
| Europe |
Automotive & energy-storage specialist |
Strong |
EV, industrial and stationary storage |
ASIL support, lifecycle and regulation |
| South America |
Developing market |
Selective |
Renewables, commercial EV and industrial |
Cost, availability and application support |
| Middle East & Africa |
Emerging storage market |
Selective high growth |
Solar storage, telecom and fleet electrification |
Ruggedness, safety and supply continuity |
Asia Pacific LARGEST & FASTEST-GROWING
Why does Asia Pacific lead Battery Management IC demand?
China, Japan and South Korea combine large EV production, battery-cell manufacturing and fast-growing stationary storage. The same region also hosts major automotive and electronics supply chains, which accelerates design-in and high-volume adoption of battery monitors and protection ICs.
Market positionLargest region
Growth outlookVery strong
Demand profileEV, battery and ESS scale
Market access gateAccuracy, cost and automotive qualification
| Country / market |
Position in region |
Evidence-led demand logic |
| China |
Largest volume engine |
EV production, battery factories and grid storage create the deepest demand for high-voltage cell monitoring. |
| Japan |
Automotive technology hub |
Vehicle OEMs and semiconductor suppliers support precision BMS design and long qualification cycles. |
| South Korea |
Battery manufacturing hub |
Large cell manufacturers and EV supply chains create demand for high-accuracy monitoring and pack diagnostics. |
| India |
Fast-growing storage and mobility market |
Electric two-wheelers, passenger EVs and stationary storage broaden BMS demand across voltage classes. |
24 Jun 2026 – NXP releases 18-cell BMA7418 data sheet
NXP’s BMA7418 supports EIS, dedicated high-accuracy ADCs and synchronized cell monitoring.
Market relevance: Integrated diagnostics and high channel synchronization raise the value of the monitoring IC in advanced packs.
13 Jul 2026 – NXP releases BMx7318 production documentation
The 18-channel controller supports automotive HVBMS, industrial ESS and 48 V battery systems.
Market relevance: One controller family can address both mobility and stationary storage, expanding design reuse.
2025–2026 – EV and ESS capacity continues to expand
Regional battery and vehicle production remains the largest physical demand base for BMS electronics.
Market relevance: Local engineering and high-volume qualification favor suppliers with strong Asian support networks.
Full-report coverage: Detailed sub-market, geography, supplier and forecast analysis is retained in the full study; this overview focuses on the geographies with the clearest supportable demand mechanisms.
North America HIGH-VALUE EV & ESS MARKET
Why is North America strategically important?
The United States has major EV platforms, grid-scale storage projects, data-center backup applications and a large analog-semiconductor design base. Buyers emphasize functional safety, precision sensing and scalable software because battery systems are increasingly integrated with vehicle and grid control.
Market positionMajor high-value market
Growth outlookStrong
Demand profileEV and grid storage
Market access gateDiagnostics, safety and software
| Country / market |
Position in region |
Evidence-led demand logic |
| United States |
Primary regional market |
Automotive electrification, grid storage and industrial battery systems support advanced BMS chipsets. |
| Canada |
Energy-storage and mobility niche |
Renewables and vehicle programs create selective demand for high-reliability monitoring. |
| Mexico |
Automotive manufacturing bridge |
Vehicle assembly brings BMS content through North American OEM and Tier-1 programs. |
11 Jun 2026 – TI updates BQ79616
Texas Instruments’ 16-cell monitor, balancer and protector supports stackable high-voltage BMS designs.
Market relevance: Active monitoring platforms show continuing demand for precise multi-cell measurement and integrated protection.
10 Mar 2026 – NXP EIS software enablement released
NXP published software support for EIS measurements using BMA7418 and related BMS devices.
Market relevance: Software and silicon are becoming more tightly coupled in advanced battery diagnostics.
2025–2026 – grid storage expands
Battery energy-storage systems require scalable monitoring and fault detection across large series-parallel packs.
Market relevance: Stationary storage broadens BMS IC demand beyond vehicle production cycles.
Full-report coverage: Detailed sub-market, geography, supplier and forecast analysis is retained in the full study; this overview focuses on the geographies with the clearest supportable demand mechanisms.
Europe AUTOMOTIVE SAFETY MARKET
What drives European BMS IC demand?
Europe’s premium automotive and industrial markets require high functional-safety performance, long lifecycle support and precise battery monitoring. EV adoption and stationary storage add demand for multi-cell stacks and sophisticated diagnostics, while regional semiconductor companies provide strong local engineering support.
Market positionMajor premium market
Growth outlookStrong
Demand profileAutomotive, industrial and ESS
Market access gateSafety, lifecycle and regulation
| Country / market |
Position in region |
Evidence-led demand logic |
| Germany |
Automotive anchor |
Premium EV and industrial programs require high-reliability battery-management electronics. |
| France |
Mobility and energy market |
EV platforms and grid-storage investment support BM
-
14 July 2026 Industry investment
SEMI raised its 2026 semiconductor-equipment outlook to a record USD 165.9 billion. Wafer-fab equipment is expected to account for most of the increase, supporting demand for core process tools such as CMP.
Source
-
3 September 2025 Advanced packaging
EBARA joined the JOINT3 consortium to develop panel-level CMP for next-generation organic interposers. The initiative uses large 515 × 510 mm panels and expands CMP into new packaging form factors.
Source
-
2 June 2025 R&D capacity
EBARA completed its V8 development building at Fujisawa with a primary focus on semiconductor equipment including CMP systems. The facility expands development and customer-support capability.
Source
-
19 December 2024 Production capacity
EBARA completed a new Kumamoto production building designed to increase semiconductor-equipment capacity by 1.5 times. CMP systems are a core product manufactured at the site.
Source
Report Scope & Segmentation
| Attribute |
Coverage |
| Report title |
Chemical Mechanical Polishing Machine (CMP) Market, Emerging Trends, Technological Advancements, and Business Strategies 2026-2033 |
| Base Year |
2025 |
| Estimated Year |
2026 |
| Forecast Period |
2026–2034 |
| By Type |
300MM Polishing Machine; 200MM Polishing Machine; Others |
| By Application |
Semiconductor Plants; Research Institutes |
| Regions |
North America; Europe; Asia Pacific; South America; Middle East & Africa |
| Companies |
Applied Materials; EBARA Corporation; KC Tech; ACCRETECH; Tianjin Huahaiqingke; Logitech Ltd.; Revasum; Alpsitec; Semicore Microelectronics; Sizone Tech |
| Customization scope |
Country, segment, company, application, technology, production and competitive-detail customization available within the study scope. |
Frequently Asked Questions
What is the size of the Chemical Mechanical Polishing Machine market?
The global CMP machine market is valued at USD 3,240.0 million in 2025, is estimated at USD 3,581.5 million in 2026, and is projected to reach USD 7,983.1 million by 2034, representing a 10.5% CAGR during 2026–2034. The standardized 2025–2034 series is used consistently across the overview so market size, forecast outlook and growth rate remain on one time basis. Commercial demand is shaped by AI-driven 300mm fab investment, advanced-node logic, HBM and DRAM, higher-layer 3D NAND, hybrid bonding, panel-level packaging, and tighter planarization control.
Which geography leads the CMP machine market?
Asia is the largest reported geography with more than 68% share in the report scope, reflecting the concentration of foundry and memory production in Taiwan, South Korea, China and Japan. Regional leadership reflects installed production or consumption, customer concentration, supplier ecosystems and end-market intensity. Country discussion focuses on markets with clear operating drivers rather than forcing unsupported country shares. Supplier selection in these markets therefore reflects local service, qualification history and supply assurance as well as headline component performance.
Which CMP machine type leads?
300MM Polishing Machine leads because the largest advanced logic, DRAM, NAND and foundry fabs use 300mm wafers. Segment leadership matters because suppliers allocate R&D, capacity and channel resources toward the product classes with the strongest combination of volume, qualification value and system relevance. Over the forecast period, the mix can still shift toward higher-value variants as technical requirements rise. This remains commercially relevant because design-in decisions can persist for several product generations once performance and reliability are validated.
Which application is largest?
Semiconductor Plants dominate because CMP is a repeated production process used across isolation, interconnect, gate-stack, memory and advanced-packaging flows. Application demand also depends on design cycles, qualification requirements, replacement timing and end-user investment, so suppliers that solve a measurable performance, efficiency or reliability problem are better positioned to defend design wins. Long design cycles can make successful application wins durable and commercially attractive for qualified suppliers.
Why is advanced packaging important for CMP?
Hybrid bonding and stacked AI packages require extremely flat copper and dielectric surfaces. CMP therefore becomes a critical back-end process as well as a front-end wafer step. The commercial importance of this technology comes from improving system performance or simplifying implementation while balancing cost, efficiency, reliability, integration and qualification requirements. That system-level value is the main reason the technology can command a premium over simpler alternatives in demanding use cases.
What is changing in CMP process control?
Real-time endpoint detection, spectroscopy, eddy-current sensing, profile control and integrated cleaning are becoming more important as allowable non-uniformity and defectivity shrink. This trend affects both component selection and the surrounding system architecture, so buyers increasingly evaluate the complete power, thermal, signal or manufacturing outcome rather than one headline specification. Vendors that support application design and validation can turn this technical shift into longer customer relationships.
What are the main restraints?
High equipment cost, complex process tuning, sensitivity to pads and slurries, and the environmental burden of chemistry and water are the main restraints. These constraints influence where adoption is fastest and which suppliers can earn premium margins. Proven reliability, application engineering, supply continuity and qualification support can reduce several of these barriers. These barriers can also protect established suppliers once their devices or systems are approved in production programs.
Who are the major CMP machine companies?
Major companies include Applied Materials, EBARA, KC Tech, ACCRETECH, Tianjin Huahaiqingke, Logitech, Revasum, Alpsitec, Semicore Microelectronics and Sizone Tech. Competitive position depends on breadth of qualified products, manufacturing scale, customer support, process technology and participation in higher-value applications rather than market presence alone. This is why product breadth and engineering support remain meaningful competitive differentiators throughout the forecast period. In the Chemical Mechanical Polishing Machine (CMP) market, buyers therefore evaluate lifecycle support, technical fit and supply continuity alongside the headline specification.
Why does panel-level packaging create a new opportunity?
Large organic panels have different mechanics, dimensions and uniformity challenges from round wafers, creating demand for CMP platforms specifically engineered for panel-level interposers. The shift is important because packaging, integration or control architecture can improve usable system performance without requiring a complete change in the end application, leaving room for differentiated products even in mature markets. Suppliers that combine device performance with manufacturability and qualification support are best placed to monetize the shift.
Where are the strongest opportunities?
The strongest opportunities are in hybrid-bonding CMP, panel-level packaging, adaptive process control and upgrades for specialty 200mm fabs. Opportunity is strongest where a clear system bottleneck is emerging and suppliers can solve it with better performance, integration, capacity or lifecycle support. The most attractive niches also tend to have higher qualification barriers. That combination of structural demand and qualification barriers supports the most defensible growth opportunities.
Research Sources & Evidence Base
View research sources used for this overview
- Applied Materials. Opta Quad CMP for Advanced Packaging, 2026 advanced-packaging CMP, hybrid bonding and real-time process control..
- Applied Materials. Reflexion LK CMP, 300mm CMP platform, endpoint methods, cleaning and profile control..
- EBARA Corporation. JOINT3 Panel-Level Packaging Consortium, Panel-level CMP development for large organic interposers..
- EBARA Corporation. Fujisawa V8 Development Building, CMP development and semiconductor-equipment support capacity..
- EBARA Corporation. Semiconductor Manufacturing Equipment, CMP technology, installed base and precision-machining role..
- SEMI. 2026 Semiconductor Equipment Forecast, 2026 global equipment investment and wafer-fab equipment growth..
- SEMI. 300mm Fab Outlook 2026, 300mm fab spending, capacity and AI-driven investment context..
|
:touch”>
| Competitive tier |
Representative companies |
Commercial basis |
| Global module leaders |
Kingston; Micron |
Large distribution, server validation, DRAM technology access and high-capacity memory. |
| Asian diversified specialists |
ADATA; Transcend; Apacer; Team Group; Innodisk; Kingmax |
Gaming, industrial, embedded and server memory with rapid product cycles. |
| OEM / regional suppliers |
Ramaxel; MA Labs; Tigo; Corsair |
Client, gaming and system-OEM channels with price and brand differentiation. |
Key Participants
Kingston, Ramaxel, ADATA, Micron (Crucial), Transend, MA Labs, Tigo, Apacer, Corsair, Team Group, Kingmax Semiconductor, Innodisk.
Production Capacity Analysis
DIMM manufacturing combines DRAM sourcing, multilayer module PCB fabrication, SMT assembly, SPD programming, thermal design and high-speed electrical validation. Server modules add RCD, PMIC, SPD hub and temperature-sensing components, while 3DS products stack DRAM dies using TSVs.
DRAM devices are the largest value input and drive module capacity, speed and power. Module suppliers either purchase DRAM on the merchant market or use captive DRAM, exposing margins to memory price cycles.
DDR5 raises PCB and support-IC complexity. On-module power management, higher data rates and registered clocking require tighter signal-integrity design and more extensive validation than older DDR4 modules.
Final test includes functional memory screening, speed binning, SPD programming and platform compatibility. Industrial and server products can add burn-in, locked component bills, extended-temperature testing and formal change control.
| Capacity layer |
Where it concentrates |
Commercial constraint |
| DRAM wafer & package supply |
South Korea, United States, Taiwan and China |
DRAM node, density, price, yield and long-term allocation. |
| Module PCB & support ICs |
Taiwan, China and global electronics hubs |
Signal integrity, RCD/PMIC availability and PCB quality. |
| Assembly & test |
Asia Pacific, United States and global module plants |
SPD programming, speed binning, ECC validation and yield. |
| Platform qualification |
Server OEMs, motherboard vendors and industrial customers |
Compatibility, controlled BOM and long-term reliability. |
Market Dynamics
DIMM demand is driven by higher memory content per system and the DDR5 transition. Revenue remains exposed to DRAM pricing, but AI servers and high-capacity registered memory are increasing the value of the premium product mix.
Market Drivers
| Factor |
Directional impact |
Why it matters |
| AI and cloud servers |
High |
More CPU cores and larger host-memory pools increase capacity per socket. |
| DDR5 platform refresh |
High |
New CPUs migrate client and server systems away from DDR4. |
| Workstation and gaming upgrades |
Medium-High |
Professional and enthusiast users adopt faster and higher-capacity modules. |
| Industrial edge computing |
Medium |
Local analytics and machine vision raise embedded memory requirements. |
AI expands host memory alongside accelerator memory
Large models and orchestration tasks require CPU-attached DRAM for preprocessing, databases, KV cache offload and system software. This supports high-capacity RDIMM even when HBM is the accelerator’s primary memory.
DDR5 raises bandwidth and module content
DDR5 increases transfer rates and adds PMIC and dual-subchannel architecture, increasing both performance and the complexity of finished modules.
Professional users upgrade capacity faster than basic office PCs
Engineering, simulation, media and local AI workloads can use 64GB, 128GB or more, supporting premium desktop and workstation DIMMs.
Industrial systems need more data locally
Machine vision and edge inference raise memory footprints while factories still require controlled BOMs and extended availability.
Market Restraints
| Factor |
Directional impact |
Why it matters |
| DRAM price cyclicality |
High |
Module ASPs move with underlying DRAM supply-demand cycles. |
| Long client replacement cycles |
Medium-High |
PC users can keep systems and memory for several years. |
| Platform incompatibility |
High |
RDIMM, UDIMM and different DDR generations are not interchangeable. |
| Alternative memory form factors |
Medium |
SOCAMM2, CXL and other architectures can shift some server capacity away from standard DIMMs. |
DRAM cycles create inventory risk
Module makers can buy memory at high prices and then face rapid ASP declines. Inventory discipline is therefore as important as product design in commodity segments.
Memory upgrades do not always require frequent replacement
DIMMs are reliable and reusable, and many users upgrade only when applications exceed current capacity or a platform changes DDR generation.
Compatibility creates fragmented demand
A server board designed for RDIMM cannot accept ordinary UDIMM, and DDR5 modules are mechanically and electrically incompatible with DDR4. Suppliers must manage many validated SKUs.
New memory architectures can compete for high-value workloads
Low-power modular server memory and CXL expansion can move some capacity outside conventional DIMM channels, especially in AI infrastructure.
Market Opportunities
256GB DDR5 RDIMM
High-capacity modules allow AI servers to scale memory per socket and reduce slot count.
12,800 MT/s MRDIMM
Multiplexed rank architectures can relieve CPU memory-bandwidth bottlenecks.
Industrial DDR5
Rugged and long-lifecycle DDR5 can serve edge AI, automation and embedded servers.
High-capacity workstation memory
Engineering and local AI workloads support premium desktop module demand.
Supply Chain Analysis
DRAM Supply
Memory manufacturers provide DDR4/DDR5 dies and packages at required density and speed.
Module PCB & Design
Module vendors design UDIMM, RDIMM, LR-DIMM and advanced registered architectures.
Assembly & Validation
DRAM and support ICs are mounted, programmed, binned and electrically tested.
OEM / Channel Distribution
Modules reach server OEMs, PC makers, industrial customers, distributors and retail buyers.
DRAM Supply. Underlying DRAM availability and pricing set the largest part of module cost. Suppliers with captive memory or long-term supply agreements can reduce volatility.
Module PCB & Design. High-speed DDR5 requires tight routing, power integrity and support-IC coordination. Registered server modules add more design complexity than standard client DIMMs.
Assembly & Validation. Testing verifies memory cells, signal timing and SPD configuration. Server and industrial products need more extensive qualification than retail gaming memory.
OEM / Channel Distribution. Server memory moves through validated OEM ecosystems, while client modules use retail and e-commerce channels. The commercial model therefore differs sharply by application.
Recent Developments in the Dual in-line Memory Module (DIMM) Market
Developments tracked to September 2026. Entries use official publication dates where available.
-
30 July 2026Bandwidth
Innodisk introduced DDR5 12,800 MT/s MRDIMM for AI, LLM and robotics workloads. The MRCD/MDB architecture delivers 60% more bandwidth than DDR5-8000 RDIMM.
Source
-
May 2026AI memory
Micron highlighted its 256GB DDR5 RDIMM and broader AI memory portfolio at COMPUTEX 2026. The portfolio emphasizes higher capacity, speed and power efficiency for data-center workloads.
Source
-
12 May 2026Capacity
Micron sampled 256GB DDR5 RDIMMs using 1-gamma DRAM and 3DS TSV packaging. The modules support speeds up to 9,200 MT/s and target next-generation AI and HPC servers.
Source
-
3 March 2026Alternative module
Micron sampled 256GB LPDRAM SOCAMM2 for data-center infrastructure. The lower-power form factor shows that modular server memory is diversifying beyond conventional RDIMM.
Source
-
30 October 2025Industrial DDR5
Innodisk launched DDR5-7200 RDIMM for advanced AI workloads with capacities up to 64GB. The product combines higher data rate with industrial validation and edge-server reliability.
Source
Report Scope & Segmentation
| Attribute |
Coverage |
| Report title |
Dual in-line Memory Module (DIMM) Market Emerging Trends, Technological Advancements, and Business Strategies (2024-2030) |
| Base Year |
2025 |
| Estimated Year |
2026 |
| Forecast Period |
2026–2034 |
| By Type |
UDIMM; FB-DIMM; RDIMM; LR-DIMM; Other |
| By Application |
Computers; Server; Industrial; Aerospace and Defense; Manufaturing |
| Regions |
North America; Europe; Asia Pacific; South America; Middle East & Africa |
| Companies |
Kingston; Ramaxel; ADATA; Micron (Crucial); Transend; MA Labs; Tigo; Apacer; Corsair; Team Group; Kingmax Semiconductor; Innodisk |
| Customization scope |
Country, segment, company, application, technology, production and competitive-detail customization available within the study scope. |
Frequently Asked Questions
What is the size of the Dual in-line Memory Module market?
The market is valued at USD 13,228.8 million in 2025, is estimated at USD 14,181.5 million in 2026, and is projected to reach USD 24,737.3 million by 2034, representing a 7.2% CAGR during 2026–2034. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. For the Dual in-line Memory Module (DIMM) market, this also affects supplier qualification, product positioning and purchasing decisions across the 2026–2034 forecast period.
Which region leads the DIMM market?
North America is the largest market reference used in this overview, supported by the reported U.S. market size, hyperscale data centers and enterprise server demand. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. Buyers therefore evaluate lifecycle support, technical fit, application performance and supply continuity alongside the headline device or system specification.
Which DIMM type leads by broad volume?
UDIMM remains the broad client-volume type, while RDIMM and LR-DIMM capture higher value in servers. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. This remains commercially important because successful design-in decisions can persist for several product generations once performance, reliability and availability are validated. For the Dual in-line Memory Module (DIMM) market, this also affects supplier qualification, product positioning and purchasing decisions across the 2026–2034 forecast period.
Which application is largest?
Computers remain the largest application in the report segmentation, while Server is the strongest high-value growth segment. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. For the Dual in-line Memory Module (DIMM) market, this also affects supplier qualification, product positioning and purchasing decisions across the 2026–2034 forecast period. Buyers therefore evaluate lifecycle support, technical fit, application performance and supply continuity alongside the headline device or system specification.
Why is DDR5 important?
DDR5 raises memory bandwidth, reduces operating voltage, adds on-module power management and supports higher capacities, making it the central technology transition across new client and server platforms. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. Buyers therefore evaluate lifecycle support, technical fit, application performance and supply continuity alongside the headline device or system specification.
What is MRDIMM?
MRDIMM uses multiplexed registering and data-buffer architecture to access ranks more efficiently and raise effective memory bandwidth for high-core-count server processors. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. This remains commercially important because successful design-in decisions can persist for several product generations once performance, reliability and availability are validated.
What are the main restraints?
DRAM price cyclicality, long replacement cycles, platform incompatibility and competing memory architectures such as SOCAMM2 and CXL are the main restraints. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. For the Dual in-line Memory Module (DIMM) market, this also affects supplier qualification, product positioning and purchasing decisions across the 2026–2034 forecast period.
Who are the major DIMM companies?
Major companies include Kingston, Ramaxel, ADATA, Micron, Transend, Apacer, Corsair, Team Group, Kingmax and Innodisk. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. Buyers therefore evaluate lifecycle support, technical fit, application performance and supply continuity alongside the headline device or system specification. This remains commercially important because successful design-in decisions can persist for several product generations once performance, reliability and availability are validated.
Why are 256GB RDIMMs important for AI?
Larger modules increase CPU-attached memory per socket without consuming additional DIMM slots, helping AI and HPC servers scale capacity while controlling power and platform complexity. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. This remains commercially important because successful design-in decisions can persist for several product generations once performance, reliability and availability are validated.
Where are the strongest opportunities?
The strongest opportunities are in high-capacity DDR5 RDIMM, MRDIMM, industrial DDR5 and premium workstation memory. This point remains commercially relevant because qualification, lifecycle support, supply continuity and system-level performance can materially affect supplier selection during the 2026–2034 forecast period. For the Dual in-line Memory Module (DIMM) market, this also affects supplier qualification, product positioning and purchasing decisions across the 2026–2034 forecast period. Buyers therefore evaluate lifecycle support, technical fit, application performance and supply continuity alongside the headline device or system specification.
Research Sources & Evidence Base
View research sources used for this overview
- Micron Technology. 256GB DDR5 RDIMM Sampling, 2026 high-capacity 1-gamma RDIMM and 3DS TSV packaging..
- Micron Technology. DDR5 and MRDIMM Technology, DDR5 bandwidth, RDIMM speeds and MRDIMM positioning..
- Micron Technology. DRAM Modules, Current RDIMM, MRDIMM, UDIMM and related module portfolio..
- Innodisk. DDR5 12,800 MT/s MRDIMM, 2026 MRDIMM bandwidth for AI and HPC..
- Innodisk. DDR5-7200 RDIMM, 2025 industrial/server DDR5 RDIMM development..
- Micron Technology. 256GB SOCAMM2, 2026 alternative modular data-center memory architecture..

 Download Sample Report PDF