
Key Statistics
Key Takeaways
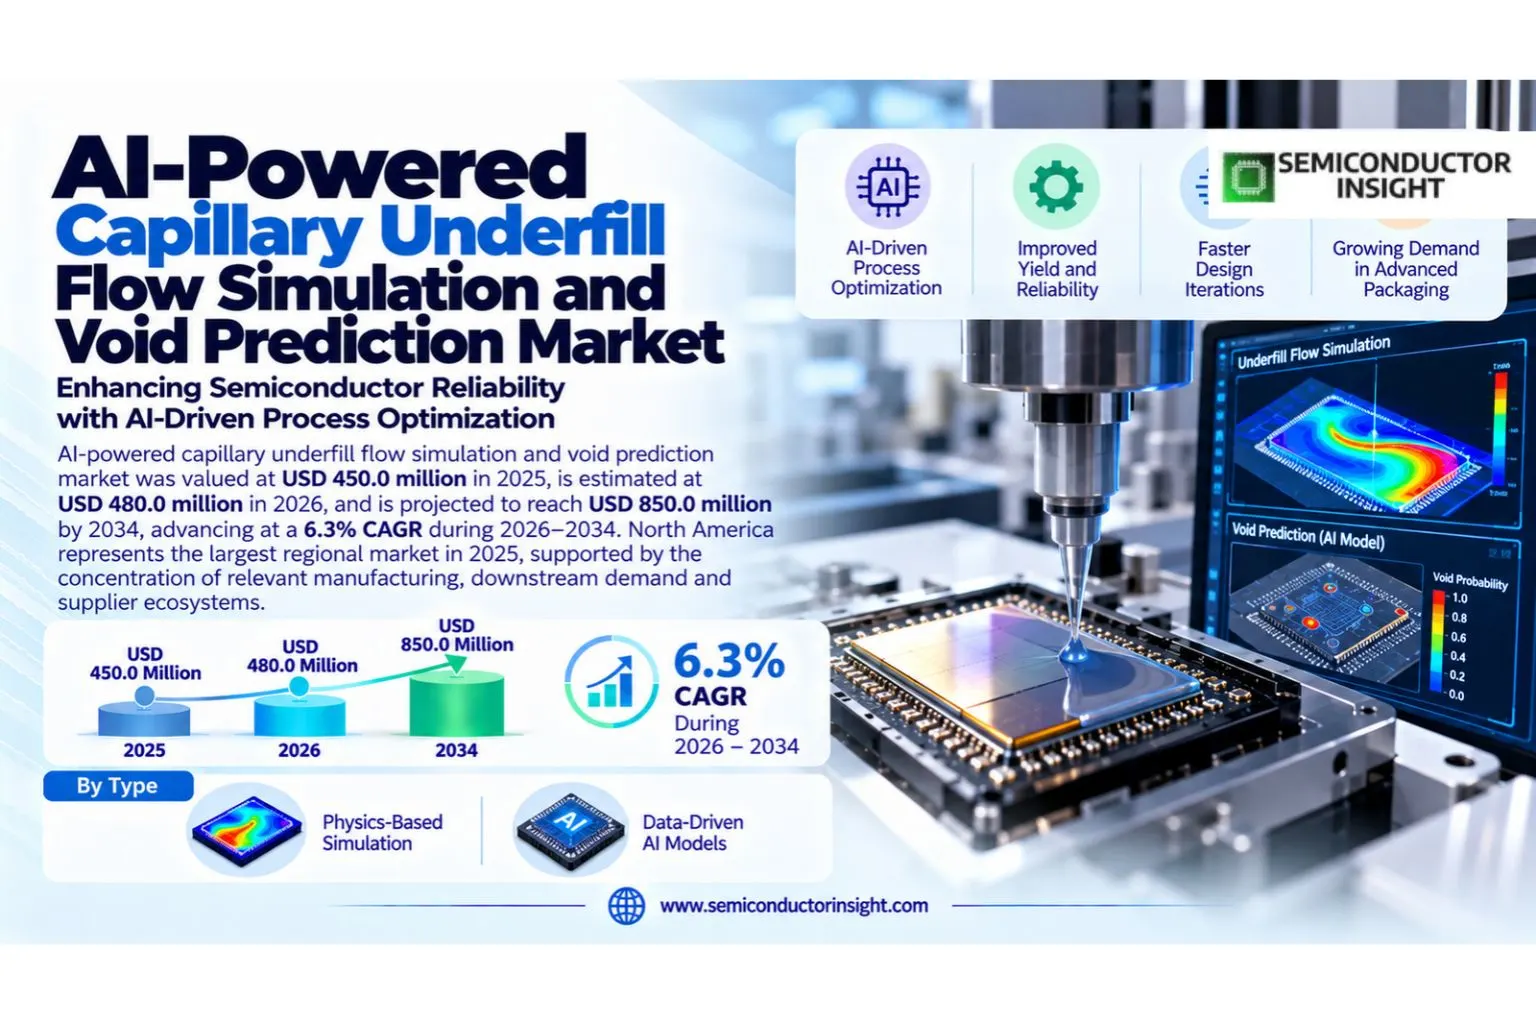
- AI-powered capillary underfill flow simulation and void prediction market was valued at USD 450.0 million in 2025 and is projected to reach USD 850.0 million by 2034, representing a 6.3% CAGR over 2026–2034.
- Physics-based simulation remains the reliability foundation because capillary flow depends on surface tension, viscosity, temperature, gap height and geometry; data-driven models add speed when they are trained and validated against trusted physics and process data.
- Underfill flow prediction and void mitigation are the highest-value use cases because defects can compromise mechanical integrity, thermal performance and long-term reliability in advanced packages.
- North America is the most mature market because leading EDA vendors, advanced-packaging customers and semiconductor design organizations are concentrated in the region, while Asia Pacific is the fastest scaling manufacturing environment.
- Hybrid CFD-AI workflows are emerging as the preferred architecture because they combine explainable physics with faster optimization across large design spaces and repeated packaging configurations.
AI-Powered Capillary Underfill Flow Simulation and Void Prediction Market Overview
AI-powered capillary underfill flow simulation and void prediction market was valued at USD 450.0 million in 2025, is estimated at USD 480.0 million in 2026, and is projected to reach USD 850.0 million by 2034, advancing at a 6.3% CAGR during 2026–2034. North America represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.
AI-powered capillary-underfill simulation combines computational fluid dynamics, material rheology, package geometry and machine-learning methods to predict how underfill flows beneath flip-chip or multi-die assemblies and where voids are likely to form. The tools help packaging engineers explore dispense patterns, temperature profiles, material properties and gap dimensions before physical builds, reducing trial-and-error during package development.
The market is tied directly to advanced packaging complexity. Chiplets, 2.5D interposers, 3D stacking and high-density AI packages create tighter spaces, more interfaces and larger thermal gradients. These conditions make underfill behavior harder to predict with manual rules alone, increasing demand for multiphysics platforms that can combine thermal, structural and fluid analysis with optimization or machine-learning acceleration.
The commercial structure of the ai-powered capillary underfill flow simulation and void prediction market is shaped by design qualification, production economics and the interaction between component performance and downstream system requirements. Suppliers that can combine consistent manufacturing, application engineering and supply assurance are better positioned to convert technical eligibility into repeat business. Customer decisions increasingly account for lifecycle continuity, geographic resilience and integration cost, which makes proven process control and ecosystem compatibility as important as nominal product capability.
Segment Analysis: By Type
By type, the AI-Powered Capillary Underfill Flow Simulation and Void Prediction market is segmented into Physics-Based Simulation, Data-Driven AI Models. Physics-based solvers remain essential for model credibility and extrapolation, while data-driven models improve speed when engineers must evaluate many geometry and material combinations. Hybrid workflows reduce the risk of purely statistical predictions by retaining a physical constraint framework. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Type | Role in the market | Demand characteristics |
|---|---|---|
| Physics-Based Simulation | Physics-Based Simulation addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
| Data-Driven AI Models | Data-Driven AI Models addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
Segment Analysis: By End User
By end user, the AI-Powered Capillary Underfill Flow Simulation and Void Prediction market is segmented into Semiconductor Fabricators, IC Design Houses, Packaging Service Providers. Fabricators and OSATs gain direct yield value from predictive process windows, while IC design houses use simulation earlier to evaluate package architectures. The value proposition differs between design-stage risk reduction and factory-stage process control. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| End User | Role in the market | Demand characteristics |
|---|---|---|
| Semiconductor Fabricators | Semiconductor Fabricators represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| IC Design Houses | IC Design Houses represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Packaging Service Providers | Packaging Service Providers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Application
By application, the AI-Powered Capillary Underfill Flow Simulation and Void Prediction market is segmented into Underfill Flow Prediction, Void Detection & Mitigation, Design Optimization, Process Control. Underfill flow prediction and void detection provide the clearest return because they reduce failed prototypes and help engineers identify process windows before expensive package builds. Design optimization and process-control applications become more valuable as simulation connects to manufacturing data and digital-twin workflows. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Application | Role in the market | Demand characteristics |
|---|---|---|
| Underfill Flow Prediction | Underfill Flow Prediction creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Void Detection & Mitigation | Void Detection & Mitigation creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Design Optimization | Design Optimization creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Process Control | Process Control creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
Segment Analysis: By Technology
By technology, the AI-Powered Capillary Underfill Flow Simulation and Void Prediction market is segmented into Hybrid CFD-AI Platforms, Pure Machine-Learning Models, Cloud-Based Simulation Services. Hybrid CFD-AI platforms can accelerate optimization while preserving physical consistency. Pure machine-learning models are attractive for high-speed inference but depend heavily on representative training data, while cloud services broaden access to compute-intensive simulation. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Technology | Role in the market | Demand characteristics |
|---|---|---|
| Hybrid CFD-AI Platforms | Hybrid CFD-AI Platforms represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Pure Machine-Learning Models | Pure Machine-Learning Models represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Cloud-Based Simulation Services | Cloud-Based Simulation Services represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Integration Level
By integration level, the AI-Powered Capillary Underfill Flow Simulation and Void Prediction market is segmented into 2.5D/3D Stacked Packages, System-in-Package (SiP), Chip-on-Board (CoB). 2.5D and 3D stacked packages create the most demanding underfill conditions because tight interconnect pitch, larger die counts and heterogeneous materials increase flow-path complexity and reliability risk. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Integration Level | Role in the market | Demand characteristics |
|---|---|---|
| 2.5D/3D Stacked Packages | 2.5D/3D Stacked Packages represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| System-in-Package (SiP) | System-in-Package (SiP) represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Chip-on-Board (CoB) | Chip-on-Board (CoB) represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Regional Analysis
North America leads the ai-powered capillary underfill flow simulation and void prediction market in 2025, while regional growth patterns differ according to manufacturing concentration, customer investment cycles, regulation, product mix and supply-chain access. The most important regional distinction is not simply market size; it is the mechanism that converts local investment and end-market demand into qualified purchases.
How does regional demand differ across the ai-powered capillary underfill flow simulation and void prediction market?
Regional demand for ai-powered capillary underfill flow simulation and void prediction is structurally uneven because manufacturing assets, design centers, downstream customers and qualification ecosystems are not distributed evenly. Asia Pacific typically has the deepest electronics manufacturing base, North America combines technology development with capital investment, Europe emphasizes reliability and industrial requirements, and emerging regions are more dependent on imported systems. These differences influence vendor selection, inventory policy, service expectations and the pace at which new technologies are adopted.
| Region | Market position | Growth outlook | Demand profile | Supplier-selection gate |
|---|---|---|---|---|
| North America | Most mature | Strong | EDA and advanced-packaging R&D led | Model validation and workflow integration |
| Europe | Precision-engineering market | Moderate-strong | Automotive, industrial and research led | Validation rigor and interoperability |
| Asia Pacific | Fastest scaling | Very strong | Manufacturing and OSAT led | Factory data integration and compute scale |
| South America | Early stage | Selective | Research and high-reliability niches | Software cost and specialist skills |
| Middle East & Africa | Nascent | Selective | Research and technology-transfer led | Skills and semiconductor ecosystem depth |
Detailed Regional Blocks
Competitive Landscape
Competition in the ai-powered capillary underfill flow simulation and void prediction market is determined by technical qualification, manufacturing consistency, customer relationships and the ability to support product lifecycles. Price matters, but it rarely overrides reliability, integration effort or switching cost once a supplier has been designed into a production platform.
The competitive field includes ANSYS, Synopsys, Siemens EDA, Cadence Design Systems, COMSOL Multiphysics, Altair Engineering, alongside other specialized suppliers. Market share can shift when a vendor gains access to a new platform, expands qualified capacity or introduces a technology that materially improves system performance. Because customer validation can be lengthy, incumbent suppliers often benefit from continuity, while challengers need a clear technical or supply-chain advantage to displace an approved source.
Competitive strategy is increasingly multi-dimensional. Leading suppliers invest in process or product development, application engineering and regional support at the same time, while customers seek second-source options where technically feasible. This creates a market in which differentiation is sustained through documented performance, manufacturing yield, quality systems, responsiveness and the ability to support future roadmap transitions without forcing unnecessary redesigns.
| Company | Competitive position | Primary basis of competition |
|---|---|---|
| ANSYS | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Synopsys | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Siemens EDA | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Cadence Design Systems | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| COMSOL Multiphysics | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Altair Engineering | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Dassault Systèmes SIMULIA | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Zuken | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Silvaco | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| MathWorks | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| TSMC internal simulation teams | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Intel internal simulation teams | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
Production Capacity Analysis
For this software market, capacity is defined by engineering compute, solver scalability, model libraries and specialist talent rather than physical factories. Vendors must support high-resolution 3D geometries, repeated parameter sweeps and enterprise-scale data management while maintaining numerical stability. Customers also need enough CPU or GPU resources to run large package models within practical development schedules.
The most important supply-side bottleneck is validated domain knowledge. Reliable underfill prediction requires material characterization, package geometry, dispense conditions and failure data. Vendors with strong semiconductor partnerships can build better-calibrated models and reference flows, creating a data and workflow advantage that is difficult for generic software platforms to reproduce.
Capacity should therefore be evaluated on a qualified-output basis rather than as nominal installed capability. A supplier may possess equipment or production lines that appear suitable but still require customer-specific validation, process tuning, test correlation or upstream material qualification. This distinction becomes especially important during demand spikes, when headline capacity can overstate the volume that is immediately available for a particular application, technology generation or reliability class.
Market Dynamics
The ai-powered capillary underfill flow simulation and void prediction market is being shaped by rising performance requirements and technology transitions on the demand side, while qualification complexity, supply concentration and cost discipline constrain the pace of adoption. The balance of these forces favors suppliers that can solve a measurable system problem without increasing integration risk.
Demand expansion is not uniform across all product variants or customer groups. New technology creates attractive design opportunities, but buyers typically require a clear economic or performance case before changing a qualified architecture. At the same time, supply-chain localization, capacity investment and tighter quality requirements are changing procurement behavior. As a result, growth is likely to concentrate around applications where performance upgrades, manufacturing scale and lifecycle value reinforce one another.
Market Drivers
Four forces provide the strongest support for demand in the ai-powered capillary underfill flow simulation and void prediction market: performance-driven technology upgrades, expansion of relevant downstream applications, investment in manufacturing or infrastructure, and the need for more resilient supply. Their importance varies by segment, but each creates a direct reason for customers to qualify or purchase additional solutions.
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Advanced packaging complexity is raising the cost of physical iteration | High | Chiplets, 2.5D and 3D packages have more interfaces and tighter gaps, making underfill behavior harder to tune empirically. Simulation can screen designs before costly package builds. |
| AI accelerators and HBM increase package size and thermal interaction | High | Large, high-power packages create stronger temperature gradients, warpage and reliability concerns, increasing the value of coupled fluid, thermal and mechanical analysis. |
| Machine learning reduces simulation turnaround time | Medium-High | Surrogate models and AI optimization can evaluate many material and geometry combinations faster than repeated full-physics runs, improving engineering productivity when models are properly validated. |
| Digital-thread adoption connects design and manufacturing | Medium-High | Packaging teams increasingly want simulation results linked to package layout, materials databases and factory data, creating demand for integrated workflows rather than isolated CFD tools. |
Advanced packaging complexity is raising the cost of physical iteration
Chiplets, 2.5D and 3D packages have more interfaces and tighter gaps, making underfill behavior harder to tune empirically. Simulation can screen designs before costly package builds. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
AI accelerators and HBM increase package size and thermal interaction
Large, high-power packages create stronger temperature gradients, warpage and reliability concerns, increasing the value of coupled fluid, thermal and mechanical analysis. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Machine learning reduces simulation turnaround time
Surrogate models and AI optimization can evaluate many material and geometry combinations faster than repeated full-physics runs, improving engineering productivity when models are properly validated. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Digital-thread adoption connects design and manufacturing
Packaging teams increasingly want simulation results linked to package layout, materials databases and factory data, creating demand for integrated workflows rather than isolated CFD tools. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Market Restraints
Growth is moderated by qualification burden, cyclical purchasing, technology substitution and supply-chain risk. These restraints do not eliminate demand, but they can extend sales cycles, limit supplier switching and reduce the speed at which technically superior solutions convert into production revenue.
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Training data can be sparse or proprietary | High | High-quality void and flow data are expensive to generate and often customer-specific. Poor training coverage can make machine-learning predictions unreliable outside the original process window. |
| Multiphysics accuracy requires detailed material characterization | High | Viscosity, surface tension, cure behavior and temperature dependence strongly affect capillary flow. Incomplete material data can dominate model error even when the numerical solver is advanced. |
| EDA workflow integration can be complex | Medium | Package geometry, meshing, material databases and manufacturing parameters come from different tools and teams. Data translation and model setup can limit productivity gains. |
| Enterprise software and compute costs can slow adoption | Medium | High-fidelity 3D simulation and AI training may require large compute resources, specialized licenses and expert users, making return on investment harder for smaller packaging teams. |
Training data can be sparse or proprietary
High-quality void and flow data are expensive to generate and often customer-specific. Poor training coverage can make machine-learning predictions unreliable outside the original process window. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Multiphysics accuracy requires detailed material characterization
Viscosity, surface tension, cure behavior and temperature dependence strongly affect capillary flow. Incomplete material data can dominate model error even when the numerical solver is advanced. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
EDA workflow integration can be complex
Package geometry, meshing, material databases and manufacturing parameters come from different tools and teams. Data translation and model setup can limit productivity gains. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Enterprise software and compute costs can slow adoption
High-fidelity 3D simulation and AI training may require large compute resources, specialized licenses and expert users, making return on investment harder for smaller packaging teams. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Market Opportunities
The most attractive opportunities in the ai-powered capillary underfill flow simulation and void prediction market occur where a technology transition creates measurable value and where suppliers can enter before the customer architecture is locked. Early engagement, application-specific engineering and credible supply planning can convert these windows into durable design positions.
Physics-informed surrogate models
Combining CFD results with machine learning can deliver fast predictions while preserving physical constraints, enabling broader design-space exploration without abandoning model credibility. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Closed-loop package process optimization
Linking simulation with inline inspection and factory data can move the technology from design support into active process-window optimization and defect prevention. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Cloud simulation for smaller packaging teams
Secure cloud compute and subscription licensing can broaden access to multiphysics tools among fabless companies and smaller OSAT engineering groups. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Digital twins for advanced packaging
Package-level digital twins can combine underfill flow, thermal, mechanical and reliability models to support lifecycle optimization from design through manufacturing. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Supply Chain Analysis
Material and process data
Rheology, surface tension, cure kinetics, geometry and temperature data define the physical behavior that simulation must reproduce. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Simulation engines and AI models
CFD, multiphysics solvers, surrogate models and optimization algorithms convert input data into flow, void and reliability predictions. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
EDA and package-design integration
Simulation is connected to package layouts, chiplet planning, thermal models and design-management environments to reduce manual data transfer. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Manufacturing feedback and validation
Inspection, yield and process data are used to calibrate models, validate predictions and improve future package designs. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Recent Developments
Recent developments show how technology roadmaps, manufacturing investment and standards are changing the competitive requirements of the ai-powered capillary underfill flow simulation and void prediction market. The entries below are selected for their direct relevance to product capability, capacity, qualification or downstream adoption rather than for general corporate activity.
Cadence and TSMC expanded collaboration on AI-driven design flows and 3DFabric advanced packaging, including automated system-level analysis and optimization for multi-chiplet designs. The work reinforces the shift toward integrated, AI-assisted analysis across package, signal, power and thermal domains. Source
Cadence announced certified design solutions with TSMC for A16, N2P and 3D-IC flows, including enhanced multiphysics convergence analysis. The certification shows how advanced-packaging simulation is increasingly becoming part of foundry-qualified design infrastructure. Source
SEMI forecast semiconductor assembly and packaging equipment sales of USD 6.7 billion in 2026, with further growth through 2028 as heterogeneous packaging and AI devices become more complex. Higher packaging investment increases demand for simulation that can shorten process development and improve reliability. Source
Report Scope & Segmentation
| Report attribute | Coverage |
|---|---|
| Market | AI-Powered Capillary Underfill Flow Simulation and Void Prediction |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 450.0 million |
| 2026 Estimated Size | USD 480.0 million |
| 2034 Forecast Size | USD 850.0 million |
| CAGR (2026–2034) | 6.3% |
| Largest Market in 2025 | North America |
| By Type | Physics-Based Simulation, Data-Driven AI Models |
| By Application | Underfill Flow Prediction, Void Detection & Mitigation, Design Optimization, Process Control |
| By End User | Semiconductor Fabricators, IC Design Houses, Packaging Service Providers |
| By Technology | Hybrid CFD-AI Platforms, Pure Machine-Learning Models, Cloud-Based Simulation Services |
| By Integration Level | 2.5D/3D Stacked Packages, System-in-Package (SiP), Chip-on-Board (CoB) |
| Companies Profiled | ANSYS, Synopsys, Siemens EDA, Cadence Design Systems, COMSOL Multiphysics, Altair Engineering, Dassault Systèmes SIMULIA, Zuken, Silvaco, MathWorks, TSMC internal simulation teams, Intel internal simulation teams |
Frequently Asked Questions
What was the ai-powered capillary underfill flow simulation and void prediction market size in 2025?
The global ai-powered capillary underfill flow simulation and void prediction market was valued at USD 450.0 million in 2025. The 2025 value is the base-year reference used throughout this overview and provides the starting point for comparing the 2026 estimate and the 2034 forecast.
What is the projected ai-powered capillary underfill flow simulation and void prediction market size in 2034?
The global market is projected to reach USD 850.0 million by 2034. The forecast reflects the interaction of downstream adoption, technology transitions, production investment and the qualification requirements that shape commercial conversion across the market.
What is the CAGR of the ai-powered capillary underfill flow simulation and void prediction market from 2026 to 2034?
The ai-powered capillary underfill flow simulation and void prediction market is expected to expand at a 6.3% CAGR during 2026–2034. Growth will not be uniform across every product or region because customer qualification, capital cycles, supply constraints and application-specific performance requirements differ materially.
Which region is the largest ai-powered capillary underfill flow simulation and void prediction market?
North America is the largest regional market in 2025. Its position is supported by the concentration of relevant manufacturing, customers, technology ecosystems and downstream demand, although the precise commercial mechanism differs by country and application.
How is the ai-powered capillary underfill flow simulation and void prediction market segmented by type?
By type, the market is segmented into Physics-Based Simulation, Data-Driven AI Models. These categories address different performance, cost and integration requirements, so supplier selection depends on application fit, qualification history and lifecycle economics rather than a single specification.
What are the main applications for ai-powered capillary underfill flow simulation and void prediction?
By application, the market covers Underfill Flow Prediction, Void Detection & Mitigation, Design Optimization, Process Control. Demand in each application is linked to platform launches, capacity expansion, equipment replacement and the degree to which the technology improves system performance or manufacturing economics.
What are the principal growth drivers for the ai-powered capillary underfill flow simulation and void prediction market?
Key drivers include advanced packaging complexity is raising the cost of physical iteration and ai accelerators and hbm increase package size and thermal interaction. These forces increase demand when customers can translate technical improvements into higher performance, lower cost, greater reliability or access to new applications.
What are the main restraints in the ai-powered capillary underfill flow simulation and void prediction market?
Important restraints include training data can be sparse or proprietary and multiphysics accuracy requires detailed material characterization. The resulting qualification burden, purchasing cyclicality and technology risk can extend sales cycles and limit rapid supplier substitution even when new solutions offer clear technical advantages.
Which companies participate in the ai-powered capillary underfill flow simulation and void prediction market?
Companies profiled in this market include ANSYS, Synopsys, Siemens EDA, Cadence Design Systems, COMSOL Multiphysics, Altair Engineering, Dassault Systèmes SIMULIA, Zuken. Competition centers on qualification, product or process performance, manufacturing consistency, customer support and the ability to maintain supply across the required product lifecycle.
What should buyers evaluate when selecting a ai-powered capillary underfill flow simulation and void prediction supplier?
Buyers should evaluate demonstrated performance, qualification history, manufacturing consistency, lifecycle support, supply resilience and integration cost. A technically strong product can still face adoption barriers if it increases redesign risk, lacks regional support or cannot meet the customer’s production and quality requirements.
Research Sources & Evidence Base
View research sources used for this overview.
- Cadence. Multiphysics system analysis — AI-driven multiphysics, CFD, thermal, SI/PI and package-analysis capabilities.
- Cadence. Multi-die 3D-IC solution — Chiplet, package and multiphysics integration for advanced packaging.
- Cadence. TSMC advanced-node and 3D-IC certification announcement — 2025 certified advanced packaging and multiphysics workflow context.
- SEMI. Global semiconductor equipment forecast 2026–2028 — Advanced packaging and test investment context driven by AI and heterogeneous integration.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...




