
Key Statistics
Key Takeaways
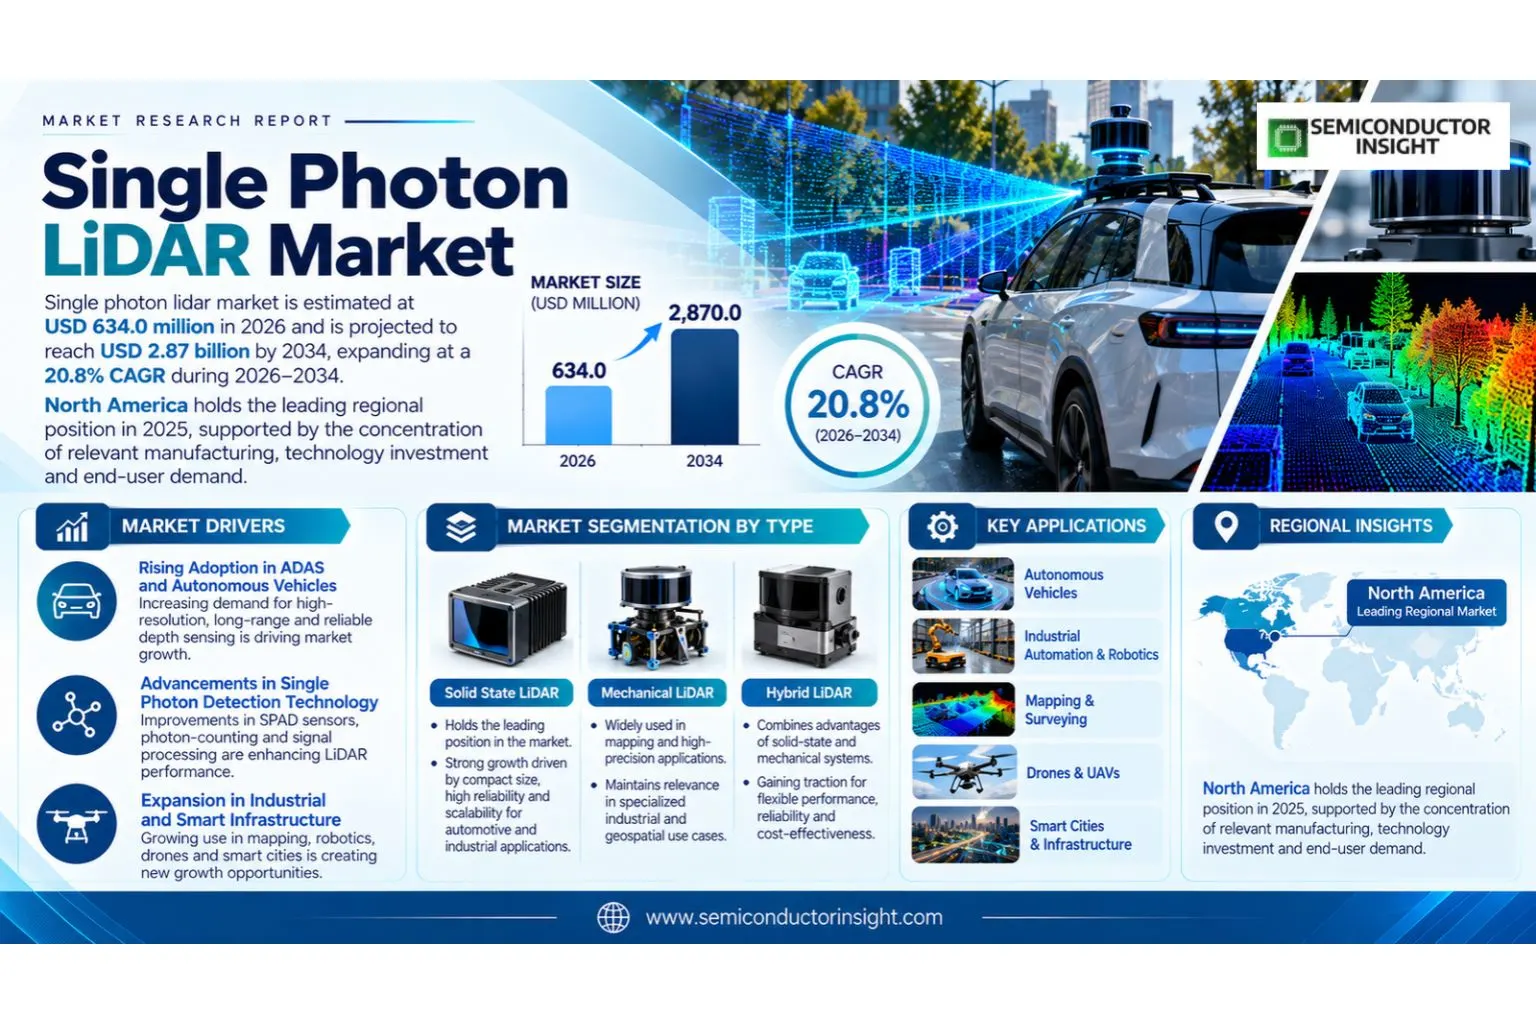
- Single Photon LiDAR market is estimated at USD 634.0 million in 2026 and is projected to reach USD 2.87 billion by 2034, representing a 20.8% CAGR over 2026–2034.
- Solid State LiDAR represents the largest type position, while Solid State LiDAR benefits most from the current shift toward higher-value and more integrated system architectures.
- Autonomous Vehicles is the largest application, while Autonomous Vehicles shows the strongest incremental opportunity as end users expand automation, precision control and data-rich monitoring.
- North America holds the leading regional position in 2025 because its industrial base, customer concentration and technology ecosystem create the strongest commercial pull for suppliers.
- The main growth engine is autonomous driving and adas, whereas system cost remains high remains the most persistent constraint on broader adoption.
- Competitive advantage is shifting toward suppliers that combine core hardware performance with application software, qualification support, integration capability and regional service rather than competing on component specifications alone.
Single Photon LiDAR Market Overview
Single photon lidar market is estimated at USD 634.0 million in 2026 and is projected to reach USD 2.87 billion by 2034, expanding at a 20.8% CAGR during 2026–2034. North America holds the leading regional position in 2025, supported by the concentration of relevant manufacturing, technology investment and end-user demand.
Single photon LiDAR detects extremely weak returned optical signals using photon-sensitive detectors such as single-photon avalanche diodes and time-correlated measurement electronics. The technology enables long-range ranging and dense three-dimensional point clouds with lower returned optical power than conventional linear-detection architectures. Commercial applications include autonomous vehicles, surveying, topographic mapping, infrastructure inspection, security and selected consumer or robotics uses. The market is moving rapidly toward solid-state integration, semiconductor-based detector arrays and lower-cost manufacturing as suppliers seek to translate high sensitivity into automotive- and industrial-scale systems.
The addressable market spans different architectures rather than one uniform product. Mechanical scanning can provide broad field of view and mature performance, while solid-state designs reduce moving parts and support compact integration. Time-of-flight remains widely used because of its established ecosystem, whereas FMCW offers velocity information and potential interference advantages but requires more complex coherent photonics. Range class also matters commercially: automotive and mapping customers pay for detection probability, resolution, eye safety and environmental robustness rather than headline range alone.
The market should be understood as a system-level purchasing decision rather than a standalone component category. Buyers evaluate performance, qualification risk, integration time, service response and lifecycle cost together. This shifts value toward suppliers with proven application engineering and repeatable production capability. The result is a market in which technical differentiation can support pricing, but only when the supplier can translate specifications into measurable yield, uptime, safety, throughput or maintenance benefits for the end user.
Segment Analysis: By Type
By type, the Single Photon LiDAR market is segmented into Solid State LiDAR, Mechanical LiDAR, Hybrid LiDAR. Solid State LiDAR holds the leading position, while the fastest growth is concentrated in configurations that solve higher-value integration, reliability or performance requirements rather than purely price-driven use cases.
| Type | Market position and demand characteristics |
|---|---|
| Solid State LiDAR | Solid State LiDAR serves a distinct set of performance and cost requirements within the market. Its commercial position depends on application fit, technical qualification, integration complexity and the supplier’s ability to maintain repeatable performance across production environments. Largest type reflects the balance between installed-base demand and the rate at which customers are shifting toward more advanced configurations. |
| Mechanical LiDAR | Mechanical LiDAR serves a distinct set of performance and cost requirements within the market. Its commercial position depends on application fit, technical qualification, integration complexity and the supplier’s ability to maintain repeatable performance across production environments. Established segment reflects the balance between installed-base demand and the rate at which customers are shifting toward more advanced configurations. |
| Hybrid LiDAR | Hybrid LiDAR serves a distinct set of performance and cost requirements within the market. Its commercial position depends on application fit, technical qualification, integration complexity and the supplier’s ability to maintain repeatable performance across production environments. Established segment reflects the balance between installed-base demand and the rate at which customers are shifting toward more advanced configurations. |
Type selection is increasingly driven by total system economics
Customers increasingly compare single photon lidar configurations on total installed value rather than purchase price alone. A higher-cost solution can be preferred when it reduces calibration time, improves yield, eliminates auxiliary hardware or provides better diagnostic information. This favors products that simplify integration and support consistent operation at scale. Commodity configurations remain important for cost-sensitive applications, but margin and strategic differentiation are concentrated in products that solve a difficult measurement, automation or reliability problem.
Segment Analysis: By Application
By application, demand spans Autonomous Vehicles, Topographic Mapping, Security Systems, Consumer Electronics. Autonomous Vehicles forms the largest application base, while Autonomous Vehicles is positioned for the strongest incremental growth as customers increase investment in automation, precision and connected operations.
| Application | Demand characteristics |
|---|---|
| Autonomous Vehicles | Largest application. Purchasing is driven by the requirement to improve process control, reliability, safety or throughput in this application. Buyers typically qualify suppliers on performance under real operating conditions, integration with existing equipment and the economic cost of failure. Growth therefore depends on the pace of capital deployment and the degree to which the technology becomes embedded in standard equipment architectures. |
| Topographic Mapping | Relevant demand segment. Purchasing is driven by the requirement to improve process control, reliability, safety or throughput in this application. Buyers typically qualify suppliers on performance under real operating conditions, integration with existing equipment and the economic cost of failure. Growth therefore depends on the pace of capital deployment and the degree to which the technology becomes embedded in standard equipment architectures. |
| Security Systems | Relevant demand segment. Purchasing is driven by the requirement to improve process control, reliability, safety or throughput in this application. Buyers typically qualify suppliers on performance under real operating conditions, integration with existing equipment and the economic cost of failure. Growth therefore depends on the pace of capital deployment and the degree to which the technology becomes embedded in standard equipment architectures. |
| Consumer Electronics | Relevant demand segment. Purchasing is driven by the requirement to improve process control, reliability, safety or throughput in this application. Buyers typically qualify suppliers on performance under real operating conditions, integration with existing equipment and the economic cost of failure. Growth therefore depends on the pace of capital deployment and the degree to which the technology becomes embedded in standard equipment architectures. |
Additional Segment Analysis: By Technology
| Technology | Commercial relevance |
|---|---|
| Time-of-Flight (ToF) | This segment represents a distinct commercial configuration within the single photon lidar market. Adoption depends on performance requirements, cost, compatibility with the host system and the level of qualification demanded by the target industry. Suppliers that can offer multiple configurations across the same platform improve cross-selling opportunities and reduce the customer’s engineering burden when moving between applications. |
| Frequency Modulated Continuous Wave (FMCW) | This segment represents a distinct commercial configuration within the single photon lidar market. Adoption depends on performance requirements, cost, compatibility with the host system and the level of qualification demanded by the target industry. Suppliers that can offer multiple configurations across the same platform improve cross-selling opportunities and reduce the customer’s engineering burden when moving between applications. |
| Direct Detection | This segment represents a distinct commercial configuration within the single photon lidar market. Adoption depends on performance requirements, cost, compatibility with the host system and the level of qualification demanded by the target industry. Suppliers that can offer multiple configurations across the same platform improve cross-selling opportunities and reduce the customer’s engineering burden when moving between applications. |
Additional Segment Analysis: By Detection Range
| Detection Range | Commercial relevance |
|---|---|
| Short Range (<100 m) | This segment represents a distinct commercial configuration within the single photon lidar market. Adoption depends on performance requirements, cost, compatibility with the host system and the level of qualification demanded by the target industry. Suppliers that can offer multiple configurations across the same platform improve cross-selling opportunities and reduce the customer’s engineering burden when moving between applications. |
| Medium Range (100-300 m) | This segment represents a distinct commercial configuration within the single photon lidar market. Adoption depends on performance requirements, cost, compatibility with the host system and the level of qualification demanded by the target industry. Suppliers that can offer multiple configurations across the same platform improve cross-selling opportunities and reduce the customer’s engineering burden when moving between applications. |
| Long Range (>300 m) | This segment represents a distinct commercial configuration within the single photon lidar market. Adoption depends on performance requirements, cost, compatibility with the host system and the level of qualification demanded by the target industry. Suppliers that can offer multiple configurations across the same platform improve cross-selling opportunities and reduce the customer’s engineering burden when moving between applications. |
Regional Analysis
North America leads the Single Photon LiDAR market in 2025, while regional growth rates differ according to manufacturing concentration, technology adoption, end-user investment and local supply-chain maturity. The market is not simply a set of geographic revenue pools; each region has a different purchasing logic and supplier-selection process.
How does regional demand differ across the Single Photon LiDAR market?
Regional demand is shaped by where the relevant equipment is built, where end users deploy it, and how quickly local customers adopt advanced technologies. Mature regions tend to place greater weight on qualification, software and service, while high-growth manufacturing regions generate more unit demand and new design-in opportunities. Project-led regions can still be commercially attractive when applications are high value. Suppliers therefore need regional product positioning rather than a single global sales approach.
| Region | Position | Growth outlook | Demand profile | Supplier-selection gate |
|---|---|---|---|---|
| Asia Pacific | Emerging / project-led | High | Manufacturing and technology-led | Local service, qualification and supply reliability |
| North America | Largest | Moderate-high | Innovation and replacement-led | Local service, qualification and supply reliability |
| Europe | High-value established | Moderate-high | Engineering and regulation-led | Local service, qualification and supply reliability |
| South America | Emerging / project-led | Selective | Project-led | Local service, qualification and supply reliability |
| Middle East & Africa | Emerging / project-led | Selective | Project-led | Local service, qualification and supply reliability |
Key Single Photon LiDAR Manufacturers and Competitive Landscape
Competition in the Single Photon LiDAR market is shaped by application expertise, product reliability, integration capability and global support. The market includes established multinational suppliers, specialist technology companies and regional competitors, with customer qualification creating meaningful switching costs in demanding applications.
Leading suppliers compete by building platforms that can be adapted across multiple customer requirements without forcing a complete redesign. This lowers development time for the customer and creates cross-selling opportunities for the vendor. Brand reputation matters most in high-cost or safety-critical applications, where the financial impact of unreliable measurement or control can exceed the purchase price of the hardware by a wide margin.
Specialist companies remain important because many applications require niche performance, custom packaging or proprietary algorithms. These firms can win against larger suppliers when they solve a difficult technical problem faster or provide more responsive engineering support. However, scaling from prototype to volume production requires quality systems, manufacturing repeatability and a service model that can support customers in multiple regions.
Regional competitors often enter through cost-sensitive applications and then move upward as product quality improves. Their strongest advantage is usually local access, shorter lead time and willingness to customize. Global suppliers respond by broadening product families and adding software, diagnostics and support services that make direct price comparison more difficult. The result is a tiered market rather than a single winner-takes-all structure.
| Competitive tier | Representative companies | Typical advantage |
|---|---|---|
| Global technology leaders | Hesai Group, Ouster, Leica Geosystems, Angstrong Tech, Orbbec Inc. | Broad portfolios, strong qualification history, global support and premium applications |
| Established specialists | Opus Technologies, SK Telecom, innoHere, SMiTSense, Opsys Technologies | Focused technical niches, application depth and regional strengths |
| Emerging / niche suppliers | Photonics Electronics, LuminWave, Blickfeld, Terranet AB, Cepton Technologies | Customization, local access and targeted product differentiation |
Companies profiled
The profiled supplier set includes Hesai Group, Ouster, Leica Geosystems, Angstrong Tech, Orbbec Inc., Opus Technologies, SK Telecom, innoHere, SMiTSense, Opsys Technologies, Photonics Electronics, LuminWave, Blickfeld, Terranet AB, Cepton Technologies. The competitive relevance of each company varies by geography, product architecture and target application, so customer shortlists are usually narrower than the complete profiled universe.
Single Photon LiDAR Production Capacity Analysis
Production capacity for Single Photon LiDAR products is concentrated where the enabling components, precision manufacturing skills and end-user industries are already established. Capacity expansion therefore follows both customer proximity and access to specialized process know-how.
The production footprint is constrained by more than factory floor space. Critical inputs can include precision materials, semiconductor or optical components, calibration equipment, clean manufacturing, specialized test systems and engineering labor. Capacity that lacks validated quality systems is not interchangeable with qualified capacity, particularly in semiconductor, automotive, medical or aerospace applications. As a result, suppliers often scale through phased line additions and customer qualification rather than by building large speculative capacity.
Asia Pacific has the strongest manufacturing density for many electronic and precision components, while North America and Europe retain substantial high-value engineering and specialty production. Regional diversification is increasing as customers seek supply resilience, but duplicating advanced production requires process transfer, trained staff and long qualification cycles. The practical supply risk is therefore concentrated in specialized subcomponents and manufacturing know-how rather than in basic assembly alone.
Single Photon LiDAR Market Dynamics: Drivers, Restraints and Opportunities
The market outlook combines structural growth from autonomous driving and adas with persistent constraints from system cost remains high. The strongest suppliers will be those that convert technical performance into lower total cost, better uptime, improved yield or new end-user functionality.
MARKET DRIVERS
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Autonomous driving and ADAS | High | Automotive platforms demand longer-range and higher-confidence object detection to complement cameras and radar. LiDAR supplies direct depth information and can improve perception … |
| National mapping and infrastructure programs | High | Public mapping programs create recurring demand for airborne and terrestrial LiDAR data. The U.S. Geological Survey’s 3DEP program continues to fund large-area lidar acquisition, i… |
| SPAD semiconductor scaling | Medium-High | Single-photon avalanche diodes can increasingly be integrated into semiconductor arrays with timing electronics, supporting higher pixel counts, smaller modules and lower unit cost… |
| Robotics and industrial autonomy | Medium | Warehouse robots, mobile machines, drones and industrial automation require reliable 3D perception in dynamic environments. LiDAR can provide geometric data independent of visible … |
Autonomous driving and ADAS
Automotive platforms demand longer-range and higher-confidence object detection to complement cameras and radar. LiDAR supplies direct depth information and can improve perception redundancy in complex lighting. Single-photon sensitivity is attractive because it can extend detection performance while supporting lower optical return levels. As suppliers reduce detector and processing cost, more advanced LiDAR architectures become viable for production vehicles rather than only prototype fleets.
National mapping and infrastructure programs
Public mapping programs create recurring demand for airborne and terrestrial LiDAR data. The U.S. Geological Survey’s 3DEP program continues to fund large-area lidar acquisition, including tens of thousands of square miles in recent collaboration rounds. While not every project uses single-photon systems, these programs demonstrate sustained institutional demand for higher-density, faster elevation mapping and provide a commercial pathway for photon-counting technologies.
SPAD semiconductor scaling
Single-photon avalanche diodes can increasingly be integrated into semiconductor arrays with timing electronics, supporting higher pixel counts, smaller modules and lower unit cost. Process improvement in CMOS-compatible detectors is a central enabling factor because it shifts value from bulky optical systems toward scalable semiconductor content. This supports solid-state products for vehicles, robotics and compact 3D sensing.
Robotics and industrial autonomy
Warehouse robots, mobile machines, drones and industrial automation require reliable 3D perception in dynamic environments. LiDAR can provide geometric data independent of visible texture, making it useful for navigation, obstacle avoidance and mapping. A broader robotics installed base diversifies demand beyond passenger vehicles and allows suppliers to commercialize smaller-volume products while automotive qualification proceeds.
MARKET RESTRAINTS
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| System cost remains high | High | Photon-sensitive detectors, precision timing electronics, scanning or beam-steering components and high-performance processing raise system cost. Automotive adoption requires a ste… |
| Data processing and power demand | Medium-High | Dense point clouds create substantial computational load, especially at long range and high frame rate. The sensing advantage can be offset if the vehicle or platform must carry ex… |
| Weather and interference performance | Medium | Fog, rain, dust, sunlight and interference from other optical systems can reduce LiDAR performance. Single-photon detectors are highly sensitive, so signal-processing algorithms mu… |
| Regulatory and qualification barriers | Medium | Automotive, aviation, defense and laser products face stringent safety, reliability and electromagnetic-compatibility requirements. Qualification cycles can take years, and design … |
System cost remains high
Photon-sensitive detectors, precision timing electronics, scanning or beam-steering components and high-performance processing raise system cost. Automotive adoption requires a steep cost reduction relative to surveying and defense systems. Suppliers therefore face pressure to integrate more functions into semiconductor devices, reduce optical complexity and scale manufacturing while still meeting reliability and eye-safety requirements.
Data processing and power demand
Dense point clouds create substantial computational load, especially at long range and high frame rate. The sensing advantage can be offset if the vehicle or platform must carry expensive processors and consume significant power to filter noise and classify returns. Efficient on-sensor processing, compression and perception software are therefore important to total system economics.
Weather and interference performance
Fog, rain, dust, sunlight and interference from other optical systems can reduce LiDAR performance. Single-photon detectors are highly sensitive, so signal-processing algorithms must reject background photons and false returns without losing weak targets. Demonstrating stable operation across real-world conditions is essential for automotive and safety-critical deployment.
Regulatory and qualification barriers
Automotive, aviation, defense and laser products face stringent safety, reliability and electromagnetic-compatibility requirements. Qualification cycles can take years, and design changes may require renewed validation. The market therefore rewards suppliers with financial capacity, quality systems and long-term customer support, while smaller startups face high commercialization risk.
MARKET OPPORTUNITIES
Photon-counting airborne mapping
Single-photon and other photon-counting architectures can collect dense elevation data efficiently over large areas. National mapping, forestry, coastal monitoring and disaster-response programs create demand for faster acquisition and higher point density. Suppliers that combine sensor performance with processing software and workflow integration can capture value beyond the hardware sale.
Automotive solid-state integration
Moving from mechanical scanning toward compact solid-state architectures can improve reliability, manufacturability and styling integration. Semiconductor-based beam steering and SPAD arrays can lower bill of materials at scale. The opportunity is largest for suppliers that secure OEM design wins early enough to be integrated into vehicle electrical and perception architectures.
Smart infrastructure and security
Roadside perception, traffic monitoring, perimeter security and critical infrastructure can use LiDAR where accurate 3D geometry improves tracking. Fixed installations relax some size and power constraints found in vehicles, allowing higher-performance systems to commercialize sooner. The resulting deployments can also create recurring software and analytics revenue.
Robotics volume expansion
Humanoid robots, autonomous mobile robots, robotic lawn equipment and drones are growing LiDAR demand outside automotive. Hesai reported more than 1.6 million lidar shipments in 2025 across its broader product portfolio, illustrating how robotics and automotive scale can move the industry toward high-volume manufacturing. Single-photon designs can benefit as component costs fall and compactness improves.
Single Photon LiDAR Supply Chain Analysis
Raw materials & enabling components
Core manufacturing
Integration & distribution
End-use operation
Raw materials & enabling components
Specialized materials, semiconductor devices, optics, mechanics, RF parts or precision substrates depending on architecture. Value capture rises when a supplier controls a difficult-to-replicate capability such as proprietary design, precision calibration, qualification data or software integration. Bottlenecks become commercially important when they lengthen lead times or limit the ability to qualify alternative suppliers, which is why customers increasingly evaluate resilience as part of sourcing decisions.
Core manufacturing
Fabrication, assembly, calibration, software loading and quality control that establish product performance and repeatability. Value capture rises when a supplier controls a difficult-to-replicate capability such as proprietary design, precision calibration, qualification data or software integration. Bottlenecks become commercially important when they lengthen lead times or limit the ability to qualify alternative suppliers, which is why customers increasingly evaluate resilience as part of sourcing decisions.
Integration & distribution
OEM design-in, distributors, system integrators and applications teams that adapt the product to customer equipment. Value capture rises when a supplier controls a difficult-to-replicate capability such as proprietary design, precision calibration, qualification data or software integration. Bottlenecks become commercially important when they lengthen lead times or limit the ability to qualify alternative suppliers, which is why customers increasingly evaluate resilience as part of sourcing decisions.
End-use operation
Factories, vehicles, research laboratories, infrastructure or industrial assets where recurring replacement and service demand is created. Value capture rises when a supplier controls a difficult-to-replicate capability such as proprietary design, precision calibration, qualification data or software integration. Bottlenecks become commercially important when they lengthen lead times or limit the ability to qualify alternative suppliers, which is why customers increasingly evaluate resilience as part of sourcing decisions.
Recent Developments in the Single Photon LiDAR Market
The U.S. Geological Survey selected seven FY26 3DEP collaboration projects expected to add more than 45,000 square miles of public-domain lidar point-cloud and elevation data. Continued federal and state acquisition programs sustain demand for advanced lidar collection and processing, particularly where faster coverage or higher point density can reduce survey cost.
Hesai reported more than 1.6 million lidar shipments in 2025 and planned annual production capacity above 4 million units for 2026 across its broader lidar portfolio. The scale is important for the single-photon segment because high-volume optical, detector and assembly supply chains reduce component cost and create manufacturing infrastructure that advanced architectures can leverage.
USGS selected 17 FY25 3DEP projects across 11 states, expected to add more than 79,000 square miles of public-domain lidar data. Large-area mapping programs create recurring procurement for lidar systems and services and support continued innovation in acquisition speed, point density and processing efficiency.
REPORT SCOPE & SEGMENTATION
| Attribute | Coverage |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 524.9 million |
| 2026 Market Size | USD 634.0 million |
| 2034 Projected Market Size | USD 2.87 billion |
| CAGR (2026–2034) | 20.8% |
| Largest Market in 2025 | North America |
| By Type | Solid State LiDAR, Mechanical LiDAR, Hybrid LiDAR |
| By Application | Autonomous Vehicles, Topographic Mapping, Security Systems, Consumer Electronics |
| By Technology | Time-of-Flight (ToF), Frequency Modulated Continuous Wave (FMCW), Direct Detection |
| By Detection Range | Short Range (<100 m), Medium Range (100-300 m), Long Range (>300 m) |
| Regions | North America; Europe; Asia Pacific; South America; Middle East & Africa |
| Companies Profiled | Hesai Group, Ouster, Leica Geosystems, Angstrong Tech, Orbbec Inc., Opus Technologies, SK Telecom, innoHere, SMiTSense, Opsys Technologies, Photonics Electronics, LuminWave, Blickfeld, Terranet AB, Cepton Technologies |
Frequently Asked Questions
What is the current size of the Single Photon LiDAR market?
The global Single Photon LiDAR market is estimated at USD 634.0 million in 2026 and is projected to reach USD 2.87 billion by 2034, representing a 20.8% CAGR during 2026–2034. The 2025 base-year market size is USD 524.9 million. Growth is supported by higher end-user technology intensity, automation and the need for more reliable or precise system performance.
Which region leads the Single Photon LiDAR market?
North America holds the leading regional position in 2025. Its advantage reflects the concentration of relevant manufacturing, technology investment and end-user activity. Other regions remain commercially important for premium applications, research, regulation-driven adoption or project demand, so suppliers typically use different channel and service strategies by geography.
Which type leads the Single Photon LiDAR market?
Solid State LiDAR holds the strongest current type position. Its leadership is tied to broad application coverage, installed-base demand and a favorable balance between performance and cost. Growth within the type segment increasingly depends on automation, digital integration and the ability to reduce total system cost rather than on standalone hardware specifications.
Which application is the largest for Single Photon LiDAR?
Autonomous Vehicles forms the largest application base, reflecting the technology’s established role in processes where accuracy, control, reliability or sensing quality directly affects output. Autonomous Vehicles offers a strong incremental opportunity as investment shifts toward more automated, data-rich and performance-sensitive operating environments.
What are the main growth drivers?
The main growth drivers are autonomous driving and adas, national mapping and infrastructure programs, spad semiconductor scaling and robotics and industrial autonomy. Together they increase either the number of addressable system installations or the value of technology required per installation, supporting both unit demand and higher-value product configurations.
What are the main restraints on market growth?
Growth is constrained by system cost remains high, data processing and power demand, weather and interference performance and regulatory and qualification barriers. These factors affect adoption economics, qualification timing or competitive substitution. Suppliers mitigate them through integration, automation, software, service and more application-specific product design.
Who are the key companies in the Single Photon LiDAR market?
Key companies profiled include Hesai Group, Ouster, Leica Geosystems, Angstrong Tech, Orbbec Inc., Opus Technologies, SK Telecom, innoHere, together with additional specialist and regional suppliers. Competitive position varies by product architecture, geography and application. Customers usually shortlist suppliers based on qualification history, performance, integration capability and local support rather than company size alone.
Which technology trends are shaping the market?
The most important technology trends are greater automation, digital connectivity, embedded diagnostics, software-assisted analysis and tighter integration with the host system. These changes move the product from a passive hardware component toward a more intelligent subsystem. Suppliers that can verify performance under production conditions are better positioned to defend pricing and secure long-term design wins.
Where are the strongest new opportunities?
New opportunities are concentrated in photon-counting airborne mapping, automotive solid-state integration, smart infrastructure and security and robotics volume expansion. The common theme is that customers are willing to adopt higher-value technology when it enables a new function, reduces maintenance or improves operating economics in a measurable way.
What is the outlook for the Single Photon LiDAR market through 2034?
The market is projected to reach USD 2.87 billion by 2034 from USD 634.0 million in 2026, a 20.8% CAGR. Growth should remain uneven by segment and region, with the best performance coming from applications where the technology becomes embedded in new equipment architectures, automation programs or high-value measurement and control workflows.
Research Sources & Evidence Base
View research sources used for this overview.
- U.S. Geological Survey. FY25 3DEP Data Collaboration Announcement Selected Projects. Supporting evidence for industry activity, technology development, regional demand or competitive context.
- U.S. Geological Survey. FY26 3DEP Data Collaboration Announcement Selected Projects. Supporting evidence for industry activity, technology development, regional demand or competitive context.
- Hesai Group. Investor Relations and 2025 operating metrics. Supporting evidence for industry activity, technology development, regional demand or competitive context.
- Ouster. 2025 Annual Report. Supporting evidence for industry activity, technology development, regional demand or competitive context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...


