Key Statistics
Key Takeaways
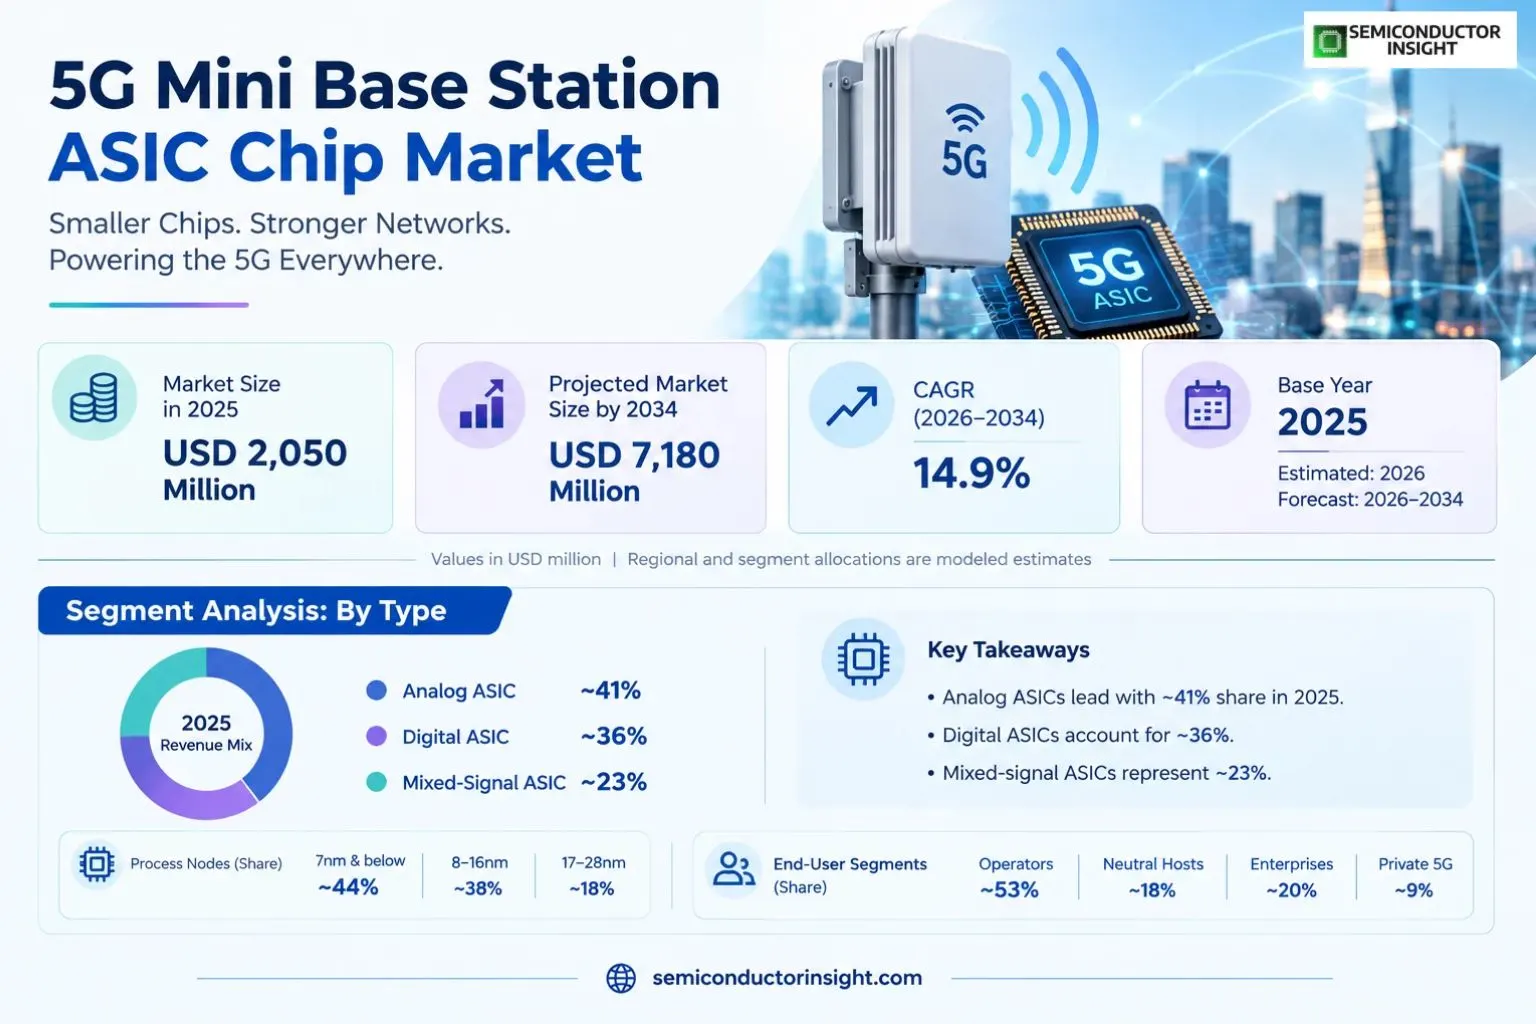
- Market trajectory: The worldwide market starts at USD 2,050 million in 2025 and is projected to reach USD 7,180 million by 2034, representing 14.9% compound annual growth in the 2026–2034 forecasting framework; purchases depend on the silicon content of compact radio equipment rather than the value of installed wireless networks.
- Analog ASICs: An estimated ~41% of base-year type revenue comes from analog-oriented designs that support radio control, clocking and signal conditioning. Digital ASICs at ~36% are more sensitive to changes in baseband processing architecture, and mixed-signal products at ~23% combine interface and control functions within constrained equipment footprints.
- Indoor installations: Small cells deployed inside buildings represent an estimated ~62% of application demand, reflecting office, shopping, transport and enterprise connectivity projects. Outdoor units account for ~38% and face different power, enclosure, environmental and backhaul requirements, which alter the bill of materials and qualification process.
- Process-node mix: The 7nm-and-below category leads the modeled node allocation at ~44%, followed by 8–16nm at ~38% and 17–28nm at ~18%. This split reflects a blended silicon market: advanced digital processors coexist with older-node control and interface circuits, rather than every function moving to the newest fabrication process.
- Regional leadership: Asia-Pacific represents ~58% of the base-year opportunity, with China, Taiwan, South Korea, Japan and India providing different combinations of equipment production, operator spending and enterprise deployments. North America follows at ~20%, while Europe accounts for ~15% under the modeled regional allocation.
- Buyer structure: Telecom operators account for an estimated ~53% of demand, but neutral hosts at ~18%, enterprises at ~20% and private network buyers at ~9% create alternative procurement routes. Vendor qualification is frequently controlled by the system integrator or radio supplier rather than the entity owning the building.
- Competitive boundary: EdgeQ represents a focused integrated base-station silicon architecture; Qualcomm, Intel, NXP and other established semiconductor companies contribute processing, connectivity or supporting functions. Huawei and ZTE are also major equipment integrators, so their complete-radio sales cannot be counted as independent ASIC merchant revenue.
- Commercial constraints: Design-in lead times, software portability, heat dissipation, export controls and procurement cycles limit the speed at which newly developed chips turn into shipments. The strongest growth cases combine a repeatable reference design, an identifiable small-cell equipment customer and a path from field trials to sustained network deployment.
5G Mini Base Station ASIC Chip Market Overview
5G mini base station ASIC chip market was valued at USD 2,050 million in 2025 and is projected to reach USD 7,180 million by 2034, a 14.9% CAGR over the 2026–2034 market horizon. Asia-Pacific leads with an estimated ~58% of base-year revenue, while indoor small-cell applications account for ~62% of application spending; these figures describe ASIC and integrated semiconductor sales, not the full value of radio systems or installation services.
A 5G mini base station uses specialised integrated circuits to perform baseband computation, timing, radio-control, signal-conversion and network-interface functions within an enclosure much smaller than a traditional macro radio cabinet. Some suppliers combine processor cores, accelerators and control logic in a system-on-chip; others supply purpose-built analog and mixed-signal components around the digital processor. Revenue is recognised at the chip or semiconductor-product level, even when the chip is ultimately installed inside a higher-priced radio sold by an equipment manufacturer.
The market definition spans analog ASIC, digital ASIC and mixed-signal ASIC types, indoor and outdoor small-cell applications, three semiconductor process-node bands and four customer groups. It excludes the sale price of a finished radio, the fibre or wireless backhaul service, installation labour, antenna hardware and mobile subscriptions. This distinction prevents network expansion announcements from being mistaken for direct semiconductor purchase orders and avoids treating an equipment manufacturer’s entire radio division as a chip vendor.
Demand for silicon is shaped by architecture as much as by radio count. A highly integrated baseband-on-chip can replace several components and lower the cost of a compact cell, but it may also command a higher price per silicon package than a collection of simple controllers. The same indoor coverage project can be implemented through distributed radio heads, an integrated small cell or a neutral-host shared system, each of which changes the number of independent ASIC sockets available to semiconductor suppliers.
Technology requirements combine physical-layer acceleration, error correction, synchronisation, radio scheduling and secure connectivity. Advanced-node digital logic is valuable where throughput and power efficiency determine product feasibility; established nodes remain appropriate for power control, timing and analog functions that benefit less from transistor scaling. The practical competitive test is whether a silicon platform can support software upgrades, carrier certification and long field-service lifetimes without requiring a complete hardware redesign.
The underlying demand environment is favourable but not uniform. Ericsson counted 3.1 billion 5G subscriptions in the first quarter of 2026, yet subscriber growth does not translate into a proportional rise in mini base stations because much traffic is served by existing macro sites. Enterprise buildings, underground transport areas, industrial campuses and outdoor capacity hotspots generate the strongest small-cell-specific purchasing cases, while projects with insufficient backhaul or weak commercial ownership can remain in trials for years.
Segment Analysis: By Type
By type, the chip market separates analog ASICs, digital ASICs and mixed-signal ASICs according to their dominant design function. Analog ASICs lead the modeled 2025 revenue mix at ~41%, digital products account for ~36%, and mixed-signal devices represent ~23%. A device that integrates several functions is allocated to one primary commercial category rather than counted multiple times across types.
| ASIC type | Technical function | Commercial position |
|---|---|---|
| Analog ASIC | Analog-oriented chips provide low-noise signal paths, clock conditioning, radio calibration, power monitoring and interface control where stable behaviour matters more than extreme transistor density. Their operating environment can include nearby high-power radio stages, challenging board layouts and strict electromagnetic compatibility requirements. The design objective is repeatable performance across temperature and production batches, with integration reducing the number of components surrounding the principal baseband processor. | The modeled leading type at ~41% of 2025 revenue. Analog functions persist even when digital computation moves to newer nodes, so demand is less dependent on a single processor generation. Buyers assess signal integrity, power budgets, test yield and product longevity; suppliers compete on application support and the ability to meet carrier-grade reliability expectations across different equipment enclosures. |
| Digital ASIC | Digital devices perform packet handling, physical-layer acceleration, coding, scheduling and high-speed processing for compact 5G radios. Designs may include programmable processing resources or fixed-function accelerators that lower power per processed bit. The selection between a proprietary ASIC, an adaptable system-on-chip and a more general processor depends on traffic targets, software ecosystem, capital investment and the number of units expected over the platform lifetime. | An estimated ~36% of type revenue is attributed to digital ASICs, whose modeled growth exceeds that of mature analog control functions as bandwidth-intensive applications spread. However, higher integration can reduce discrete chip counts per radio, and chip vendors must demonstrate software continuity across network generations rather than relying only on process-node leadership. |
| Mixed-Signal ASIC | Mixed-signal devices combine conversion, control, clocking and digital processing interfaces within one package, making them useful when the radio board has limited area and thermal headroom. Integration can shorten signal routes and reduce external component counts, but analog isolation and verification become more complex when sensitive circuits share a die with switching logic. Qualification therefore covers both signal performance and embedded control firmware behaviour. | The modeled ~23% base-year share reflects specialised functions rather than a universal replacement for analog and digital chips. Suppliers with proven analog design libraries and packaging expertise can differentiate through integration density, production consistency and application-specific interfaces, especially in indoor units where compactness and installation simplicity are major buying criteria. |
Process nodes and buyer classes
Process-node segmentation is not a simple proxy for device quality. The 7nm-and-below class holds a modeled ~44% of revenue because high-throughput digital engines benefit from denser logic and reduced power per computation; 8–16nm represents ~38% where cost and performance are balanced, while 17–28nm accounts for ~18% in less demanding control and interface roles. Mixed-node designs are normal within a radio, and the node labels refer to the principal commercial silicon product rather than every transistor in the equipment.
End-user demand is distributed among telecom operators, neutral hosts, enterprises and private 5G network operators. The modeled 2025 shares are ~53%, ~18%, ~20% and ~9%, respectively. These categories refer to the buyer context driving ASIC shipments, not four separate invoices for one chip. A venue owner can contract a neutral host, which purchases equipment from a system vendor, which in turn buys silicon; the final device revenue is counted once.
Modeled annual revenue by segmentation axis
The following annual allocation is an internally consistent scenario based on the published market endpoints and modeled 2025 shares, not audited company revenue. Each row belongs to a single segmentation axis, so values within one axis sum to the global total while values across different axes must not be added together. Growth rates are scenario assumptions reflecting the technical and procurement roles of the respective segments; the year-by-year amounts are calculated using the same annual compounding convention throughout the table.
| Modeled axis | Segment | 2025 share | 2025 USD m | 2026 USD m | 2027 USD m | 2028 USD m | 2029 USD m | 2030 USD m | 2031 USD m | 2032 USD m | 2033 USD m | 2034 USD m | 2025–34 CAGR |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Region | Asia-Pacific | ~58% | 1,189.0 | 1,373.6 | 1,586.7 | 1,833.0 | 2,117.6 | 2,446.2 | 2,825.9 | 3,264.5 | 3,771.3 | 4,356.6 | ~15.5% |
| Region | North America | ~20% | 410.0 | 469.9 | 538.7 | 617.4 | 707.7 | 811.2 | 929.8 | 1,065.7 | 1,221.6 | 1,400.2 | ~14.6% |
| Region | Europe | ~15% | 307.5 | 350.3 | 399.1 | 454.6 | 517.9 | 590.0 | 672.2 | 765.7 | 872.4 | 993.8 | ~13.9% |
| Region | South America | ~4% | 82.0 | 92.8 | 104.9 | 118.7 | 134.3 | 151.9 | 171.8 | 194.4 | 219.9 | 248.7 | ~13.1% |
| Region | Middle East & Africa | ~3% | 61.5 | 69.3 | 78.1 | 88.1 | 99.3 | 111.9 | 126.2 | 142.2 | 160.3 | 180.7 | ~12.7% |
| Type | Analog ASIC | ~41% | 840.5 | 960.5 | 1,097.6 | 1,254.2 | 1,433.2 | 1,637.8 | 1,871.6 | 2,138.7 | 2,444.0 | 2,792.8 | ~14.3% |
| Type | Digital ASIC | ~36% | 738.0 | 854.4 | 989.2 | 1,145.2 | 1,325.8 | 1,535.0 | 1,777.1 | 2,057.4 | 2,381.9 | 2,757.6 | ~15.8% |
| Type | Mixed-Signal ASIC | ~23% | 471.5 | 541.2 | 621.1 | 712.9 | 818.2 | 939.1 | 1,077.8 | 1,237.0 | 1,419.8 | 1,629.5 | ~14.8% |
| Application | Indoor Small Cells | ~62% | 1,271.0 | 1,467.0 | 1,693.3 | 1,954.5 | 2,256.0 | 2,603.9 | 3,005.5 | 3,469.1 | 4,004.2 | 4,621.8 | ~15.4% |
| Application | Outdoor Small Cells | ~38% | 779.0 | 889.0 | 1,014.6 | 1,157.9 | 1,321.4 | 1,508.1 | 1,721.1 | 1,964.2 | 2,241.6 | 2,558.2 | ~14.1% |
| Node | 7nm and Below | ~44% | 902.0 | 1,049.0 | 1,219.9 | 1,418.8 | 1,650.0 | 1,918.8 | 2,231.5 | 2,595.2 | 3,018.1 | 3,510.0 | ~16.3% |
| Node | 8-16nm | ~38% | 779.0 | 891.1 | 1,019.4 | 1,166.2 | 1,334.1 | 1,526.2 | 1,745.9 | 1,997.2 | 2,284.8 | 2,613.7 | ~14.4% |
| Node | 17-28nm | ~18% | 369.0 | 414.7 | 466.2 | 523.9 | 588.9 | 661.9 | 743.9 | 836.2 | 939.8 | 1,056.3 | ~12.4% |
| End User | Telecom Operators | ~53% | 1,086.5 | 1,247.2 | 1,431.6 | 1,643.4 | 1,886.4 | 2,165.4 | 2,485.6 | 2,853.3 | 3,275.2 | 3,759.6 | ~14.8% |
| End User | Neutral Hosts | ~18% | 369.0 | 423.2 | 485.4 | 556.7 | 638.4 | 732.2 | 839.8 | 963.1 | 1,104.6 | 1,266.9 | ~14.7% |
| End User | Enterprises | ~20% | 410.0 | 471.9 | 543.1 | 625.0 | 719.3 | 827.9 | 952.8 | 1,096.6 | 1,262.0 | 1,452.4 | ~15.1% |
| End User | Private 5G Networks | ~9% | 184.5 | 214.0 | 248.2 | 287.9 | 333.9 | 387.3 | 449.3 | 521.1 | 604.4 | 701.1 | ~16.0% |
Segment Analysis: By Application
Indoor Small Cells and Outdoor Small Cells form the application axis. Indoor projects lead with an estimated ~62% of 2025 chip revenue because multi-floor buildings, transport facilities and enterprises need local radio capacity that macro sites cannot reliably provide. Outdoor equipment represents ~38% and serves street-level infill, campuses and dense urban coverage, usually with stricter weatherproofing and backhaul constraints.
| Application | Demand characteristics |
|---|---|
| Indoor Small Cells | An indoor unit operates within an office, shopping complex, transit hub, hospital or industrial building and must fit space, energy and cabling restrictions. Radio performance is affected by walls, floor plates and shared use by several operators. Semiconductor designs prioritise integrated baseband capability, low acoustic and thermal impact, manageable power draw and reliable software upgrades over a long facility contract. The modeled ~62% application share reflects numerous small venues as well as large multi-radio installations. |
| Outdoor Small Cells | Outdoor mini base stations fill capacity gaps on streets, campuses and public spaces without the scale of a macro tower. Devices may need wider temperature ratings, environmental protection, interference coordination and remote operation when access for maintenance is difficult. The modeled ~38% share reflects fewer but often more demanding deployment sites. Procurement is sensitive to installation permits, street furniture rights and the cost of backhaul, all of which can delay a semiconductor design win reaching production volumes. |
The two applications differ in who specifies the system. Building owners may select an indoor service provider based on coverage guarantees, while mobile operators and municipalities influence outdoor siting and radio configuration. For chip suppliers, the resulting route to market is normally an equipment-platform qualification followed by repeat orders across many installations. A successful field demonstration is useful evidence of technical readiness but does not establish how many ASICs will ship in a particular calendar year.
Integrated indoor solutions such as Nokia Kolibri and Ericsson Radio Dot illustrate the range of equipment architectures that create semiconductor demand. A compact baseband embedded in the small cell can increase the importance of a highly integrated processor, whereas a distributed radio arrangement may concentrate compute elsewhere and use different chips at each remote radio point. Market allocation follows the semiconductor content actually sold, not the number of visible radio endpoints in a building.
Regional Analysis
Asia-Pacific accounts for a modeled ~58% of 2025 ASIC demand and grows at an estimated ~15.5% annual rate through 2034. North America represents ~20%, Europe ~15%, South America ~4% and the Middle East and Africa ~3%. These allocations describe where chip-enabled mini base station demand is ultimately deployed, not the location of semiconductor foundries or the corporate headquarters of radio equipment vendors.
Where is demand for compact 5G base-station silicon concentrated?
The regional pattern reflects different infrastructure economics. Asia-Pacific combines dense cities, large operator networks and substantial radio equipment engineering activity; North America emphasises enterprise connectivity and neutral-host solutions; Europe faces complex multi-country procurement and building requirements; South America prioritises selective urban upgrades; and Gulf markets use targeted indoor deployments for commercial and public facilities. These differences affect chip mix, project timing and system certification more directly than headline national 5G subscription counts.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~58%) | ~15.5% CAGR | Urban density and manufacturing ecosystem | Interoperability, cost per covered square metre and local equipment support |
| North America | Second (~20%) | ~14.6% CAGR | Enterprise and neutral-host sites | Private-network security, certification and integration partners |
| Europe | Third (~15%) | ~13.9% CAGR | Building coverage and industrial campuses | Energy efficiency, public procurement and national spectrum rules |
| South America | Developing (~4%) | ~13.1% CAGR | Selective city and venue deployments | Financing, affordable radio hardware and backhaul availability |
| Middle East & Africa | Emerging (~3%) | ~12.7% CAGR | Large venues and enterprise networks | Heat tolerance, system vendor service and project continuity |
5G Mini Base Station ASIC Chip Manufacturers and Competitive Landscape
Competition in small-cell silicon crosses the boundary between independent semiconductor suppliers, proprietary radio equipment developers and companies supplying supporting processors or analog functions. The market is not a league table of total corporate sales: a complete 5G radio may contain silicon from several companies, and some equipment manufacturers design critical chips internally. Winning a qualified equipment platform and maintaining its software ecosystem are the most important routes to recurring revenue.
EdgeQ promotes a base-station-on-chip approach combining 4G and 5G baseband functions with programmable processing and hardware acceleration. This architecture can reduce the number of separate processors required in a compact cell, although it also changes the revenue distribution between merchant ASICs and surrounding support chips. The product illustrates a focused competitive strategy: deliver a sufficiently complete and software-upgradable silicon platform that equipment manufacturers can reuse across multiple small-cell designs and service-provider requirements.
Qualcomm, Intel and NXP participate in the wider connectivity and processing ecosystem through products and intellectual property relevant to communications equipment. Their commercial roles should be assessed by the exact device, platform and customer rather than inferred from company size. A general-purpose processor used in a network appliance does not automatically qualify as a mini base-station ASIC, and an integrated system-on-chip should be counted once even when it performs digital, analog-control and acceleration functions.
Huawei and ZTE are important radio equipment developers with substantial engineering capabilities, but the revenue from their completed small-cell products includes antennas, power supplies, mechanical components, software and service elements. Counting that equipment revenue as merchant ASIC sales would materially overstate the semiconductor opportunity. Ericsson and Nokia likewise influence the market through platform architectures, qualification and operator relationships, while their publicly described indoor solutions provide evidence of end-use demand rather than a breakdown of individual chip sales.
The competitive cycle begins with technical sampling and software enablement, moves through lab validation and radio interoperability, and then requires a system vendor to secure operator or enterprise orders. This sequence can take longer than a conventional electronics component qualification because the silicon affects radio timing, security and network performance. Supplier differentiation rests on power efficiency, accelerator programmability, long-term availability, reference software, documentation and the cost of supporting multiple regional radio configurations.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Focused integrated silicon | EdgeQ and specialised baseband ASIC developers | A platform-led strategy integrates 5G processing, acceleration and network functions to reduce radio board complexity. Success depends on software portability, validation tools and the ability to scale from a reference design to repeated equipment orders without substantial redesign for every deployment. |
| Broad semiconductor ecosystem | Qualcomm, Intel, NXP and other connectivity silicon suppliers | Established companies offer processing, mixed-signal or control capabilities relevant to telecom hardware, but their total corporate revenue is not equivalent to small-cell ASIC sales. The precise product socket and merchant-versus-captive revenue boundary must be established before assigning competitive share. |
| Equipment and network integrators | Huawei, ZTE, Ericsson, Nokia and system-integration partners | These firms influence chip requirements and qualification through complete radio platforms and operator relationships. Some functions may be internally designed while others are bought from merchant vendors, so their importance reflects purchasing influence and ecosystem control rather than a directly comparable chip-revenue ranking. |
Key companies profiled
- EdgeQ
- Qualcomm
- Intel
- NXP Semiconductors
- Huawei Technologies
- ZTE Corporation
- Ericsson
- Nokia
- Broadcom
- MediaTek
- Samsung Electronics
5G Mini Base Station ASIC Chip Production and Technology Capacity
Semiconductor production capacity for mini base-station ASICs is shared with a much larger universe of communications processors, control devices and advanced digital chips. Design companies may outsource fabrication and packaging, while integrated equipment vendors can use proprietary silicon. The critical bottleneck is often not raw wafer supply alone but the ability to validate a specific processor architecture, firmware stack and radio implementation across several product generations.
Leading-edge digital ASICs can use the 7nm-and-below process class when energy per computation and processing throughput justify the design and mask costs. This class holds an estimated ~44% of the modeled base-year node revenue. The choice is not universal: 8–16nm designs offer a different balance of power, cost and availability, while 17–28nm circuits can remain competitive for timing, interface and control functions that do not require the densest digital logic.
Chip supply planning must account for the length of a telecom equipment lifecycle. A radio platform may remain in service long after the foundry has shifted investment toward newer nodes, creating demand for long-term process support, test programs and qualified replacement devices. Packaging and thermal validation matter because a small cell may be installed in a ceiling void or weatherproof enclosure where airflow is restricted and field repair is expensive.
Capacity risk also comes from engineering resources. A silicon design can be fabricated successfully yet remain commercially constrained by incomplete driver software, interoperability issues or certification delays. Vendors with reusable reference designs, test automation and a documented path to operator acceptance can convert fabrication capacity into sellable products more reliably than firms offering an isolated chip without an equipment-level integration plan.
The manufacturing ecosystem spans wafer fabrication, assembly, electrical test, firmware provisioning and final radio-system integration. A change in the foundry node may alter timing behaviour and power characteristics even when the functional specification is unchanged, forcing additional equipment qualification. Supply diversification is therefore a longer process than ordering the same component from another distributor, particularly for custom ASICs tied to proprietary radio software.
5G Mini Base Station ASIC Chip Market Dynamics: Drivers, Restraints and Opportunities
Growth in this semiconductor category is driven by enterprise indoor coverage, denser 5G capacity requirements, integrated radio designs and private wireless adoption. Offsetting forces include costly system qualification, dependence on equipment-vendor procurement, uneven project financing and silicon supply constraints. The contribution model below separates the main demand accelerators from project-level obstacles and reconciles their effects to the annual growth rate without treating every 5G subscription as a chip order.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Enterprise indoor 5G coverage | High | +6.30% | High | High | Medium |
| Network capacity and 5G-Advanced upgrades | High | +4.80% | Medium | High | High |
| Highly integrated low-power silicon | Medium-High | +3.10% | High | High | Medium |
| Private network and neutral-host expansion | Medium | +2.70% | Medium | High | High |
| Repeatable equipment reference platforms | Low-Medium | +1.90% | Medium | Medium | High |
| Others (industrial and transport connectivity) | Low | +1.10% | Low | Medium | Medium |
Indoor connectivity as a dedicated infrastructure category
Office complexes, transport stations, malls and hospitals cannot always obtain consistent 5G service from outdoor macro sites. Dedicated indoor radio systems address building attenuation and high local user density, creating equipment purchases with distinct semiconductor content. The opportunity is strongest when a building operator or neutral host can replicate one proven installation model across many properties, reducing design effort and increasing the repeat orders available to the selected ASIC platform.
Capacity-led upgrades beyond first-time 5G coverage
Once broad network coverage is established, traffic concentration and service differentiation become more important than adding coverage points alone. A busy venue may require local processing, efficient radio scheduling and better uplink performance, encouraging upgraded baseband silicon. The resulting demand is selective: equipment suppliers must demonstrate that a compact radio offers measurable performance or energy benefits against existing macro and distributed antenna alternatives before operators commit to replacement programs.
Integration lowers the physical cost of deployment
Combining processing, acceleration and control functions in fewer semiconductor packages can reduce board area, cooling needs and installation complexity. These savings are particularly valuable in indoor locations with limited ceiling space or power infrastructure. A chip supplier can therefore win business through total system cost rather than the lowest unit price, provided its software environment supports the operator features and security maintenance expected over the equipment lifetime.
Private wireless extends the customer base
Utilities, ports, logistics operators and industrial campuses can deploy local 5G networks for operational communication without relying exclusively on a public mobile operator. These projects create alternative purchasing channels through system integrators and managed service providers. A silicon platform capable of supporting secure local cores, predictable traffic handling and straightforward configuration can participate in several industrial verticals, although projects must still justify the cost of equipment and ongoing support.
Platform reuse improves chip economics
ASIC development involves substantial upfront engineering, verification and software work, which becomes more economical when one design supports several radio models. Equipment manufacturers seek configurable platforms that can be used for indoor and outdoor variants with limited changes. This favours chip suppliers offering stable interfaces and a clear migration path for new network releases, because customer lifetime value is determined by repeated shipments rather than the initial sample purchase.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Long carrier qualification and design cycles | High | -2.10% | High | Medium | Medium |
| Uneven operator capital budgets | Medium-High | -1.40% | High | High | Medium |
| Backhaul, siting and facility access barriers | Medium | -0.90% | Medium | Medium | Low |
| Others (software portability and supply exposure) | Low | -0.60% | Medium | Low | Low |
Carrier qualification delays commercial conversion
A compact radio cannot enter a large operator network merely because its processor meets a laboratory throughput target. Interoperability, timing accuracy, security, software maintenance and network management must all be validated in the equipment platform. A defect discovered late in this process can force redesign or firmware changes, delaying production shipments and reducing the commercial value of early semiconductor design wins.
Project budgets remain uneven across geographies
Indoor coverage is often funded by building owners, operators or neutral hosts with different expectations about return on investment. Where no party is willing to pay for installation and ongoing management, a technically sound small-cell design may remain unpurchased. This creates irregular demand for ASIC vendors even while national 5G subscription totals rise, making revenue recognition sensitive to project timing and procurement concentration.
Backhaul and site access create non-chip bottlenecks
A mini base station needs reliable transport connectivity, suitable power and permission to install equipment in a building or on street furniture. These requirements can account for a large share of the deployment cost, so a lower-cost processor alone may not make a project viable. Delays in cabling, building approvals or spectrum arrangements can hold back radio orders independently of semiconductor availability.
Software and sourcing concentration complicate support
Proprietary baseband interfaces, firmware dependencies and specialised fabrication processes can lock an equipment vendor into a narrow supplier set. Changing the chip may require expensive validation of radio software and security functions, while regional sourcing policies add another qualification layer. Buyers consequently value lifecycle commitments and second-source planning, which can limit the speed of adoption for otherwise attractive new silicon architectures.
MARKET OPPORTUNITIES
Programmable baseband for differentiated services
Equipment platforms that expose processing and acceleration functions through stable software interfaces can adapt to private network requirements, enterprise traffic policies and future 5G-Advanced features. This provides a route for focused silicon vendors to compete without replicating the full product range of large semiconductor groups. The opportunity is strongest when a radio manufacturer can demonstrate a clear feature upgrade path while preserving the same hardware design.
Shared indoor systems and neutral-host channels
Shared-building installations reduce duplicate equipment and can improve the economics of providing several operators with consistent coverage. Although sharing may reduce the number of independent radios, it can favour higher-functionality processors and integrated management capabilities in the chosen platform. ASIC suppliers should therefore target equipment vendors serving repeatable neutral-host projects, not simply count the number of operators whose customers use a particular venue.
Industrial reliability and local processing
Factories and utilities may need private 5G equipment with secure local traffic handling, long-term component availability and resilience under challenging environmental conditions. These requirements create space for differentiated chip architectures that balance digital acceleration with robust control functions. Successful suppliers will document field-service characteristics and integration support, because industrial buyers assess operational continuity more heavily than the newest semiconductor node designation.
5G Mini Base Station ASIC Chip Supply Chain Analysis
The supply chain begins with ASIC architecture, intellectual property and electronic design tools, proceeds through wafer fabrication and packaging, and ends with radio-equipment qualification and deployment. A chip can pass wafer test yet generate no meaningful market revenue until a system vendor has incorporated it into a certified mini base station. Procurement power therefore sits with equipment designers and operators, while fabrication and software ecosystems determine how readily suppliers can scale production.
Upstream design. Chip suppliers rely on processor IP, physical-layer acceleration blocks, analog design libraries and reliable software toolchains. The most expensive design effort often concerns integration and verification rather than the bare cost of silicon. A product that can be configured for several radio bands and software releases may reduce the equipment manufacturer’s engineering burden, but only if the vendor maintains a consistent interface and documents the performance trade-offs.
Fabrication. A mini base-station platform may combine an advanced digital processor with mature-node analog and power-management devices. Different fabrication processes have distinct cost, yield and lifecycle characteristics, so a system vendor must manage multiple semiconductor suppliers even when the main baseband is highly integrated. Packaging and temperature testing are essential because compact equipment has limited cooling capacity and may be installed where maintenance access is difficult.
System integration. The equipment manufacturer connects silicon to RF stages, timing sources, network interfaces, power delivery and management software before seeking carrier or enterprise acceptance. This step determines whether a nominally capable ASIC meets practical throughput, latency and reliability targets. Vendors providing reference designs, firmware support and test results can shorten integration time, which improves their chance of turning an engineering evaluation into repeatable commercial orders.
Downstream purchasing. Mobile operators usually buy certified equipment rather than individual chips, while neutral hosts and enterprise integrators purchase managed connectivity solutions. Semiconductor revenue is embedded in those equipment orders and should not be confused with the full project budget. For market analysis, the relevant drivers are radio platform adoption, chip content per unit and shipment timing; spectrum fees, construction work and network subscriptions remain outside the counted market.
Recent Developments in the 5G Mini Base Station ASIC Chip Ecosystem
- 22 October 2025 Industry recognition
Ericsson discussed its positioning in enterprise indoor cellular systems and the role of shared radio infrastructure in serving large buildings. The development matters for silicon suppliers because a shift toward integrated indoor products changes the balance between processing inside the radio endpoint and functions centralised elsewhere in the network. Recognition of an equipment portfolio is not a measure of merchant ASIC shipments, but it signals sustained commercial attention to the application. Source - 10 November 2025 Deployment
An Ericsson indoor 5G solution was announced for the 10 World Trade office tower in Boston, using a building-oriented deployment model. The case illustrates how a property owner can obtain indoor coverage without purchasing semiconductor devices directly. Equipment qualification and neutral-host integration determine which processors are embedded in the final installation, while the announcement itself does not disclose chip volumes, unit prices or supplier market shares. Source - 15 October 2025 Statistics
The International Telecommunication Union published 2025 connectivity statistics indicating that 5G/IMT-2020 accounted for 36% of mobile broadband subscriptions. This establishes a broader adoption backdrop for capacity investment, but it should not be used as a direct multiplier for mini base-station ASIC demand. Subscriber coverage can expand on existing macro equipment, whereas dedicated indoor and outdoor small cells require separate project economics and site decisions. Source - 3 September 2025 Industry study
Nokia released research on enterprise private wireless returns and edge-enabled applications, highlighting the commercial motivation for industrial connectivity beyond ordinary public mobile access. For ASIC suppliers, the significance is the potential to reuse secure and configurable radio platforms across manufacturing, logistics and infrastructure customers. The survey is evidence of enterprise interest and does not establish a global revenue figure for specialised small-cell semiconductor products. Source - 14 July 2025 Contract
Nokia announced a private 5G network selection for Memphis Light, Gas and Water, covering communications needed for grid modernisation and operational resilience. The project spans radio, core, cybersecurity and transport functions, demonstrating how broad the system value chain can be. Only the qualifying chip content of mini base-station equipment belongs in the market defined here; the full value of the utility network must not be attributed to ASIC vendors. Source - 25 June 2025 Deployment
Nokia said Verizon Business had selected its hardware and software for a multisite private 5G initiative at Thames Freeport in the United Kingdom. The project is relevant because geographically distributed industrial installations favour equipment platforms with common management and repeatable configuration. Such standardisation can support recurring processor orders, although the public announcement does not identify the ASIC supplier or provide an equipment-level bill of materials. Source - 8 May 2025 Field test
Ericsson and Taiwanese operators reported a multi-operator 5G Radio Dot field trial at Taipei City Mall, with peak downlink throughput above 1Gbps and energy consumption up to 45% below a conventional active distributed antenna arrangement. The result shows how indoor systems are evaluated against performance and power targets. The relevant semiconductor implication is pressure for efficient processing and integration, not proof of a particular chip vendor’s sales. Source - 2 June 2025 Partnership
Nokia and Andorix announced cooperation on private 5G and edge solutions for commercial real estate in North America. The partnership connects wireless equipment demand with building technology decisions and introduces another channel for compact-cell system vendors. A repeatable building deployment package may improve the economics of an ASIC platform, but the announcement concerns solutions and partnerships rather than separately disclosed chip revenue. Source - 15 January 2025 Indoor network
Nokia announced work with Zain KSA on enterprise indoor solutions, including compact cellular equipment suited to business facilities. The announcement demonstrates that the small-cell market includes operator-led projects outside the largest East Asian and North American markets. Semiconductor demand will depend on the hardware architecture selected, its field qualification and the number of commercially installed units, none of which is disclosed as a separate ASIC sales figure. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2024 |
| Market Size 2025 | USD 2,050 million |
| Market Size 2026 | USD 2,356 million |
| Market Size 2034 | USD 7,180 million |
| Growth Rate | CAGR of 14.9% for 2026–2034 |
| Units | Revenue in USD million; modeled segment shares and growth rates |
| Coverage | ASIC and integrated semiconductor products designed for 5G mini and small base stations |
| By Type | Analog ASIC · Digital ASIC · Mixed-Signal ASIC |
| By Application | Indoor Small Cells · Outdoor Small Cells |
| By Node | 7nm and Below · 8–16nm · 17–28nm |
| By End User | Telecom Operators · Neutral Hosts · Enterprises · Private 5G Networks |
| By Region | Five geographic markets, with country-level equipment demand assessed separately from semiconductor fabrication location North AmericaUnited States, Canada, Mexico EuropeUnited Kingdom, Germany, France, Benelux, Italy, Nordics and Rest of Europe Asia-PacificChina, Japan, South Korea, Taiwan, India, Southeast Asia and Rest of Asia-Pacific South AmericaBrazil, Argentina, Chile, Colombia and Rest of South America Middle East & AfricaSaudi Arabia, UAE, South Africa and Rest of Middle East & Africa |
| Key Companies Profiled | EdgeQ; Qualcomm; Intel; NXP Semiconductors; Huawei Technologies; ZTE Corporation; Ericsson; Nokia; Broadcom; MediaTek; Samsung Electronics |
| Customization Scope | Optional custom analysis of chip functions, process nodes, procurement channels, operator qualification and specific country-level applications can be scoped separately to match buyer needs. |
Frequently Asked Questions
What is the size and forecast of the 5G mini base station ASIC chip market?
The market stood at USD 2,050 million in 2025 and is forecast to reach USD 7,180 million in 2034, representing a 14.9% CAGR over the required forecast framework. The values cover integrated circuits and related semiconductor products used in compact 5G base-station equipment, rather than complete radio installations, spectrum rights, network services or the spending of telecom operators on their entire infrastructure.
What functions are performed by a mini base station ASIC?
A compact 5G radio needs specialised silicon for baseband processing, physical-layer acceleration, clocking, network interfaces, signal conditioning and control. Some platforms combine several of these functions in one package, while other designs retain separate digital and analog components. A successful ASIC must satisfy power, timing, security and software requirements within the limited space of indoor or outdoor equipment, often for a long service life.
Which type of ASIC leads the market?
Analog ASICs account for the leading modeled type allocation at ~41% of 2025 revenue, reflecting control and interface functions present in many radio designs. Digital ASICs represent ~36% and mixed-signal ASICs ~23%. The distinction is based on the primary commercial function of a device; integrated products are not counted multiple times merely because they include several kinds of circuitry on the same die.
Why are indoor small cells commercially important?
Indoor installations account for a modeled ~62% of application revenue because buildings can attenuate signals from outdoor macro networks and create dense local traffic. Offices, stations, malls and industrial facilities may require dedicated radio coverage with compact power and cooling arrangements. The ASIC opportunity depends on which equipment architecture is selected and whether the installation is funded by an operator, neutral host or property owner.
How is the semiconductor process-node market segmented?
Three node bands are tracked: 7nm and below, 8–16nm and 17–28nm. The leading band has a modeled ~44% share, while the others account for ~38% and ~18%. Advanced logic is attractive for throughput-intensive baseband processing, but established processes can be preferable for analog control, timing and interfaces. A small-cell system commonly uses more than one node across its different semiconductor packages.
Which geographic market is largest?
Asia-Pacific leads with an estimated ~58% of base-year revenue, supported by dense urban wireless infrastructure and extensive radio equipment engineering activity. North America and Europe follow with different enterprise, neutral-host and industrial procurement patterns. Regional allocations describe the final equipment-demand market; they do not imply that all relevant chips are fabricated in the same region where a radio is eventually installed.
Who purchases mini base station ASIC products?
The immediate chip customer is generally a radio equipment manufacturer or electronics integrator, while the end-use demand comes from telecom operators, neutral hosts, enterprises and private network owners. The modeled allocation gives operators ~53% of demand. A building owner may purchase a managed indoor connectivity service without ever negotiating with a semiconductor supplier, so the sales channel is more complex than a direct chip-to-operator transaction.
Which companies influence competitive dynamics?
Focused integrated baseband suppliers such as EdgeQ compete through programmable architectures and system-level design support. Qualcomm, Intel, NXP and other semiconductor companies participate through relevant processing or connectivity functions, while Huawei, ZTE, Ericsson and Nokia shape platform requirements as equipment developers. Their roles are not directly interchangeable, and complete radio-equipment revenue should not be treated as merchant ASIC market share.
What are the main barriers to faster growth?
Radio platform qualification is lengthy because processors affect timing, interoperability, network security and field reliability. Projects also require suitable backhaul, building access, power and a party willing to fund installation. Silicon supply exposure and software dependence can further complicate adoption. These obstacles explain why a rapid increase in 5G subscriptions or an impressive field test does not automatically produce proportional annual growth in chip shipments.
What segmentation and forecast period are covered?
The study uses 2025 as its base year, 2026 as the estimate year and 2026–2034 as the forecast window. Its classifications distinguish signal-processing functions, indoor and outdoor equipment installations, fabrication-node choices and the procurement channels that ultimately determine chip shipments. Five world regions are assessed, with modeled market shares distinguished from directly reported company, operator or network-deployment statistics.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF