SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Redundant Array of Independent Disks (RAID) Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
CONSUMER ELECTRONICS Semiconductor Market Research

Redundant Array of Independent Disks (RAID) Market

Size, Share & Industry Analysis, By Type (Hardware RAID, Software RAID), By Application (Internet & Cloud Services, Enterprise IT, Industrial & Manufacturing, Others), By End User (Large Enterprises, Small & Medium Enterprises, Data Center Operators), By RAID Level (RAID 0-1, RAID 5-6, RAID 10 and above), and Regional Forecast, 2026-2034

◷
UPDATED 16 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE afeb0d3d3671
▯
FORMATS PDF

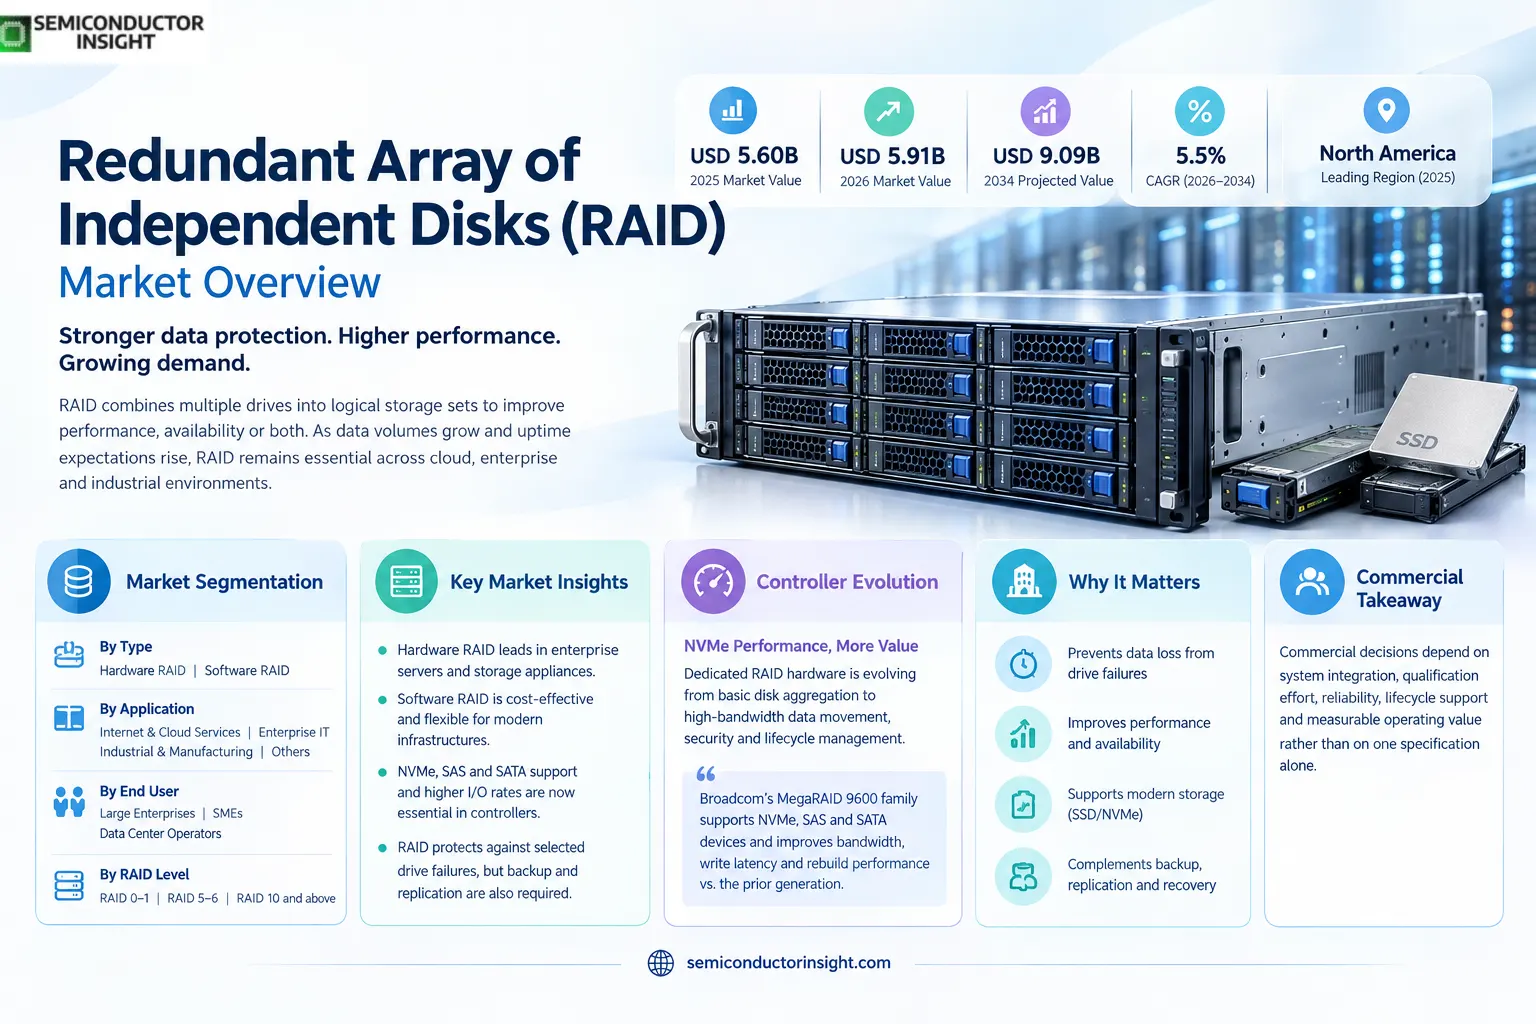
RAID market was valued at USD 5.60 billion in 2025 and is estimated at USD 5.91 billion in 2026. It is projected to reach USD 9.09 billion by 2034, registering a CAGR of 5.5% over 2026–2034. North America held the leading regional position in 2025.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 5.60 billion
2026 Estimated Size
USD 5.91 billion
2034 Projected Size
USD 9.09 billion
CAGR (2026–2034)
5.5%
Largest Market in 2025
North America

Key Takeaways

  • Market trajectory: Redundant Array of Independent Disks (RAID) Market was valued at USD 5.60 billion in 2025 and is projected to reach USD 9.09 billion by 2034, representing a 5.5% CAGR over 2026–2034.
  • Largest type: Hardware RAID holds the strongest commercial position because enterprise servers and storage appliances use dedicated controllers for predictable performance, cache protection and manageability.
  • Demand center: Internet & Cloud Services is the principal application segment, supported by cloud and data-center operators require resilient storage architectures across large server fleets.
  • Regional position: North America leads demand as the region has a dense hyperscale, enterprise data-center and server infrastructure base.
  • Growth driver: Growing data volumes and NVMe adoption are increasing requirements for resilient, high-throughput storage control.
  • Primary restraint: Software-defined storage and application-level replication can displace dedicated RAID in selected architectures.

Redundant Array of Independent Disks (RAID) Market Overview

RAID market was valued at USD 5.60 billion in 2025 and is estimated at USD 5.91 billion in 2026. It is projected to reach USD 9.09 billion by 2034, registering a CAGR of 5.5% over 2026–2034. North America held the leading regional position in 2025.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless stated otherwise

RAID combines multiple physical drives into logical storage sets to improve performance, availability or both, depending on the selected level. The commercial market includes dedicated hardware controllers, embedded server solutions and software implementations used across enterprise systems, data centers and industrial computing. RAID remains important because drive failures are inevitable at scale, while applications increasingly require predictable uptime and rapid recovery.

Technology migration from hard disk drives toward SSD and NVMe storage is changing controller requirements rather than removing them. Modern hardware RAID adapters must handle PCIe interfaces, mixed NVMe/SAS/SATA environments, high I/O rates, secure boot and fast rebuild behavior. Software RAID remains attractive where CPU resources are abundant and infrastructure is designed around software-defined control.

The market sits between component-level storage and higher-level data protection. RAID can protect against selected drive failures, but it does not replace backup, geographic replication or application recovery. Buyers therefore evaluate controllers as part of a broader availability architecture, with workload, drive type, server platform and total cost of ownership determining the preferred implementation.

Segment Analysis: By Type

By type, the market is segmented into Hardware RAID and Software RAID. Hardware RAID retains the leading commercial position in enterprise servers and appliances where dedicated processing, protected cache and vendor-supported management are valued. Software RAID competes effectively in flexible, software-defined environments.

Type Technical role Market position
Hardware RAID Dedicated controller manages arrays, cache and drive interfaces Leading commercial segment. Strong in enterprise servers, storage appliances and performance-sensitive deployments.
Software RAID Host CPU and operating system manage array functions Flexible and cost-effective for general-purpose servers, Linux environments and software-defined infrastructure.

Controller value is shifting toward NVMe performance

Dedicated RAID hardware is evolving from basic disk aggregation toward high-bandwidth data movement, security and lifecycle management. Broadcom states that its MegaRAID 9600 family supports NVMe, SAS and SATA devices and materially improves bandwidth, write latency and rebuild performance versus its prior generation, demonstrating how controller differentiation now centers on flash-era workloads.

Segment Analysis: By Application

By application, the market is segmented into Internet & Cloud Services, Enterprise IT, Industrial & Manufacturing, and Others. Internet and cloud environments generate strong demand because large server populations magnify the operational cost of drive failures and make standardized storage management valuable.

Application Demand characteristics
Internet & Cloud Services Large-scale server fleets require resilient storage, high I/O throughput and efficient recovery procedures.
Enterprise IT Database, virtualization and business applications use RAID to balance uptime, performance and storage cost.
Industrial & Manufacturing Edge servers and control systems favor dependable local storage in environments where downtime disrupts operations.
Others Includes specialized government, media, research and embedded storage deployments.

Segment Analysis: By End User

By end user, demand spans Large Enterprises, Small & Medium Enterprises and Data Center Operators. Data center operators and large enterprises purchase at scale and prioritize manageability, security and platform qualification, while SMEs often favor integrated server solutions with simpler lifecycle support.

End User Commercial relevance
Large Enterprises Use standardized server platforms and value vendor support, monitoring and predictable recovery.
Small & Medium Enterprises Prefer integrated, manageable solutions with clear cost and support structures.
Data Center Operators Operate large drive populations where performance, telemetry and rebuild behavior have fleet-level economic impact.

Segment Analysis: By RAID Level

RAID level selection is segmented into RAID 0–1, RAID 5–6, and RAID 10 and above. The trade-off is between usable capacity, redundancy, write performance and rebuild exposure. Enterprise buyers increasingly model these choices against SSD endurance and application-level replication.

RAID Level Commercial relevance
RAID 0–1 Simple striping or mirroring; favored where low complexity or strong read/write performance is important.
RAID 5–6 Parity-based protection improves usable capacity but requires careful rebuild and write-performance management.
RAID 10 and above Higher resilience and performance for critical workloads at the cost of additional drive capacity.

Redundant Array of Independent Disks (RAID) Market Size & Shape

Regional Analysis

North America leads the Redundant Array of Independent Disks (RAID) Market, with regional demand shaped by different combinations of manufacturing concentration, installed-base replacement, regulatory requirements and customer qualification. The market is therefore not a uniform global pool: supplier access depends on local production ecosystems, channel depth, technical support and the purchasing model used by major customers.

How does regional demand differ across the redundant array of independent disks (RAID) market?

North America leads through hyperscale cloud infrastructure, enterprise server deployment and a strong ecosystem of controller, server and storage vendors. Asia Pacific combines fast data-center expansion with large electronics manufacturing bases. Europe is a mature enterprise market shaped by data-sovereignty and efficiency requirements, while other regions are expanding with cloud and colocation infrastructure.

Region Position Growth outlook Demand profile What decides supplier selection
Asia Pacific High-growth High Manufacturing and new-capacity led Scale, qualification, local support
North America Largest Moderate to high Technology and replacement led Performance, support, compliance
Europe Established Moderate Compliance and specialty led Compliance, sustainability, engineering
South America Emerging Selective Import and distributor led Landed cost, availability, service
Middle East & Africa Emerging Selective to high Project and infrastructure led Reliability, integrator support, delivery
Asia Pacific HIGH GROWTH

What defines the Asia Pacific market?

Asia Pacific demand is shaped by dense electronics and semiconductor manufacturing ecosystems. RAID demand follows server refresh, cloud infrastructure growth and the transition toward NVMe-based storage platforms. Regional suppliers benefit from proximity to high-volume customers, while global vendors compete through technology, reliability and local engineering support.

Market positionHigh-growth
Growth outlookHigh
Demand profileManufacturing and new-capacity led
Market access gateCustomer qualification
Country / market Position in region What drives demand
China Major market Large electronics and semiconductor manufacturing base supports sustained purchasing and local supplier development.
Japan / Korea / Taiwan Technology-intensive Advanced manufacturing clusters emphasize quality, process control and long supplier qualification cycles.

Capacity additions and supply-chain localization reinforce Asia Pacific demand, but commercial access depends on demonstrated process capability rather than price alone.

North America LARGEST

What defines the North America market?

North America is characterized by technology-intensive customers, established installed bases and demanding qualification standards. RAID demand follows server refresh, cloud infrastructure growth and the transition toward NVMe-based storage platforms. Buyers tend to prioritize validated performance, security of supply and field support over lowest initial price.

Market positionLargest
Growth outlookModerate to high
Demand profileTechnology and replacement led
Market access gateVendor qualification
Country / market Position in region What drives demand
United States Largest in region Data-center, electronics, semiconductor and healthcare demand creates a broad installed base with stringent technical purchasing requirements.
Canada Smaller but established Demand is concentrated in enterprise, communications and specialized manufacturing applications.

Regional growth is supported by modernization and strategic manufacturing investment, although mature end markets create a larger replacement component than in Asia Pacific.

Europe COMPLIANCE LED

What defines the Europe market?

Europe combines advanced industrial demand with rigorous environmental, product-safety and supply-chain requirements. RAID demand follows server refresh, cloud infrastructure growth and the transition toward NVMe-based storage platforms. Suppliers that document traceability, energy efficiency and long-term support are better positioned in regulated and premium applications.

Market positionEstablished
Growth outlookModerate
Demand profileCompliance and specialty led
Market access gateCE and customer standards
Country / market Position in region What drives demand
Germany Industrial anchor Advanced manufacturing and electronics engineering support specification-led demand.
France / Netherlands Specialty markets Semiconductor, communications and enterprise infrastructure create selective demand for higher-value solutions.

European demand is less dependent on pure volume expansion and more on upgrades, efficiency, regulatory compliance and resilience of critical supply chains.

South America EMERGING

What defines the South America market?

South America is a smaller market where distributor inventory, import economics and technical service strongly influence purchasing. RAID demand follows server refresh, cloud infrastructure growth and the transition toward NVMe-based storage platforms. Brazil is the primary demand center, while other countries rely more heavily on imported equipment and components.

Market positionEmerging
Growth outlookSelective
Demand profileImport and distributor led
Market access gateLocal import requirements
Country / market Position in region What drives demand
Brazil Largest in region Electronics assembly, data infrastructure and industrial investment create the broadest addressable base in the region.
Mexico / Southern Cone Selective demand Purchasing is concentrated in multinational manufacturing networks and enterprise infrastructure.

Growth opportunities are strongest where suppliers can shorten lead times, support regional system integrators and maintain consistent spare-part or component availability.

Middle East & Africa PROJECT LED

What defines the Middle East & Africa market?

Middle East & Africa demand is concentrated in infrastructure programs, data centers, telecom networks and selected electronics or semiconductor investments. RAID demand follows server refresh, cloud infrastructure growth and the transition toward NVMe-based storage platforms. Project timing produces uneven order patterns, making channel coverage and delivery reliability commercially important.

Market positionEmerging
Growth outlookSelective to high
Demand profileProject and infrastructure led
Market access gateProject approvals
Country / market Position in region What drives demand
GCC Investment-led Data-center, digital infrastructure and industrial diversification projects create concentrated demand for advanced systems.
South Africa Established base Enterprise, telecom and industrial users provide the most developed demand base in Sub-Saharan Africa.

Suppliers typically compete through project qualification, integrator relationships and service reach rather than large continuous production volumes.

Key Redundant Array of Independent Disks (RAID) Market Manufacturers and Competitive Landscape

Competition spans storage-controller semiconductor vendors, server OEMs and specialized adapter suppliers. The strongest positions are built through silicon capability, firmware maturity, operating-system support, platform qualification and long product lifecycles rather than controller hardware alone.

Broadcom and Microchip compete at the controller and adapter layer, while Dell, HPE, Lenovo, IBM, Fujitsu and Supermicro integrate RAID into server platforms and lifecycle-management suites. This creates a layered market where component vendors may supply technology that is ultimately sold under an OEM system architecture.

Qualification matters because storage controllers sit directly in the data path. Customers expect stable firmware, driver support, secure boot capabilities, telemetry and predictable behavior under degraded arrays. A technically superior controller can still lose if it is not validated on the target server, operating system and drive set.

NVMe is raising the performance ceiling and making PCIe bandwidth, queue management and rebuild speed more important. At the same time, cloud-native architectures can shift redundancy above the device level, forcing hardware RAID vendors to prove value in latency-sensitive and enterprise workloads rather than assuming universal deployment.

Tier structure

Competitive tier Representative companies Basis of competition
Controller technology leaders Broadcom; Microchip RAID-on-chip silicon, firmware, NVMe/SAS/SATA support and OEM design wins.
Global server OEMs Dell; HPE; Lenovo; IBM; Fujitsu; NEC; Supermicro Integrated server platforms, management software, support and installed base.
Specialized storage vendors ATTO; QNAP; Synology; Promise Technology; Tyan Niche appliances, adapters and targeted storage use cases.

Companies profiled: Broadcom (Avago), Intel, Dell, HPE, Lenovo, IBM, Microchip (Adaptec), ATTO, Supermicro, Fujitsu, QNAP, Synology, Tyan, NEC, Promise Technology.

Redundant Array of Independent Disks (RAID) Market Production Capacity Analysis

RAID production capacity is tied primarily to controller silicon, printed circuit assembly and server-platform integration. Dedicated adapters use mature electronics manufacturing, but advanced controller availability depends on semiconductor foundry capacity, memory components, high-speed interfaces and firmware validation.

Server OEM capacity is geographically diversified, while controller silicon is more concentrated. This makes component qualification and supply assurance important during server refresh cycles. OEMs commonly validate specific controller and drive combinations, so changing a component can require engineering work beyond simple procurement.

The main constraint is not adapter assembly throughput but design and qualification bandwidth. New PCIe generations, NVMe support, security features and firmware updates must be validated across multiple operating systems and drive families before enterprise customers will adopt them at scale.

Redundant Array of Independent Disks (RAID) Market Market Dynamics: Drivers, Restraints and Opportunities

Growth comes from expanding digital data, data-center buildout and higher-performance flash storage, while software-defined redundancy changes where protection is implemented. Hardware RAID remains commercially important in enterprise and appliance architectures, but vendors must continue increasing throughput and security while demonstrating advantages over host-based or distributed software alternatives.

MARKET DRIVERS

Drivers Impact Analysis*

Driver Impact Commercial mechanism
Data-center storage growth High More servers and drives increase demand for resilient storage control.
NVMe transition High Raises controller bandwidth, latency and rebuild-performance requirements.
Enterprise uptime requirements Medium Supports dedicated, vendor-qualified storage protection.

Data growth expands protected storage fleets

Cloud, analytics, virtualization and enterprise applications create larger pools of persistent data. As drive counts increase, failures become routine operational events rather than exceptions, supporting technologies that automate redundancy, rebuild and monitoring.

NVMe raises performance expectations

Flash storage can expose controller bottlenecks that were hidden by slower disks. Modern RAID products therefore compete on PCIe bandwidth, IOPS, write latency and rebuild behavior, creating upgrade demand when servers move to newer NVMe generations.

Server refresh sustains controller replacement

RAID controllers are commonly purchased as part of a new server configuration. Platform refresh cycles therefore create recurring demand even when an existing array remains functional, because customers seek current firmware, security support and compatibility with new drive interfaces.

MARKET RESTRAINTS

Restraints Impact Analysis*

Restraint Impact Commercial mechanism
Software-defined storage High Distributed replication can move redundancy above the controller layer.
Cloud managed services Medium Some customers consume storage as a service rather than buying controllers directly.
Rebuild and parity overhead Medium Large-capacity arrays can face performance and recovery trade-offs.

Distributed software can replace device-level redundancy

Hyperscale and cloud-native systems may replicate data across nodes or availability zones, reducing dependence on traditional controller-based RAID. This is especially relevant where applications are designed to tolerate server failure and manage consistency at a higher layer.

Managed cloud shifts purchasing away from end users

Organizations that move workloads to public cloud no longer procure the underlying RAID hardware themselves. Demand does not disappear, but it becomes concentrated among cloud and data-center operators with substantial purchasing leverage and custom infrastructure preferences.

Complexity increases with high-capacity storage

Parity calculations, drive rebuilds and degraded-array operation can create performance risk, particularly as drive capacities rise. Customers may choose mirroring, erasure coding or application-level protection instead of conventional RAID for selected workloads.

MARKET OPPORTUNITIES

Tri-mode NVMe/SAS/SATA controllers

Controllers that support multiple drive interfaces simplify server platforms during the transition from legacy SAS/SATA to NVMe. This can reduce OEM inventory complexity and protect customer investment while enabling higher flash performance.

Security-enhanced storage adapters

Secure boot, device attestation and firmware integrity are increasingly relevant in enterprise infrastructure. Vendors can differentiate by embedding hardware-rooted security and integrating controller telemetry into broader server-management systems.

Edge and industrial servers

Factories, telecom sites and edge systems need local storage resilience where cloud connectivity may not be sufficient for real-time workloads. Rugged, manageable RAID solutions can capture these distributed deployments.

High-performance rebuild optimization

Faster rebuild and lower degraded-mode impact reduce operational risk in dense storage systems. Controller vendors that improve recovery behavior can create a measurable total-cost advantage for data-center customers with large fleets.

Redundant Array of Independent Disks (RAID) Market Supply Chain Analysis

Stage 1: Silicon and memory
RAID-on-chip devices, processors, cache memory and interface components.
Stage 2: Adapter / motherboard
Controller cards and embedded server implementations.
Stage 3: Server / storage OEM
Platform qualification, firmware integration and lifecycle support.
Stage 4: Enterprise / data center
Deployment, monitoring, drive replacement and data-protection policy.

Value is concentrated in controller silicon, firmware and platform validation. Adapter assembly is comparatively standardized, but the software stack and qualification matrix determine whether a product can be trusted in enterprise environments. Long support cycles make supplier stability strategically important.

The supply chain is moving toward tighter integration between storage controllers and server management. Telemetry, security state, drive health and firmware updates increasingly feed centralized infrastructure tools, making software integration a larger part of the purchasing decision.

Recent Developments in the Redundant Array of Independent Disks (RAID) Market

Current — Broadcom markets the MegaRAID 9670-24i for NVMe/SAS/SATA environments

Broadcom states that the 9600 series doubles bandwidth and materially improves RAID 5 IOPS and rebuild performance versus its prior generation, illustrating the performance demands created by NVMe storage. Source.

2025 — Dell continued current-generation PERC support across PowerEdge systems

Dell maintains a current list of PowerEdge RAID Controller families and platform support, reinforcing the importance of OEM qualification and lifecycle management in enterprise RAID purchasing. Source.

Current — Microchip continues SmartRAID adapter development

Microchip markets Adaptec SmartRAID adapters for enterprise storage, maintaining competition in dedicated hardware RAID alongside Broadcom and server OEM implementations. Source.

REPORT SCOPE & SEGMENTATION

Attribute Coverage
Market Redundant Array of Independent Disks (RAID) Market
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
By Type Hardware RAID, Software RAID
By Application Internet & Cloud Services, Enterprise IT, Industrial & Manufacturing, Others
By End User Large Enterprises, Small & Medium Enterprises, Data Center Operators
By RAID Level RAID 0–1, RAID 5–6, RAID 10 and above
Regions North America, Europe, Asia Pacific, South America, Middle East & Africa
Companies Profiled Broadcom (Avago), Intel, Dell, HPE, Lenovo, IBM, Microchip (Adaptec), ATTO, Supermicro, Fujitsu, QNAP, Synology, Tyan, NEC, Promise Technology

Frequently Asked Questions

What is the size of the Redundant Array of Independent Disks (RAID) Market?

The market was valued at USD 5.60 billion in 2025 and is projected to reach USD 9.09 billion by 2034, with a CAGR of 5.5% during 2026–2034.

Which region leads the market?

North America is the largest regional market, supported by the region has a dense hyperscale, enterprise data-center and server infrastructure base.

Which type leads the redundant array of independent disks (RAID) market?

Hardware RAID holds the leading position because enterprise servers and storage appliances use dedicated controllers for predictable performance, cache protection and manageability.

Which application is the largest?

Internet & Cloud Services is the principal application segment, driven by cloud and data-center operators require resilient storage architectures across large server fleets.

What are the main growth drivers?

Data-center growth, NVMe storage, enterprise uptime requirements and recurring server refresh cycles support demand.

What are the main restraints?

Software-defined storage, managed cloud services and alternative replication architectures can reduce the role of dedicated controllers in selected workloads.

What additional segmentation is covered?

The analysis also covers End User and RAID Level, enabling comparison beyond type and application.

How is competition structured?

Competition spans controller silicon vendors, server OEMs and specialist storage suppliers; firmware maturity and platform qualification are decisive.

What is changing in the supply chain?

The strategic bottlenecks are controller silicon, firmware and platform qualification rather than physical adapter assembly capacity.

Which companies are profiled?

Broadcom (Avago), Intel, Dell, HPE, Lenovo, IBM, Microchip (Adaptec), ATTO, Supermicro, Fujitsu, QNAP, Synology, Tyan, NEC, Promise Technology.

Research Sources & Evidence Base

View supporting primary and industry sources
  1. Broadcom: MegaRAID 9670-24i — current tri-mode controller performance and feature evidence.
  2. Dell Technologies: List of PowerEdge RAID Controller types — current PERC families and PowerEdge integration.
  3. Microchip: Adaptec SmartRAID RAID Adapters — current dedicated RAID adapter portfolio.
Redundant Array of Independent Disks (RAID) Market Size, Share & Industry Analysis, By Type (Hardware RAID, Software RAID), By Application (Internet & Cloud Services, Enterprise IT, Industrial & Manufacturing, Others), By End User (Large Enterprises, Small & Medium Enterprises, Data Center Operators), By RAID Level (RAID 0-1, RAID 5-6, RAID 10 and above), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Redundant Array of Independent Disks (RAID) Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Redundant Array of Independent Disks (RAID) Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Redundant Array of Independent Disks (RAID) Overall Market Size
2.1 Global Redundant Array of Independent Disks (RAID) Market Size: 2024 VS 2032
2.2 Global Redundant Array of Independent Disks (RAID) Market Size, Prospects & Forecasts: 2026-2034
2.3 Key Market Trends, Opportunity, Drivers and Restraints
2.3.1 Market Opportunities & Trends
2.3.2 Market Drivers
2.3.3 Market Restraints
3 Company Landscape
3.1 Top Redundant Array of Independent Disks (RAID) Players in Global Market
3.2 Top Global Redundant Array of Independent Disks (RAID) Companies Ranked by Revenue
3.3 Global Redundant Array of Independent Disks (RAID) Revenue by Companies
3.4 Top 3 and Top 5 Redundant Array of Independent Disks (RAID) Companies in Global Market, by Revenue in 2024
3.5 Global Companies Redundant Array of Independent Disks (RAID) Product Type
3.6 Tier 1, Tier 2, and Tier 3 Redundant Array of Independent Disks (RAID) Players in Global Market
3.6.1 List of Global Tier 1 Redundant Array of Independent Disks (RAID) Companies
3.6.2 List of Global Tier 2 and Tier 3 Redundant Array of Independent Disks (RAID) Companies
4 Sights by Product
4.1 Overview
4.1.1 Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Market Size Markets, 2024 & 2032
4.1.2 Hardware RAID Card
4.1.3 Software RAID Card
4.2 Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue & Forecasts
4.2.1 Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue, 2020-2025
4.2.2 Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue, 2026-2032
4.2.3 Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Market Size, 2024 & 2032
5.1.2 Internet Industry
5.1.3 Service Industry
5.1.4 Manufacturing Industry
5.1.5 Financial
5.1.6 Government
5.1.7 Others
5.2 Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue & Forecasts
5.2.1 Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue, 2020-2025
5.2.2 Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue, 2026-2032
5.2.3 Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
6 Sights by Region
6.1 By Region – Global Redundant Array of Independent Disks (RAID) Market Size, 2024 & 2032
6.2 By Region – Global Redundant Array of Independent Disks (RAID) Revenue & Forecasts
6.2.1 By Region – Global Redundant Array of Independent Disks (RAID) Revenue, 2020-2025
6.2.2 By Region – Global Redundant Array of Independent Disks (RAID) Revenue, 2026-2032
6.2.3 By Region – Global Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
6.3 North America
6.3.1 By Country – North America Redundant Array of Independent Disks (RAID) Revenue, 2026-2034
6.3.2 United States Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.3.3 Canada Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.3.4 Mexico Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4 Europe
6.4.1 By Country – Europe Redundant Array of Independent Disks (RAID) Revenue, 2026-2034
6.4.2 Germany Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4.3 France Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4.4 U.K. Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4.5 Italy Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4.6 Russia Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4.7 Nordic Countries Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.4.8 Benelux Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.5 Asia
6.5.1 By Region – Asia Redundant Array of Independent Disks (RAID) Revenue, 2026-2034
6.5.2 China Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.5.3 Japan Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.5.4 South Korea Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.5.5 Southeast Asia Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.5.6 India Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.6 South America
6.6.1 By Country – South America Redundant Array of Independent Disks (RAID) Revenue, 2026-2034
6.6.2 Brazil Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.6.3 Argentina Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.7 Middle East & Africa
6.7.1 By Country – Middle East & Africa Redundant Array of Independent Disks (RAID) Revenue, 2026-2034
6.7.2 Turkey Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.7.3 Israel Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.7.4 Saudi Arabia Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
6.7.5 UAE Redundant Array of Independent Disks (RAID) Market Size, 2026-2034
7 Companies Profiles
7.1 Broadcom(Avago Technologies)
7.1.1 Broadcom(Avago Technologies) Corporate Summary
7.1.2 Broadcom(Avago Technologies) Business Overview
7.1.3 Broadcom(Avago Technologies) Redundant Array of Independent Disks (RAID) Major Product Offerings
7.1.4 Broadcom(Avago Technologies) Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.1.5 Broadcom(Avago Technologies) Key News & Latest Developments
7.2 Intel
7.2.1 Intel Corporate Summary
7.2.2 Intel Business Overview
7.2.3 Intel Redundant Array of Independent Disks (RAID) Major Product Offerings
7.2.4 Intel Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.2.5 Intel Key News & Latest Developments
7.3 Dell
7.3.1 Dell Corporate Summary
7.3.2 Dell Business Overview
7.3.3 Dell Redundant Array of Independent Disks (RAID) Major Product Offerings
7.3.4 Dell Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.3.5 Dell Key News & Latest Developments
7.4 Fujitsu
7.4.1 Fujitsu Corporate Summary
7.4.2 Fujitsu Business Overview
7.4.3 Fujitsu Redundant Array of Independent Disks (RAID) Major Product Offerings
7.4.4 Fujitsu Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.4.5 Fujitsu Key News & Latest Developments
7.5 HP
7.5.1 HP Corporate Summary
7.5.2 HP Business Overview
7.5.3 HP Redundant Array of Independent Disks (RAID) Major Product Offerings
7.5.4 HP Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.5.5 HP Key News & Latest Developments
7.6 IBM
7.6.1 IBM Corporate Summary
7.6.2 IBM Business Overview
7.6.3 IBM Redundant Array of Independent Disks (RAID) Major Product Offerings
7.6.4 IBM Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.6.5 IBM Key News & Latest Developments
7.7 Lenovo
7.7.1 Lenovo Corporate Summary
7.7.2 Lenovo Business Overview
7.7.3 Lenovo Redundant Array of Independent Disks (RAID) Major Product Offerings
7.7.4 Lenovo Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.7.5 Lenovo Key News & Latest Developments
7.8 Microsemi
7.8.1 Microsemi Corporate Summary
7.8.2 Microsemi Business Overview
7.8.3 Microsemi Redundant Array of Independent Disks (RAID) Major Product Offerings
7.8.4 Microsemi Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.8.5 Microsemi Key News & Latest Developments
7.9 Supermicro
7.9.1 Supermicro Corporate Summary
7.9.2 Supermicro Business Overview
7.9.3 Supermicro Redundant Array of Independent Disks (RAID) Major Product Offerings
7.9.4 Supermicro Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.9.5 Supermicro Key News & Latest Developments
7.10 Areca Technology Corporation
7.10.1 Areca Technology Corporation Corporate Summary
7.10.2 Areca Technology Corporation Business Overview
7.10.3 Areca Technology Corporation Redundant Array of Independent Disks (RAID) Major Product Offerings
7.10.4 Areca Technology Corporation Redundant Array of Independent Disks (RAID) Revenue in Global Market (2020-2025)
7.10.5 Areca Technology Corporation Key News & Latest Developments
8 Conclusion
9 Appendix
9.1 Note
9.2 Examples of Clients
9.3 DisclaimerList of Tables
Table 1. Redundant Array of Independent Disks (RAID) Market Opportunities & Trends in Global Market
Table 2. Redundant Array of Independent Disks (RAID) Market Drivers in Global Market
Table 3. Redundant Array of Independent Disks (RAID) Market Restraints in Global Market
Table 4. Key Players of Redundant Array of Independent Disks (RAID) in Global Market
Table 5. Top Redundant Array of Independent Disks (RAID) Players in Global Market, Ranking by Revenue (2024)
Table 6. Global Redundant Array of Independent Disks (RAID) Revenue by Companies, (US$, Mn), 2020-2025
Table 7. Global Redundant Array of Independent Disks (RAID) Revenue Share by Companies, 2020-2025
Table 8. Global Companies Redundant Array of Independent Disks (RAID) Product Type
Table 9. List of Global Tier 1 Redundant Array of Independent Disks (RAID) Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Redundant Array of Independent Disks (RAID) Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2024 & 2032
Table 12. Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue (US$, Mn), 2020-2025
Table 13. Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue (US$, Mn), 2026-2032
Table 14. Segmentation by Application– Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2024 & 2032
Table 15. Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 16. Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 17. By Region– Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2024 & 2032
Table 18. By Region – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 19. By Region – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 20. By Country – North America Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 21. By Country – North America Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 22. By Country – Europe Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 23. By Country – Europe Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Asia Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 25. By Region – Asia Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 26. By Country – South America Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 27. By Country – South America Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 28. By Country – Middle East & Africa Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2020-2025
Table 29. By Country – Middle East & Africa Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2032
Table 30. Broadcom(Avago Technologies) Corporate Summary
Table 31. Broadcom(Avago Technologies) Redundant Array of Independent Disks (RAID) Product Offerings
Table 32. Broadcom(Avago Technologies) Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 33. Broadcom(Avago Technologies) Key News & Latest Developments
Table 34. Intel Corporate Summary
Table 35. Intel Redundant Array of Independent Disks (RAID) Product Offerings
Table 36. Intel Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 37. Intel Key News & Latest Developments
Table 38. Dell Corporate Summary
Table 39. Dell Redundant Array of Independent Disks (RAID) Product Offerings
Table 40. Dell Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 41. Dell Key News & Latest Developments
Table 42. Fujitsu Corporate Summary
Table 43. Fujitsu Redundant Array of Independent Disks (RAID) Product Offerings
Table 44. Fujitsu Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 45. Fujitsu Key News & Latest Developments
Table 46. HP Corporate Summary
Table 47. HP Redundant Array of Independent Disks (RAID) Product Offerings
Table 48. HP Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 49. HP Key News & Latest Developments
Table 50. IBM Corporate Summary
Table 51. IBM Redundant Array of Independent Disks (RAID) Product Offerings
Table 52. IBM Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 53. IBM Key News & Latest Developments
Table 54. Lenovo Corporate Summary
Table 55. Lenovo Redundant Array of Independent Disks (RAID) Product Offerings
Table 56. Lenovo Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 57. Lenovo Key News & Latest Developments
Table 58. Microsemi Corporate Summary
Table 59. Microsemi Redundant Array of Independent Disks (RAID) Product Offerings
Table 60. Microsemi Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 61. Microsemi Key News & Latest Developments
Table 62. Supermicro Corporate Summary
Table 63. Supermicro Redundant Array of Independent Disks (RAID) Product Offerings
Table 64. Supermicro Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 65. Supermicro Key News & Latest Developments
Table 66. Areca Technology Corporation Corporate Summary
Table 67. Areca Technology Corporation Redundant Array of Independent Disks (RAID) Product Offerings
Table 68. Areca Technology Corporation Redundant Array of Independent Disks (RAID) Revenue (US$, Mn) & (2020-2025)
Table 69. Areca Technology Corporation Key News & Latest Developments

List of Figures
Figure 1. Redundant Array of Independent Disks (RAID) Product Picture
Figure 2. Redundant Array of Independent Disks (RAID) Segment by Type in 2024
Figure 3. Redundant Array of Independent Disks (RAID) Segment by Application in 2024
Figure 4. Global Redundant Array of Independent Disks (RAID) Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Redundant Array of Independent Disks (RAID) Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Redundant Array of Independent Disks (RAID) Revenue: 2026-2034 (US$, Mn)
Figure 8. The Top 3 and 5 Players Market Share by Redundant Array of Independent Disks (RAID) Revenue in 2024
Figure 9. Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2024 & 2032
Figure 10. Segmentation by Type – Global Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 11. Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2024 & 2032
Figure 12. Segmentation by Application – Global Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 13. By Region – Global Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 14. By Country – North America Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 15. United States Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 16. Canada Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 17. Mexico Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 18. By Country – Europe Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 19. Germany Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 20. France Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 21. U.K. Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 22. Italy Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 23. Russia Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 24. Nordic Countries Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 25. Benelux Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 26. By Region – Asia Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 27. China Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 28. Japan Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 29. South Korea Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 30. Southeast Asia Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 31. India Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 32. By Country – South America Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 33. Brazil Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 34. Argentina Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 35. By Country – Middle East & Africa Redundant Array of Independent Disks (RAID) Revenue Market Share, 2026-2034
Figure 36. Turkey Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 37. Israel Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 38. Saudi Arabia Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 39. UAE Redundant Array of Independent Disks (RAID) Revenue, (US$, Mn), 2026-2034
Figure 40. Broadcom(Avago Technologies) Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 41. Intel Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 42. Dell Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 43. Fujitsu Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 44. HP Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 45. IBM Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 46. Lenovo Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 47. Microsemi Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 48. Supermicro Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 49. Areca Technology Corporation Redundant Array of Independent Disks (RAID) Revenue Year Over Year Growth (US$, Mn) & (2020-2025)