Key Statistics
Key Takeaways
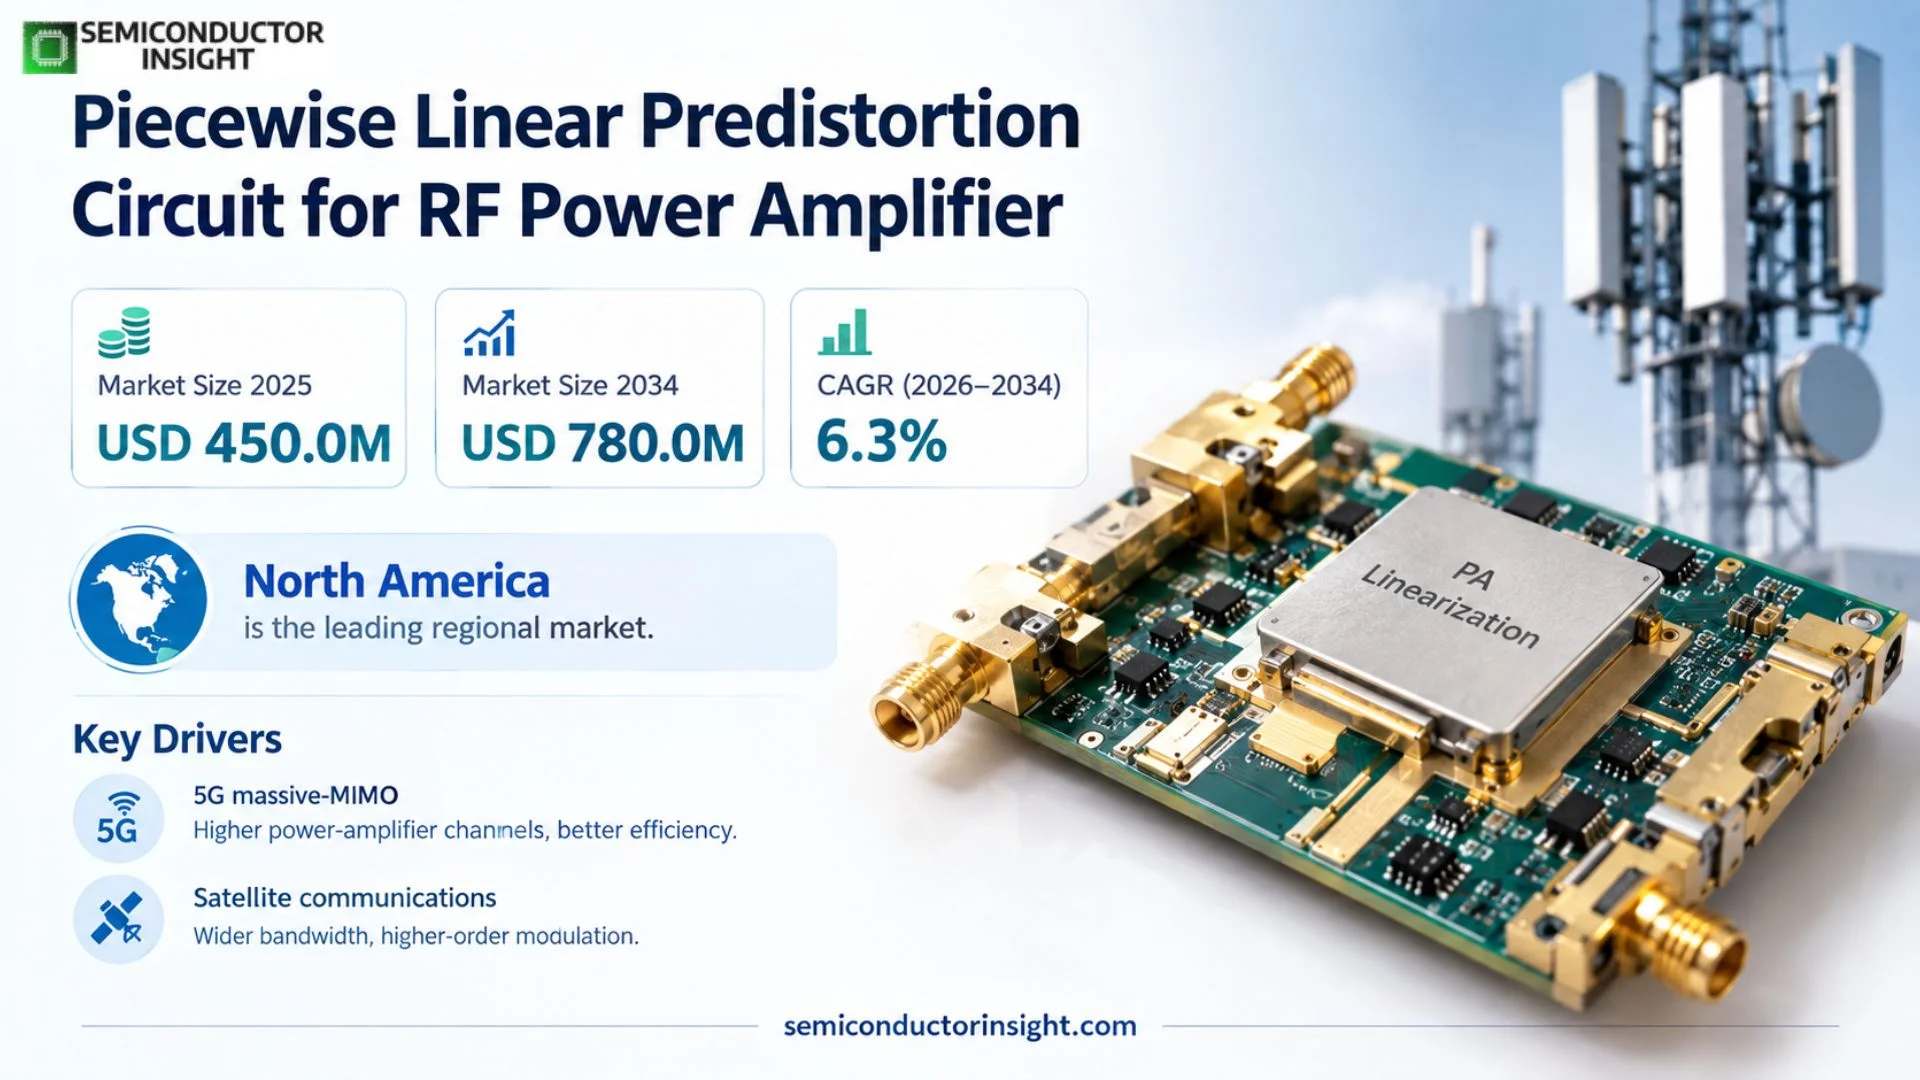
- Market size and growth: the market is estimated at USD 478.4 million in 2026 and is projected to reach USD 780.0 million by 2034, representing a 6.3% CAGR during 2026–2034.
- Digital predistortion is the leading type because software-controlled coefficients can adapt to amplifier behavior across bandwidth, temperature and power levels while supporting modern software-defined radio architectures.
- Cellular base stations remain the largest application as massive-MIMO radio units require high-efficiency RF power amplifiers that still meet strict adjacent-channel and spectral-emission limits.
- North America leads through Qorvo, Analog Devices, NXP, Skyworks and defense or satellite programs, while Asia Pacific is the largest high-volume deployment region for 5G radio infrastructure.
- Integration is moving toward chip-level and SoC implementations, reducing board area, calibration overhead and parasitic losses while allowing adaptive algorithms to respond to changing operating conditions.
Piecewise Linear Predistortion Circuit for RF Power Amplifier Market Overview
Piecewise Linear Predistortion Circuit for RF Power Amplifier market was valued at USD 450.0 million in 2025 and is estimated at USD 478.4 million in 2026. The market is projected to reach USD 780.0 million by 2034, representing a CAGR of 6.3% during 2026–2034. North America is the leading regional market because the region combines major RF semiconductor companies, telecom-equipment R&D, satellite programs and early adoption of advanced linearization technologies.
Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated
Piecewise linear predistortion is a power-amplifier linearization technique that approximates the inverse of a nonlinear RF amplifier transfer characteristic using multiple linear segments. The corrected input signal compensates for gain compression and phase distortion so the amplifier can operate closer to its efficient high-power region without violating spectral-emission limits. The technique is used in cellular radios, satellite transmitters, industrial RF systems and other broadband applications where power efficiency and linearity must be achieved simultaneously.
The market is shifting toward digital implementations because coefficients can be recalculated as the amplifier changes with temperature, frequency, device aging and traffic load. Analog predistortion still offers low-latency and compact architectures in selected systems, but digital control aligns more naturally with software-defined radios and modern baseband processing. Semiconductor vendors increasingly integrate predistortion support with data converters, transceivers, RF front ends and control software rather than selling isolated correction circuits.
5G massive-MIMO and satellite communications are the main structural demand drivers. Large antenna arrays multiply the number of power-amplifier channels, so even small efficiency improvements can materially reduce power and cooling requirements at a base station. At the same time, wider modulation bandwidths and higher-order modulation make nonlinear distortion more difficult to manage. This increases the value of adaptive predistortion that can preserve error-vector magnitude and adjacent-channel performance across changing network conditions.
Segment Analysis: By Type
By type, the market is segmented into digital predistortion and analog predistortion. Digital predistortion leads because it can support adaptive coefficients, wider bandwidths and real-time recalibration through firmware or baseband processing. Analog predistortion remains useful where designers prioritize low latency, low implementation complexity and compact RF signal paths. The market trend favors hybrid architectures that combine analog front-end correction with digital optimization for demanding broadband systems.
| Type | Technical / commercial role | Market position |
|---|---|---|
| Digital Predistortion | Digital or mixed-signal correction before the RF power amplifier using adaptive models and coefficient updates. | Leading segment; strongest fit for 5G, massive MIMO and software-defined radio. |
| Analog Predistortion | Analog circuits create an inverse nonlinear response in the RF or IF path. | Smaller but relevant where latency, simplicity or compact implementation is critical. |
Segment Analysis: By Application
Applications include cellular base stations, satellite repeaters, IoT edge devices and other RF systems. Cellular infrastructure is the largest application because macro and massive-MIMO radios must maximize amplifier efficiency while meeting strict spectral masks. Satellite systems value predistortion because onboard power is constrained and signal integrity must remain stable across wide temperature ranges. IoT and industrial RF systems use lower-cost approaches where battery life, thermal limits and regulatory compliance still matter.
| Application | Demand characteristics |
|---|---|
| Cellular Base Stations | Largest application; massive-MIMO radios use many PA channels and need strong efficiency with low adjacent-channel leakage. |
| Satellite Repeaters | High-power and power-constrained payloads benefit from linearization that preserves spectral efficiency. |
| IoT Edge Devices | Compact low-power radios use simplified predistortion where efficiency and compliance justify the added circuitry. |
| Others | Includes broadcasting, radar, aerospace, test systems and specialized industrial RF platforms. |
Segment Analysis: By End User
End users are led by telecom operators and equipment vendors because 5G radio networks create the largest installed base of linearized power amplifiers. Satellite service providers form a smaller but technically demanding market where power budgets and spectral efficiency are critical. Industrial OEMs use predistortion in RF heating, communications, broadcast and specialized wireless equipment. Each user group values different trade-offs between algorithm sophistication, implementation cost, bandwidth and long-term calibration stability.
| End User | Demand logic |
|---|---|
| Telecom Operators | Primary demand through 4G/5G radio infrastructure and massive-MIMO deployments. |
| Satellite Service Providers | High-value use where power and spectrum efficiency are constrained. |
| Industrial OEMs | Application-specific demand across broadcast, industrial RF and aerospace systems. |
Segment Analysis: By Integration Level
Integration level is becoming a strategic differentiator. Standalone modules provide flexibility for legacy or custom radio architectures, while chip-level integration reduces board area and shortens signal paths. System-on-chip approaches can combine digital predistortion, data converters, baseband processing and control logic in one platform, improving calibration and production scalability. As radio architectures become more software defined, suppliers increasingly compete on how seamlessly predistortion is integrated with the broader transceiver and amplifier control stack.
| Integration Level | Commercial role |
|---|---|
| Standalone Modules | Flexible deployment for legacy systems, custom radios and specialized equipment. |
| Chip-Level Integration | Lower board area and parasitic loss with tighter PA/transceiver co-design. |
| System-on-Chip Solutions | Highest integration; combines signal processing, control and radio functions for scalable platforms. |
Regional Analysis
North America is the leading regional market, supported by a large RF semiconductor base, defense and satellite programs, and early deployment of advanced linearization algorithms. Asia Pacific is the largest volume opportunity through dense 5G infrastructure and radio manufacturing in China, Japan and South Korea. Europe remains technically strong in telecom infrastructure and energy-efficient radio design, while South America and Middle East & Africa are smaller deployment-led markets.
Regional demand follows the geography of 5G infrastructure, satellite programs and RF semiconductor engineering. North America captures high-value design and aerospace demand, Asia Pacific combines high unit deployment with radio-equipment manufacturing, and Europe emphasizes energy efficiency and telecom standards. Emerging regions adopt predistortion primarily as part of imported base-station or satellite equipment, so their market depends more on network rollout timing than on local semiconductor manufacturing.
| Region | Position | Growth outlook | Demand profile | Supplier-selection factor |
|---|---|---|---|---|
| North America | Leading | High | RF semiconductors, satellite, defense | Algorithm performance and integration |
| Asia Pacific | High-volume growth | High | 5G deployment and radio manufacturing | Cost, efficiency and scale |
| Europe | Established | Moderate-High | Telecom and energy-efficient infrastructure | Standards and power reduction |
| South America | Emerging | Moderate | Network modernization | Cost and vendor support |
| Middle East & Africa | Emerging | Moderate | 5G, satellite and defense | Reliability and technical support |
Competitive Landscape
Competition in the Piecewise Linear Predistortion Circuit for RF Power Amplifier market is shaped by technology performance, customer qualification, application engineering and continuity of supply. Leading companies use product breadth and global support to win large programs, while specialist suppliers can defend attractive niches through deeper technical performance in specific applications. As the market expands, customers increasingly evaluate total system value and lifecycle support rather than relying only on initial component price.
The leading suppliers compete through a combination of proprietary technology, manufacturing scale and customer relationships. In the Piecewise Linear Predistortion Circuit for RF Power Amplifier market, design wins can remain in place for several product generations because switching suppliers often requires requalification, software changes or manufacturing adjustments. This creates durable revenue positions for vendors that deliver reliable performance and responsive technical support.
Regional suppliers can still gain share where local availability, cost and fast engineering response matter. Their strongest opportunities are generally in standardized or mature applications, while the highest-performance segments remain concentrated among companies with deeper intellectual property, process control and qualification histories. This creates a market structure with both global platform leaders and specialized regional competitors.
Competitive strategy is increasingly moving toward integrated solutions. Customers prefer suppliers that can combine the core product with software, interface components, testing, support or adjacent technologies because integration reduces project risk and development time. Companies able to solve a broader customer problem therefore have more pricing power than vendors competing only on a single specification.
| Competitive tier | Representative companies | Competitive basis |
|---|---|---|
| Global technology leaders | Qorvo, Skyworks Solutions, Analog Devices, NXP Semiconductors | Scale, broad product portfolios, strong R&D and global customer support. |
| Established specialists | Infineon Technologies, Texas Instruments, MACOM Technology Solutions, Murata Manufacturing | Application-specific engineering and strong qualification in selected segments. |
| Regional / emerging suppliers | STMicroelectronics, Microchip Technology, ROHM Semiconductor, L3Harris Technologies, Broadcom, Qualcomm Technologies | Local service, competitive pricing and focused customer relationships. |
Key Participants
The profiled competitive set includes Qorvo, Skyworks Solutions, Analog Devices, NXP Semiconductors, Infineon Technologies, Texas Instruments, MACOM Technology Solutions, Murata Manufacturing, STMicroelectronics, Microchip Technology, ROHM Semiconductor, L3Harris Technologies, Broadcom, Qualcomm Technologies. Supplier position depends on engineering performance, customer qualification, manufacturing continuity and the ability to support design changes over long product cycles. Larger vendors benefit from broad portfolios and application teams, while specialists can retain strong positions in narrow, technically demanding subsegments where historical qualification and process know-how create meaningful switching costs.
Production Capacity Analysis
Production capacity for Piecewise Linear Predistortion Circuit for RF Power Amplifier is constrained by the combination of specialized equipment, qualified materials, process know-how and customer-specific validation. Nominal factory output can overstate commercial supply because a new line or material source must often demonstrate consistent performance before it can serve high-value customers. This makes qualified capacity more important than raw nameplate capacity.
Regional manufacturing and service capacity influence lead time and resilience. Customers increasingly prefer suppliers that can support major production clusters from more than one site, reducing exposure to logistics disruption and single-factory events. At the same time, duplicating specialized processes can be difficult because equipment recipes, trained engineers and quality systems must be transferred without changing product performance.
The strongest capacity investments are aligned with structural demand drivers rather than short-term cycles. Suppliers expanding around AI, advanced semiconductor manufacturing, automotive electronics or industrial automation seek to secure positions before customer volumes scale. Effective capacity therefore includes engineering resources, test capability and local technical support in addition to physical manufacturing equipment.
| Capacity factor | Market implication |
|---|---|
| Specialized manufacturing | Determines qualified output and technical performance. |
| Critical materials / components | Can constrain supply despite available factory floor space. |
| Qualification and test | Controls how quickly new capacity becomes usable by customers. |
| Regional support | Improves lead time, resilience and customer retention. |
Market Dynamics
The Piecewise Linear Predistortion Circuit for RF Power Amplifier market is driven by higher system performance, automation, digitalization and expanding use in high-value applications. Growth is moderated by development cost, qualification requirements and supply-chain concentration. The strongest opportunities occur where new architectures or applications create a clear performance advantage and where suppliers can reduce integration complexity for customers.
MARKET DRIVERS
| Driver | Relative impact | Commercial mechanism |
|---|---|---|
| Structural end-market growth | High | Expanding deployments increase unit demand and installed-base requirements. |
| Technology upgrade cycle | High | Higher performance raises value per product and accelerates replacement. |
| Customer integration needs | Medium-High | Validated solutions reduce engineering time and project risk. |
| Regional capacity expansion | Medium | New manufacturing clusters create local supplier demand. |
Structural end-market expansion
Growth in the Piecewise Linear Predistortion Circuit for RF Power Amplifier market is supported by rising deployment across its principal applications. Customers are investing because the technology improves performance, efficiency, automation or product capability in ways that are difficult to replicate with older approaches. This expands both new-system demand and the installed base that later requires replacement, upgrades or related services.
Higher technical requirements increase value per system
New product generations demand tighter performance, greater integration and better reliability. These requirements can increase selling prices even when unit volumes grow more slowly, because customers are willing to pay for solutions that protect yield, uptime or user experience. Suppliers with stronger engineering capability therefore benefit disproportionately from technology transitions.
Regional investment broadens customer access
Manufacturing and infrastructure investment in North America, Europe and Asia is creating additional customer clusters outside traditional centers. Local engineering support and shorter supply chains help suppliers qualify products earlier in new projects, creating an opportunity to win design positions before production reaches full scale.
MARKET RESTRAINTS
| Restraint | Relative impact | Commercial mechanism |
|---|---|---|
| Development and qualification cost | High | Raises barriers to entry and lengthens customer adoption. |
| Supply-chain concentration | Medium-High | Critical components or materials can limit output. |
| Price pressure | Medium | Customers seek lower total system cost as volumes increase. |
| Technology substitution | Medium | Alternative architectures can replace incumbent solutions in selected uses. |
Qualification slows supplier switching
Customers in technical markets cannot change suppliers based only on purchase price. New products must demonstrate performance, reliability and compatibility in the actual application, which can require months of engineering work. This limits the pace at which new entrants gain share and can delay commercialization of technically promising products.
Specialized inputs can constrain supply
Advanced products depend on a limited number of qualified materials, components or manufacturing tools. Shortages or long lead times at one upstream stage can restrict finished-product output even when downstream assembly capacity is available. Suppliers therefore carry strategic inventory or qualify alternate sources, but those actions increase cost.
Customer cost pressure remains persistent
As a technology becomes more widely adopted, customers expect lower unit costs and may redesign systems to use standardized components. Suppliers must offset this pressure through better performance, lower manufacturing cost and additional software or service value. Vendors that cannot maintain differentiation can face margin erosion even in a growing market.
MARKET OPPORTUNITIES
Massive-MIMO radio efficiency
Each active antenna contains many PA channels, so small efficiency gains compound across the radio. Suppliers that reduce distortion while allowing the amplifier to operate closer to compression can lower cooling and power requirements without sacrificing spectral compliance. This creates premium value in dense 5G deployments where site power and thermal limits are increasingly important.
Satellite broadband and non-terrestrial networks
Satellite repeaters and user terminals operate under constrained power budgets and must maintain clean spectra across changing operating conditions. Adaptive predistortion can help extract more usable output from RF power devices, particularly in high-power or wideband links. Growth in non-terrestrial networks therefore expands the addressable market beyond terrestrial base stations.
AI-assisted adaptive calibration
Machine-learning methods can model nonlinear amplifier behavior and update coefficients under changing temperature, aging and traffic conditions. The opportunity is not only higher linearity but lower manual calibration and faster product qualification. Vendors that package algorithms with RF transceivers and development tools can make advanced predistortion accessible to engineering teams with limited specialist DSP resources.
Chip-level integration
Integrating correction, observation receivers and control logic closer to the PA reduces board area and simplifies production. The opportunity favors semiconductor suppliers that can co-design transceiver and power-amplifier control functions, creating platform-level solutions that are easier for radio OEMs to qualify and scale across multiple frequency bands.
Supply Chain Analysis
Specialized materials and components
Core product manufacturing
Qualification and system integration
End-user deployment, service and replacement
The upstream supply chain provides the specialized materials, semiconductor devices, mechanical components or substrates that determine baseline product performance. Qualified inputs are important because changes in composition or manufacturing source can alter reliability, electrical behavior or process compatibility. Suppliers therefore maintain close technical relationships with upstream partners and often approve alternate sources before a disruption occurs.
Manufacturing converts these inputs into finished products using process-specific equipment, inspection and test. Quality systems are central because customers expect lot-to-lot consistency and traceability, particularly in semiconductor, automotive and industrial applications. High-value suppliers differentiate through process control rather than simple assembly scale, and they invest heavily in metrology or validation to protect yield.
Downstream value is created when the product is integrated into the customer system and validated under real operating conditions. Application engineers support installation, software, calibration or process optimization, while service teams maintain the installed base. This lifecycle relationship creates recurring revenue through replacement, updates, refurbishment or expansion and makes customer support an important part of the market structure.
Recent Developments
2026 – RF vendors continue integrating digital linearization with transceiver platforms
Major RF semiconductor companies continue developing transceiver, PA-control and signal-processing platforms that combine digital correction with high-efficiency RF power stages for 5G and broadband communications. Source
2026 – 5G massive-MIMO sustains demand for high-efficiency linearized PAs
Wideband active-antenna radios continue to require power-amplifier linearization that balances adjacent-channel performance with lower power and cooling requirements. Source
2026 – Satellite and aerospace RF systems increase interest in adaptive correction
High-power satellite and aerospace radios increasingly value adaptive correction because spectrum efficiency, thermal limits and power budgets are tightly constrained across long mission lifetimes. Source
REPORT SCOPE & SEGMENTATION
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Year | 2034 |
| 2025 Market Size | USD 450.0 million |
| 2026 Market Size | USD 478.4 million |
| 2034 Market Size | USD 780.0 million |
| CAGR | 6.3% during 2026–2034 |
| Largest Market / Leading Geography | North America |
| By Type | Digital Predistortion; Analog Predistortion |
| By Application | Cellular Base Stations; Satellite Repeaters; IoT Edge Devices; Others |
| By End User | Telecom Operators; Satellite Service Providers; Industrial OEMs |
| By Integration Level | Standalone Modules; Chip-Level Integration; System-on-Chip Solutions |
Frequently Asked Questions
What is the size of the Piecewise Linear Predistortion Circuit for RF Power Amplifier market?
The market is estimated at USD 478.4 million in 2026 and is projected to reach USD 780.0 million by 2034, representing a 6.3% CAGR during 2026–2034.
Which type leads the market?
Digital predistortion leads because adaptive coefficients, firmware updates and wideband signal processing fit modern 5G and software-defined radio architectures.
Which application is largest?
Cellular base stations are the largest application because massive-MIMO radios require many power-amplifier channels that must remain efficient and spectrally compliant.
Which region leads the market?
North America leads through RF semiconductor design, satellite programs and advanced telecom R&D, while Asia Pacific is the highest-volume deployment region.
What drives market growth?
5G network expansion, wider channel bandwidths, massive MIMO, satellite communications and the need to reduce base-station energy consumption are the main drivers.
What are the main restraints?
Algorithm complexity, calibration requirements, specialist RF/DSP skills and integration cost can slow adoption in lower-volume or cost-sensitive systems.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF