Key Statistics
Key Takeaways
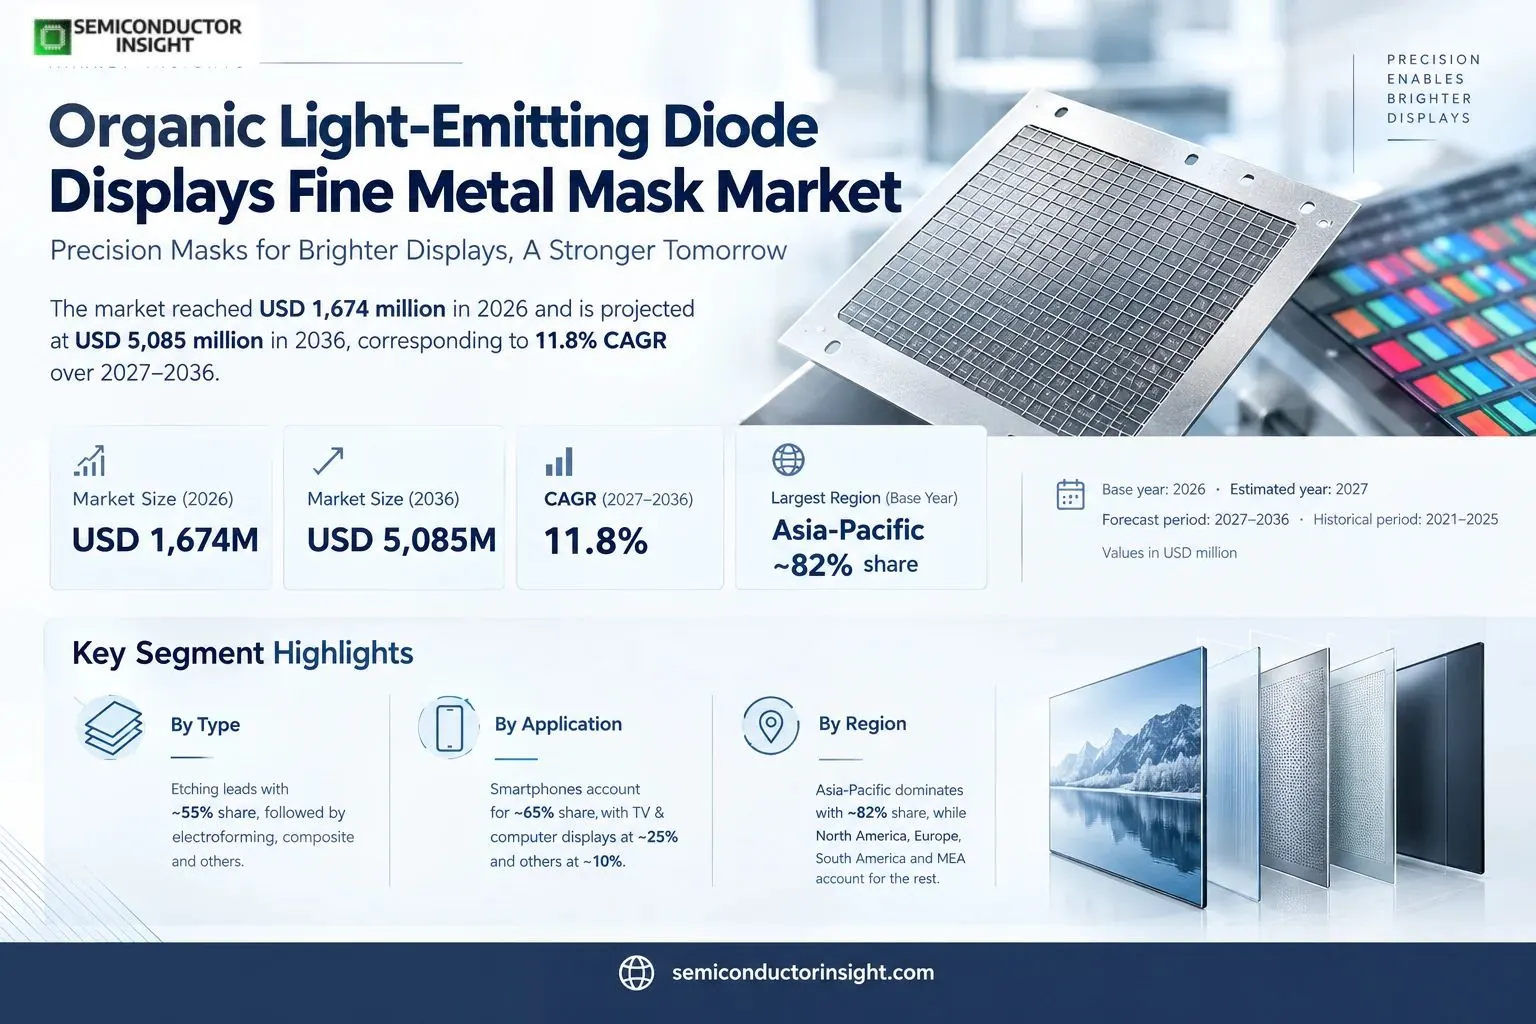
- Market trajectory: The precision OLED deposition mask market has a 2026 base of USD 1,674 million and a 2036 outlook of USD 5,085 million, implying 11.8% compound annual growth during 2027–2036; procurement follows qualified RGB panel manufacturing capacity rather than retail electronics revenue.
- Etching technology: Etched fine metal masks account for an estimated ~55% of 2026 sales, ahead of electroformed variants at ~25%, composite constructions at ~15% and specialized alternatives at ~5%; aperture repeatability and large-substrate flatness govern selection.
- Smartphone exposure: Handset OLED fabrication represents an estimated ~65% of mask purchases in 2026, while televisions and computers together represent ~25% and other display applications ~10%; tablet and notebook adoption can change this mix.
- Asia-Pacific leadership: Japan, South Korea and China together underpin an estimated ~82% of 2026 revenue because fine metal mask fabrication and qualified RGB OLED deposition lines are concentrated in the region; no other geography approaches this installed manufacturing footprint.
- Manufacturing transition: DNP began operating a Kurosaki line in May 2024 for eighth-generation OLED masks; expansion from G6 to G8 substrate formats raises the economic value of tension control, precise etching and yield-preserving mask maintenance.
- Competitive substitution: Mask-free pixel patterning promoted by LG Display and Visionox creates a long-run alternative to conventional RGB evaporation masks, although a research demonstration or technology unveiling does not automatically remove existing mask demand.
Organic Light-emitting Diode Displays Fine Metal Mask Market Overview
Organic light-emitting diode displays fine metal mask market reached USD 1,674 million in 2026 and is projected at USD 5,085 million in 2036, corresponding to 11.8% CAGR over 2027–2036. Asia-Pacific commands an estimated ~82% of the base-year revenue because the region contains the main precision mask manufacturing sites and most RGB OLED panel deposition capacity.
A fine metal mask is a thin patterned metallic stencil placed close to an OLED substrate during vacuum deposition. Separate red, green and blue organic emitter materials pass through microscopic apertures and land at designated subpixel locations. This is a production consumable and precision tool rather than a display panel: its value depends on aperture geometry, thermal expansion, frame tension, substrate compatibility and repeatable placement. The masks can be supplied as sheets, mounted assemblies or tailored sets qualified for a specific display fabrication process.
Revenue in this market includes etched, electroformed, multi-material composite and other precision masks sold for RGB organic light-emitting diode deposition. It does not include completed smartphone displays, the deposition chambers that hold the masks, the organic emitters themselves, conventional semiconductor EUV photomasks or equipment built around mask-free OLED lithography. The distinction prevents counting the entire value of a tablet panel as mask sales when the panel maker purchases a comparatively narrow set of manufacturing components.
The commercial cycle begins with panel makers specifying substrate size, pixel pitch, registration tolerance and lifetime expectations. A supplier then qualifies an aperture pattern, sheet thickness, frame design and cleaning process for a particular line. Small dimensional changes can impair color purity or produce subpixel defects across thousands of sites, so a mask that costs more to make may still lower total panel cost when it extends cleaning intervals or improves deposition yield. Repeat qualification and tooling revisions therefore influence revenue independently of consumer device unit growth.
Dai Nippon Printing began a dedicated large-mask line at its Kurosaki plant in May 2024, following a November 2022 investment announcement. The line supports eighth-generation glass and supplements the existing Mihara manufacturing base. Larger substrates are important because a G8 sheet can yield more laptop or tablet panels than a G6 sheet, but the mechanical span also raises challenges in sag, thermal movement and aperture uniformity. Precision tooling remains essential when panel producers seek better substrate utilization.
The industry has two simultaneous technology paths. Conventional FMM evaporation is established for many high-resolution RGB panels and requires successive color-aligned deposition steps. In parallel, mask-free methods such as LG Display’s FLiPP and Visionox’s ViP seek to pattern emitters without a conventional fine metal mask. These approaches are substitutes, not FMM sales, and their production qualification, lifetime and manufacturing cost must be judged separately from their public technical demonstrations.
The modeled 2026 geographic distribution assigns ~82% to Asia-Pacific, ~7% to North America, ~7% to Europe, ~2% to South America and ~2% to Middle East and Africa. These are estimated allocations of mask revenue, not independently audited shipment statistics. A country may host major OLED design centers without manufacturing the masks locally; the purchasing location of a panel factory and the manufacturing location of its mask supplier can also differ.
Segment Analysis: By Type
The technology split separates four methods for forming accurate RGB deposition apertures. Etching is estimated to represent ~55% of 2026 revenue, electroforming ~25%, multi-material composite construction ~15% and other specialized processes ~5%. Each approach trades mask thickness, opening shape, thermal behavior and process complexity differently; qualification by a panel manufacturer is more decisive than a supplier’s generic catalogue specification.
| Type | Fabrication and qualification characteristics | Commercial position |
|---|---|---|
| Etching | Photolithographic patterning and chemical etching create dense apertures in thin metal sheets. The process benefits from controlled feature placement, scalable batch fabrication and established know-how for red, green and blue pixel definition. For G6 and G8 display substrates, suppliers must control etch taper, opening variation, sheet stress and the distortion introduced when the mask is stretched into a supporting frame. | Estimated ~55% of 2026 revenue and the leading manufacturing approach. DNP documents its use of photolithography and etching in commercial OLED masks, including the 2024 Kurosaki expansion. Yield and reproducibility are more important than a simple lowest-price comparison because defects can affect many panels in a deposition lot. |
| Electroforming | Electrodeposition builds a thin metallic patterned layer through a template, potentially allowing different thickness and aperture-wall profiles from conventional subtractive etching. Dimensional control depends on plating uniformity, release behavior, thermal treatment and repeatability when the sheet is mounted. Buyers compare shadowing, mechanical stability and achievable feature pitch under their specific organic deposition conditions. | Estimated ~25% of 2026 sales. Electroformed masks compete where thin-wall geometry or custom material properties justify process development, but a laboratory aperture demonstration does not prove qualification for continuous RGB panel manufacture. The procurement decision remains tied to panel yield, replacement frequency and production engineering support. |
| Multi Material Composite Method | Composite masks combine layers or materials to improve stiffness, thermal expansion matching or dimensional stability under repeated vacuum cycles. Their design must address interfaces, bonding durability, frame attachment and thermal stress, especially when large substrates are heated unevenly during deposition. Qualification requires assessing the entire mounted mask assembly rather than a single metal foil. | Estimated ~15% share in 2026. The method attracts interest as mask dimensions increase and deformation becomes more costly, yet composite designs carry extra process steps and qualification expense. Their commercial role depends on whether a more stable aperture field offsets the added manufacturing and inspection burden. |
| Others | Other precision-mask methods include hybrid finishing, proprietary pattern transfer, localized reinforcement and specialized constructions for unusual pixel geometries. These are not a proxy for mask-free OLED production: an approach that deposits RGB emitters without a stencil is excluded from the market. Customers still require verified aperture maps, contamination controls and repeatable tension after cleaning. | Estimated ~5% in 2026, with demand concentrated in engineering trials and specialist panel formats. Small revenue share does not imply technical irrelevance because an alternative method can later influence mainstream tooling design. Commercial expansion requires evidence of qualified repeat production rather than publicity around a prototype. |
Why etched masks lead RGB deposition
Etched metal masks retain a practical advantage because established manufacturing recipes connect photolithographic definition, chemical material removal, metrology and frame assembly. DNP’s 2024 Kurosaki capacity addition supports G8 glass formats, showing that suppliers are extending a familiar method to larger substrates rather than abandoning precision apertures. The estimated ~55% type share reflects installed equipment, supplier experience and the cost of requalifying alternative mask materials across high-volume lines.
How electroforming and composite approaches compete
Electroforming and composite masks together account for an estimated ~40% of 2026 revenue in the modeled split. Their commercial appeal is strongest where panel producers demand thinner apertures, lower sag or greater stability over repeated heat cycles. Electroformed patterns need uniform deposition and release; composites require durable interfaces and matched thermal behavior. Both approaches face longer evaluation when a process change could alter red, green or blue subpixel alignment.
Engineering outlook through 2036
The mask supplier’s problem evolves from aperture resolution alone to total-process control. Across 2027–2029, the main priority is qualifying larger masks without yield loss; during 2030–2032, equipment and mask co-design become more important; and by 2033–2036, competitive alternatives could reduce some conventional mask opportunities. Those dates describe planning windows, not announced factory schedules. Each procurement decision ultimately rests on repeatable panel yields rather than an isolated material property.
Segment Analysis: By Application
The application mix is led by smartphones at an estimated ~65% of 2026 mask demand, followed by television and computer displays at ~25% and other applications at ~10%. This allocation refers to mask-related manufacturing revenue, not the retail value of the finished devices. A transition from G6 handset production to G8 IT OLED capacity changes the geometry and price of tooling even if overall panel volumes grow more slowly.
| Application | Demand characteristics |
|---|---|
| Smartphone | High-resolution RGB handset panels drive an estimated ~65% of mask sales because subpixel pitch and repeat color registration place stringent demands on aperture uniformity. Mask suppliers serve qualified deposition lines over multiple phone generations, with new designs introduced when pixel density, brightness or panel geometry changes. Replacement orders can persist even during slower smartphone shipment years. |
| TV and Computer | Estimated ~25% of 2026 revenue comes from computer, tablet, notebook and certain television OLED applications. DNP’s G8 Kurosaki line was introduced for larger IT display substrates, where panel economics reward higher glass utilization but require much wider and flatter masks. Not every television OLED technology uses the same RGB FMM process, so panel architecture matters when identifying the addressable demand. |
| Others | The remaining estimated ~10% covers wearable, automotive, industrial and specialist display uses that rely on RGB evaporation masks. Small formats can need demanding pixel alignment, while vehicle panels require long product life and supply continuity. This category excludes the entire value of finished dashboard clusters or watches and excludes display architectures that do not purchase conventional fine metal masks. |
Handset programs are the most repeatable purchasing channel because manufacturers refresh panel specifications frequently while retaining mature production lines. An estimated ~65% share is therefore plausible even as the market diversifies toward laptops and tablets. Higher resolution can increase inspection requirements and the cost of defective aperture arrays, but the mask supplier must balance that technical value against panel makers’ purchasing leverage and the cost of alternative manufacturing methods.
For IT OLED, a G8 substrate offers an economic reason to qualify a different mask size, but qualification is not automatic. Larger frames can deform during vacuum cycles, and organic material can spread differently across a wider aperture field. The estimated ~25% application share reflects emerging large-format mask demand alongside an installed handset base. The procurement opportunity depends on specific RGB process architectures rather than every advertised OLED notebook launch.
Specialist displays form an estimated ~10% application share, with demand influenced by automotive durability testing, wearable form factors and medical or industrial instrument needs. Buyers may order smaller batches, customized patterns and longer-lived tooling rather than the highest-volume handset masks. Revenue growth in this segment can therefore differ from finished-device unit growth, especially when a supplier provides application engineering or repeated qualification services around the same mask design.
Regional Analysis
Asia-Pacific is the principal manufacturing center with an estimated ~82% of 2026 fine metal mask revenue. North America and Europe each account for ~7%, while South America and the Middle East and Africa contribute ~2% apiece. These shares describe modeled component-market allocations; the geography of smartphone purchases does not reveal where RGB evaporation masks are bought or produced.
Where are OLED fine metal masks manufactured and purchased?
Demand follows the location of qualified RGB OLED deposition lines, with precision mask suppliers and panel makers working through lengthy process approvals. Japan has major mask manufacturing capability, South Korea has leading OLED panel engineering, and China combines large panel production with alternative pixel-patterning research. Outside Asia-Pacific, research and specialized display activity creates smaller orders. The geographic pattern therefore differs markedly from global retail electronics sales.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Estimated ~82% | ~12.2% CAGR | Largest | Pixel-aperture yield, frame precision and customer qualification |
| North America | Estimated ~7% | ~9.6% CAGR | Specialist demand | Qualification at overseas fabs and precision metrology |
| Europe | Estimated ~7% | ~9.4% CAGR | Equipment and research | Engineering qualification and low-volume procurement |
| South America | Estimated ~2% | ~8.0% CAGR | Small import-led market | Imported tooling, customs and small project economics |
| Middle East & Africa | Estimated ~2% | ~7.8% CAGR | Emerging project demand | Access to imported high-precision mask suppliers |
Competitive Landscape of OLED Fine Metal Mask Suppliers
The market has a narrow group of proven high-precision mask producers and a wider set of potential entrants, panel-equipment suppliers and display technology developers. DNP documents commercial OLED metal mask manufacture, while Poongwon’s 2026 reported FMM evaluation remained subject to customer approval. Other names in the sector require product-level verification before being characterized as qualified volume suppliers.
Dai Nippon Printing has a documented record in photolithographic and etched OLED masks, and its 2024 Kurosaki expansion targets larger substrates. The company’s own integrated reporting discusses leadership in metal masks for small and medium OLEDs. That supports a leading competitive position but does not establish a precise numerical share for all vendors or for every process category. Contract awards remain sensitive to proprietary aperture recipes and panel-specific qualification.
Poongwon Precision is a relevant Korean precision metal-mask company, but a March 2026 trade report described final customer qualification as underway rather than complete. This distinction matters because panel makers can test masks extensively before committing to mass production. A supplier’s ability to fabricate a fine aperture pattern is only the first step; stable deposition yields, replacement consistency and documented cleaning performance determine repeat business.
Toppan, Darwin, Sewoo, Athene, Shandong Aolai, Lianovation and APS Holdings appear in industry supplier discussions, but their current commercial roles differ and not all have independently verified 2026 RGB FMM volume production. Equipment, research, specialty-metal and mask-fabrication businesses should be described by demonstrated products rather than automatically assigned identical market shares. Concentration percentages are especially unreliable without a consistent definition of the mask revenue pool.
The threat from LG Display’s FLiPP and Visionox’s ViP is strategic rather than an immediate addition to supplier capacity. These technologies aim to form OLED pixels without conventional FMM stencils. They may eventually change process selection, but mask-free patents and demonstrations are not fine metal mask shipments. Investors and buyers should distinguish alternative manufacturing architectures from qualified vendors selling precision masks into current evaporation lines.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Established direct producer | Dai Nippon Printing (DNP) | Documented production of OLED metal masks, including a G8-compatible Kurosaki line operational from May 2024; process expertise spans photolithography, etching, mask tensioning and high-volume customer qualification. The company also maintains another production base in Mihara, providing operational redundancy for customers requiring stable delivery. |
| Qualification-stage and specialist ecosystem | Poongwon Precision; other named precision-mask developers | Poongwon was reported in March 2026 to be undergoing final customer assessment, not yet confirmed for mass-production approval. Additional suppliers may offer open masks, specialty masks, equipment or experimental FMM designs, but product and customer qualification should be established before counting them as proven direct volume competitors. |
| Adjacent and substitute technologies | LG Display; Visionox; Samsung Display | Samsung Display is a panel maker and technical user of RGB FMM processes; LG Display and Visionox have publicized FMM-free patterning approaches. Their inclusion describes demand-side process choices and substitution pressure, not a claim that they sell conventional fine metal masks as independent suppliers. |
Key companies profiled
- Dai Nippon Printing (DNP)
- TOPPAN Holdings
- Poongwon Precision
- Darwin
- Sewoo
- Athene
- Shandong Aolai Electronic Technology
- Lianovation
- APS Holdings
- Samsung Display (process user)
- LG Display (FMM-free alternative)
- Visionox (FMM-free alternative)
OLED Fine Metal Mask Production and Capacity Analysis
Fine metal mask manufacturing links thin-metal processing, micro-aperture fabrication, precision inspection, frame attachment and delivery to a qualified OLED deposition line. A mask’s effective capacity is determined not just by how many sheets a factory makes, but by the proportion that meet pixel-registration requirements after tensioning and repeated vacuum exposure.
The manufacturing chain begins with alloy selection and thickness control. Photolithography and etching produce the aperture field, while electroforming or composite processing can offer alternative geometries. Inspection systems must detect defects that would translate into missing or misplaced red, green and blue subpixels. Frame mounting adds another dimensional variable because stretching a thin mask changes aperture positions. High-volume panel customers therefore require statistical process control across materials, fabrication and final assembly.
DNP’s Kurosaki facility commenced operation in May 2024 and supports G8 OLED glass, according to the company’s June 2024 release. The new site complements Mihara and was presented as a way to increase output and strengthen business continuity. This is an identifiable supply addition, but the announcement’s production-capacity ambition should not be interpreted as a measured 2026 global FMM market share or as evidence that all planned output has been absorbed by panel customers.
Mask maintenance and replacement affect factory economics throughout the 2027–2036 period. Cleaning, thermal cycling and repeated alignment can shorten usable life, while better aperture stability may reduce replacement frequency. A panel manufacturer evaluates total cost per accepted OLED panel rather than only the price of a new mask. Consequently, material improvements can lower annual mask units even as they increase the value and complexity of each qualified assembly.
Capacity investment is exposed to architecture change. Conventional FMM production depends on RGB evaporation, whereas FLiPP and ViP seek to remove the stencil from pixel definition. Suppliers considering large G8 lines must weigh the durability of established processes against the possibility that some future panel capacity adopts mask-free patterning. The risk is technological substitution over several product generations, not an immediate cancellation of every existing qualified mask order.
OLED Fine Metal Mask Market Dynamics, Drivers and Restraints
Growth reflects expansion of high-resolution OLED panel fabrication, larger IT display substrates, and recurring tooling qualification, while precision-yield challenges and mask-free alternatives temper the outlook. The modeled contribution table allocates the 2027–2036 annual growth rate across these forces; it is a scenario decomposition rather than a separately observed statistical series.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2027–2029 | 2030–2032 | 2033–2036 |
|---|---|---|---|---|---|
| G8 IT OLED mask qualification and capacity | High | +5.00% | High | High | Medium |
| RGB smartphone deposition upgrades | High | +4.10% | High | Medium | Medium |
| Higher pixel density and mask precision | Medium-High | +3.20% | High | High | High |
| Replacement, maintenance and qualification cycles | Medium | +2.10% | Medium | Medium | Medium |
| New panel lines and regional supplier diversification | Low-Medium | +1.70% | Medium | Medium | High |
| Others (wearables, automotive displays, process engineering) | Low | +1.20% | Low | Medium | Medium |
Larger IT OLED formats need new tooling
G8 glass allows a different panel layout from the G6 lines long used for handset OLED. DNP’s Kurosaki line began operation in 2024 to supply masks compatible with this larger format, creating a direct precedent for precision-mask investment. The modeled +5.0 percentage-point contribution captures demand for new frames, aperture layouts and qualification programs as notebook and tablet OLED manufacturing grows, rather than assuming every OLED laptop requires the same stencil process.
Smartphone production sustains the installed base
High-resolution RGB smartphone lines continue to use qualified deposition masks with tight color alignment requirements. Even if annual phone shipments fluctuate, mask replacements and design changes can support recurring purchases across multiple panel generations. The modeled +4.1-point contribution reflects the installed manufacturing base and the cost of changing a qualified process, while allowing for gradual substitution by alternative pixel-patterning technologies.
Resolution and aperture uniformity raise unit value
Smaller pixel pitches place more emphasis on opening geometry, shadowing, registration and inspection. A defect in one mask can influence many subpixels and increase scrap, so a more accurate tool can justify a higher purchase price. The estimated +3.2-point contribution represents rising precision content per qualified mask, not a forecast that the number of apertures or pixel density increases at a fixed annual rate.
Replacement cycles create non-new-build demand
Masks experience repeated cleaning, heating and mechanical handling during vacuum deposition, which can affect tension and dimensional stability. Panel manufacturers therefore maintain replacement and inspection schedules alongside new-line purchases. The modeled +2.1-point contribution recognizes this installed-base demand, although improved mask durability could reduce the number of replacements required per year while increasing the price of a more sophisticated assembly.
Supplier diversification can unlock new programs
A new FMM supplier must clear stringent process qualification before entering mass production. Poongwon’s reported March 2026 evaluation illustrates the commercial importance of final customer approval, while DNP’s two-site approach illustrates continuity planning. The estimated +1.7-point contribution assumes qualified alternatives can improve procurement resilience without counting evaluation-stage capacity as already shipped commercial volume.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2027–2029 | 2030–2032 | 2033–2036 |
|---|---|---|---|---|---|
| Mask-free OLED pixel patterning | High | -2.30% | Medium | High | High |
| G8 dimensional stability and qualification losses | Medium-High | -1.60% | High | High | Medium |
| Concentrated customer qualification and pricing pressure | Medium | -1.00% | High | Medium | Medium |
| Others (cleaning limits, inspection costs, material waste) | Low | -0.60% | Medium | Medium | Low |
Mask-free technologies challenge the addressable process
LG Display publicly introduced FLiPP in August 2026 as a patterning route that does not use conventional FMM, and Visionox describes a separate FMM-free ViP architecture. Neither announcement is counted as FMM revenue. The modeled −2.3 percentage-point effect reflects the possibility that future OLED fabs select these alternatives, reducing mask purchases relative to a scenario where all new RGB lines retain stencil evaporation.
Large-area mask handling raises qualification risk
An eighth-generation substrate increases the span across which a thin patterned sheet must retain position and flatness. Sag, thermal expansion, frame distortion and uneven deposition can create yield loss, making process approval slow and costly. The modeled −1.6-point effect captures development expense and rejected masks during the transition to larger formats, not a claim that G8 production is commercially impossible.
Few buyers can dictate specifications and prices
Mask suppliers serve a limited number of OLED panel manufacturing groups, each with proprietary deposition equipment and demanding acceptance tests. Long qualifications create switching costs but also give large buyers negotiating power over unit pricing and service terms. The estimated −1.0-point contribution captures pressure on suppliers to absorb tooling improvements and inventory obligations without equivalent price increases.
MARKET OPPORTUNITIES
Process co-design for eighth-generation lines
Mask manufacturers can partner with panel and deposition-equipment engineers on frame stiffness, aperture compensation and cleaning recipes specifically for G8 substrates. A joint qualification program may create durable supply relationships because a process change affects yield across thousands of subpixels. The opportunity is strongest where suppliers demonstrate repeatable dimensional control and service support, rather than promoting unqualified mask designs as interchangeable components.
Specialized displays and replacement services
Automotive displays, wearable panels and industrial interfaces may need customized mask geometries, longer product support and low-volume production. Suppliers able to provide design revisions, inspection certificates and replacement logistics can earn value beyond the initial sheet sale. Such business remains within the precision-mask component boundary and should not be inflated by adding the value of the finished display or vehicle.
Diversified qualified supply and risk reduction
Panel makers may seek a second approved mask source to protect against factory disruptions and long replenishment lead times. DNP’s Kurosaki and Mihara facilities demonstrate the value of geographic redundancy, while Poongwon’s customer testing illustrates the hurdle faced by prospective entrants. A supplier that clears production qualification can win a strategic role even without claiming an unsupported market-share percentage.
OLED Fine Metal Mask Supply Chain and Commercialization
Commercial fine metal masks sit between specialty metal processing and OLED panel fabrication. Value is created through aperture fidelity, controlled sheet stress, frame assembly, inspection and the ability to reproduce the same qualified design across production lots. End-market demand reaches mask suppliers only through panel production programs that actually use RGB stencil deposition.
Materials and aperture fabrication. The first supply-chain constraint is the ability to turn thin metal into a stable high-density aperture field. Photolithographic etching is well established at DNP, while alternative electroforming and composite approaches must meet comparable inspection requirements. The material supplier’s specifications, process chemistry and contamination controls affect downstream panel yield, so mask producers need stable inputs and documented lot histories across many manufacturing runs.
Qualification and equipment integration. A mask is not commercially interchangeable simply because its aperture dimensions appear similar on a drawing. The panel maker must evaluate frame tension, alignment in the deposition chamber, heating behavior and cleaning cycles. A new supplier may spend months proving compatibility with a particular RGB process, and an evaluation-stage project should not be represented as approved volume production until the customer confirms it.
Regional logistics and continuity. Manufacturing concentration in Japan and the wider Asia-Pacific OLED ecosystem creates efficient technical collaboration but also exposes buyers to single-source disruption. DNP’s 2024 Kurosaki opening provided another manufacturing site alongside Mihara, improving operational resilience. International customers still require reliable packaging, transit protection and rapid replacement when a mask fails inspection or an OLED panel line changes its product mix.
Technology substitution and future contracts. Mask-free OLED pixel patterning could eventually change the required component bill of materials, but adoption depends on qualified yield and device lifetime. LG Display’s FLiPP and Visionox’s ViP should be monitored as alternative architectures, not included in FMM unit shipments. Suppliers can defend their position by lowering the total cost per good RGB panel through better precision, cleaning performance and large-area tooling support.
Recent Developments in OLED Fine Metal Mask Technology and Supply
- 10 November 2022 Capacity plan
DNP announced a plan to establish a large OLED metal-mask line at its Kurosaki plant with an investment of about JPY 20 billion and compatibility with eighth-generation substrates. The plan aimed to serve growing tablet and notebook OLED manufacturing and to provide backup capacity for Mihara. It was a direct precision-mask capacity commitment, not a completed panel manufacturing facility. Source - 12 June 2024 Factory operation
DNP confirmed that its Kurosaki metal-mask production line had started operating in May 2024 for G8 OLED glass. The announcement explained that precise apertures are used for separate RGB organic deposition and described a plan to expand capacity. This was a verified operational milestone for FMM supply and a reference point for large-substrate manufacturing economics. Source - 2024 integrated report Supplier disclosure
DNP’s 2024 integrated reporting identified OLED metal masks as an electronics growth business and described the Kurosaki expansion alongside the company’s photolithography and etching capabilities. This dated corporate disclosure supports the existence of commercial mask production but does not establish a precise percentage of total global FMM revenue for all suppliers. Source - 25 September 2025 IT OLED ecosystem
Samsung Display convened its 2025 IT OLED summit with customers and partners to discuss notebook and monitor OLED development and showed a range of display technologies. This is adjacent demand evidence for larger OLED formats, not a direct announcement that Samsung began selling fine metal masks. The distinction matters because only mask-compatible RGB deposition lines translate the wider display opportunity into FMM procurement. Source - 12 March 2026 Supplier qualification
Korean trade reporting described Poongwon Precision as entering final evaluation with a display-panel customer for fine metal masks, with subsequent commercial deliveries conditional on approval. The event signals possible diversification of the supplier base but does not prove completed mass-production qualification or volume shipments. The supplier’s technical progress should be tracked separately from booked mask revenue. Source - 19 August 2026 Substitute technology
LG Display announced FLiPP, a pixel-patterning approach designed to eliminate conventional fine metal masks from its OLED process. The unveiling is relevant as a long-term substitution risk, not as additional FMM capacity. Any effect on mask orders depends on whether the alternative process achieves the yield, lifetime and scale required for commercial panel manufacturing. Source - 11 October 2026 Process competition
LG Display published a technical briefing on FLiPP’s potential role in eighth-generation OLED manufacturing, reinforcing the strategic interest in mask-free approaches. This remains adjacent evidence about an alternative pixel-definition process and must not be counted as FMM product sales. For incumbent mask suppliers, the significance is the need to demonstrate competitive cost per accepted panel. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Market definition | Precision fine metal masks used for red, green and blue organic-emitter deposition in OLED manufacturing; includes etched, electroformed, composite and specialized stencil masks, excludes panels, chambers and FMM-free patterning. |
| Base-year market size | USD 1,674 million |
| Estimated-year market size | USD 1,870 million |
| Forecast market size | USD 5,085 million |
| CAGR | 11.8% |
| Historical period | 2021–2025 |
| Forecast period | 2027–2036 |
| Study period | 2021–2036 |
| By Type | Etching · Electroforming · Multi Material Composite Method · Others |
| By Application | Smartphone · TV and Computer · Others |
| By Region | Estimated 2026 shares by region: Asia-Pacific ~82%; North America ~7%; Europe ~7%; South America ~2%; Middle East & Africa ~2%. Asia-PacificJapan, South Korea, China, Taiwan, Southeast Asia North AmericaUnited States, Canada, Mexico EuropeGermany, France, United Kingdom, Benelux, Rest of Europe South AmericaBrazil, Argentina, Chile, Colombia, Rest of South America Middle East & AfricaIsrael, United Arab Emirates, South Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Dai Nippon Printing (DNP); TOPPAN Holdings; Poongwon Precision; Darwin; Sewoo; Athene; Shandong Aolai Electronic Technology; Lianovation; APS Holdings; Samsung Display (process user); LG Display and Visionox (mask-free alternatives). |
| Customization Scope | Customer-specific G6 and G8 mask demand, etching versus electroforming economics, OLED pixel pitch, process qualification, replacement cycles, country sourcing and mask-free technology substitution can be examined separately from finished panel sales. |
Frequently Asked Questions
What is the projected size of the OLED fine metal mask market?
The precision RGB OLED fine metal mask market is valued at USD 1,674 million in 2026 and projected to reach USD 5,085 million by 2036, with 11.8% CAGR during 2027–2036. These figures concern mask components used in deposition, not finished OLED screens. They are driven by qualification of G8 IT display lines, handset tooling replacements and rising precision requirements.
Which region leads OLED fine metal mask demand?
Asia-Pacific holds an estimated ~82% of 2026 mask revenue because Japan hosts documented precision-mask manufacturing and South Korea and China contain major OLED deposition capacity. North America and Europe each represent an estimated ~7%, with South America and the Middle East and Africa near ~2% each. The allocation follows manufacturing demand rather than consumer electronics sales.
Why is etching the largest mask fabrication type?
Etching represents an estimated ~55% of 2026 fine metal mask sales because established photolithography and chemical removal processes provide repeatable aperture arrays. DNP documents commercial use of these methods and expanded G8-compatible manufacturing in 2024. Electroforming and composite approaches offer different mechanical properties but still require rigorous qualification on the intended RGB OLED deposition line.
How much demand comes from smartphones?
Smartphones account for an estimated ~65% of the 2026 application mix, reflecting the large installed base of high-resolution RGB OLED handset fabrication. Television and computer applications contribute ~25%, while wearables, automotive and other specialized displays account for ~10%. These shares describe mask-related manufacturing purchases and should not be interpreted as the retail revenue split of the devices themselves.
What does a fine metal mask do in OLED manufacturing?
An FMM directs evaporated organic emitter material through a dense array of small apertures so red, green and blue subpixels form in designated positions. Separate deposition stages create the individual colors. Its dimensional stability, tension and cleanliness affect color registration and panel yield. The mask is a precision production tool rather than an OLED panel or semiconductor lithography photomask.
How does G8 manufacturing affect FMM suppliers?
Eighth-generation glass allows panel manufacturers to process larger substrates for IT OLED products, potentially improving substrate utilization. It also demands larger precision masks that resist sag and thermal distortion. DNP’s Kurosaki line began operating in May 2024 for G8-compatible masks, making the shift a concrete supply-chain development. Qualification costs and yield risks can offset some capacity advantages.
Are mask-free OLED processes included in FMM revenue?
No. LG Display’s FLiPP and Visionox’s ViP are alternative pixel-patterning approaches designed to avoid conventional fine metal masks. Their technical progress may reduce future FMM demand, but sales of equipment, intellectual property or displays using mask-free processes do not count as precision-mask shipments. Existing RGB evaporation lines continue to require qualified masks unless their manufacturing architecture changes.
Which companies are confirmed commercial fine metal mask suppliers?
Dai Nippon Printing has direct public documentation of commercial OLED metal-mask production and a G8-compatible Kurosaki facility. Poongwon Precision was reported to be in final customer qualification in March 2026, which is not the same as confirmed volume approval. Other company names in industry listings may represent specialty mask development, equipment or adjacent businesses and require product-specific verification.
What restrains growth in the market?
The largest modeled restraint is competition from mask-free OLED pixel patterning, followed by dimensional stability challenges as masks become larger. Concentrated customer purchasing power and the cost of inspection, cleaning and replacement also affect suppliers. The technology risk unfolds over the 2027–2036 forecast period and does not imply that all currently qualified RGB mask production will disappear immediately.
How should market share estimates be interpreted?
The modeled shares allocate 2026 mask-related revenue across five regions, four fabrication types and three application groups. They are analytical estimates informed by published manufacturing evidence and process economics, not company-reported audited market shares. A share such as Asia-Pacific ~82% or etching ~55% should be read alongside the revenue boundary and the qualification status of the relevant suppliers.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF