Key Statistics
Key Takeaways
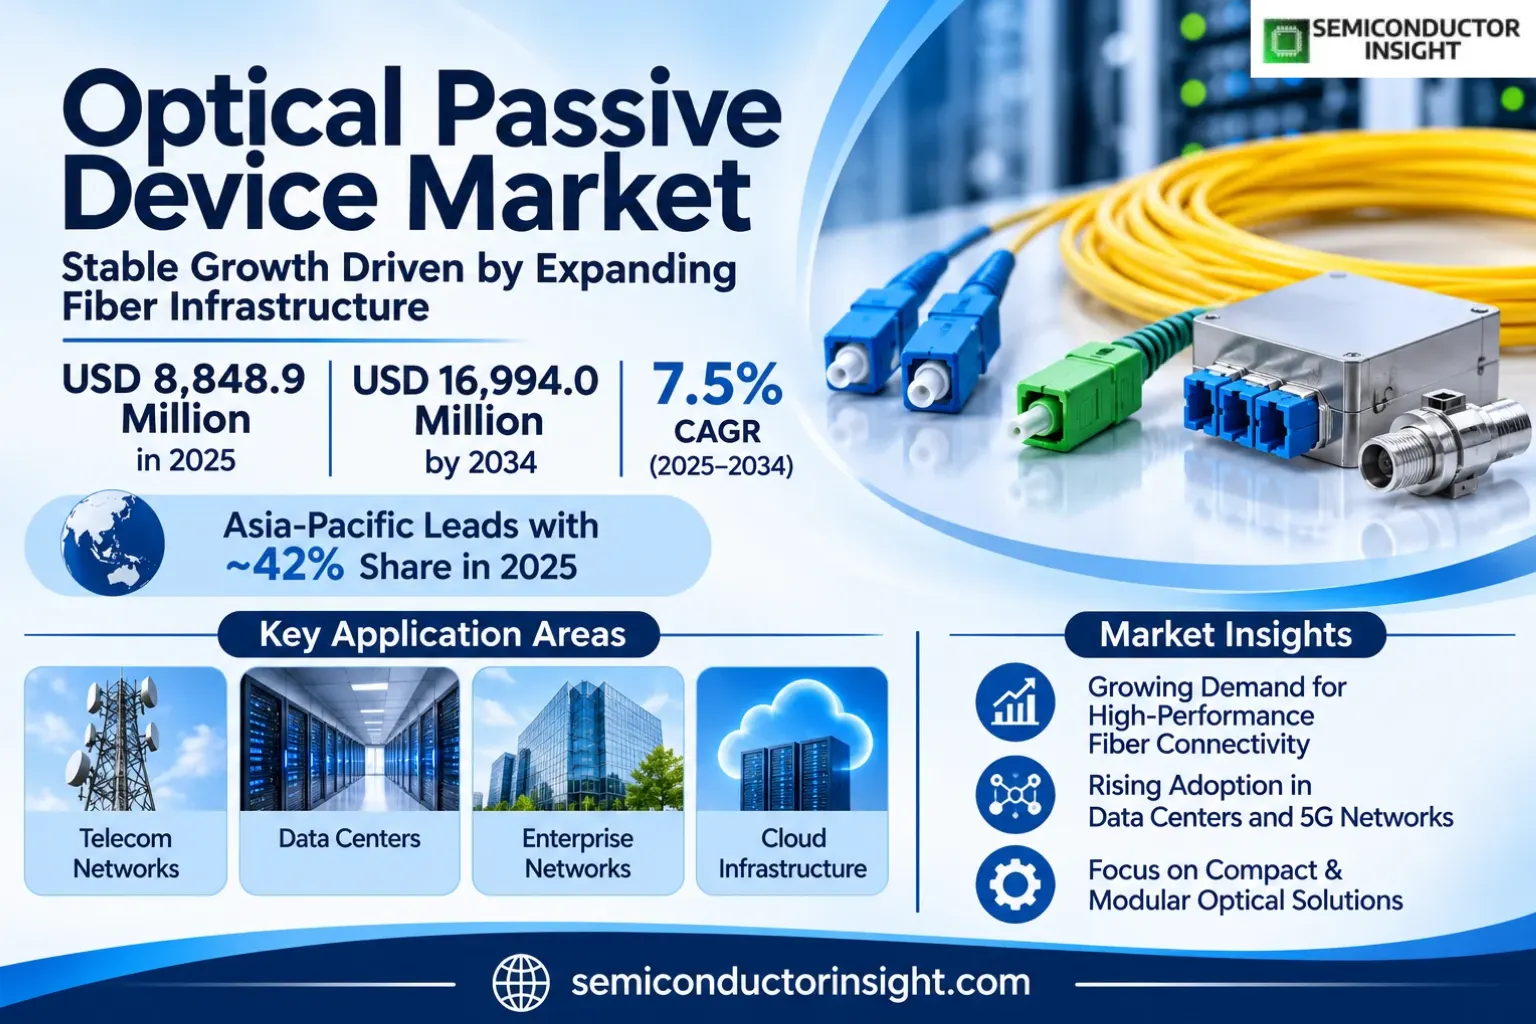
- Global value: the market was worth USD 8,848.9 million in 2025 and is projected to reach USD 16,994.0 million in 2034, reflecting a 7.5% CAGR as cloud clusters and fibre-access operators expand their optical distribution networks.
- Fiber optic connectors held the largest type position at an estimated ~34% of 2025 revenue; repeatable mating performance, low reflection and high fibre-count density keep connector assemblies essential across access, transport and server interconnects.
- Communication networks represented ~55% of 2025 applications, ahead of data centres at ~28% and enterprise IT at ~17%; the data-centre category has the faster modeled trajectory as AI infrastructure uses denser fibre distribution.
- Asia-Pacific accounted for an estimated ~42% of the global market in 2025, supported by optical-component manufacturing in China and Japan and substantial fibre deployments in major Asian economies.
- Commercial tension: higher channel density supports premium wavelength-management components, but passive-component suppliers face stringent insertion-loss tolerances, connector standardisation and aggressive volume pricing in access networks.
Optical Passive Device Market Overview
Optical passive device market was valued at USD 8,848.9 million in 2025 and is expected to reach USD 16,994.0 million by 2034, advancing at a 7.5% CAGR during 2025–2034. Asia-Pacific was the largest regional market in the base year with an estimated ~42% share, reflecting its substantial optical manufacturing footprint and installed communications infrastructure.
Passive optical devices route, connect, separate, attenuate and protect light without performing the electrical-to-optical conversion of an active transceiver. The product boundary includes finished fibre optic connectors ,couplers and splitters, wavelength-division multiplexers, attenuators and isolators sold into telecommunications, enterprise information technology and data-centre infrastructure. Silica-based optical paths dominate the revenue mix, while plastic housings and specialist materials serve distinct cost and packaging requirements. Fibre cable sold on its own, powered switches, laser chips and network service subscriptions fall outside the finished-device market.
Physical-layer upgrades are changing the specification of the passive bill of materials. In metropolitan transport, a dense wavelength-division multiplexer must maintain spectral separation while adding little insertion loss; in a large cloud cluster, a multi-fibre connector must fit more fibres into constrained front-panel space. Both demands favour tighter process control and improved packaging rather than merely more units. Suppliers with established fibre alignment, coating and optical testing capabilities can defend pricing in these demanding categories, whereas standard access connectors face stronger competition from high-volume manufacturers.
The application mix links two different investment cycles. Communications service providers remain the largest purchasers because access, aggregation and long-haul fibre systems require repeated connections, splitting and wavelength routing at multiple points in a network. Cloud service providers purchase fewer outdoor access splitters but increasingly complex high-density assemblies, fibre arrays and wavelength-management components for AI-oriented infrastructure. Enterprises and public agencies add demand through campus fibre, secure networks and modernisation projects, although these purchases typically follow slower facilities budgets.
Product selection depends on measurable optical penalties rather than headline bandwidth alone. Connector end-face geometry, return loss, insertion loss, polarisation-dependent loss, isolation and thermal stability determine whether a device can be used in a high-capacity optical link. Coherent lists compact isolators for O-, C- and L-band applications and thin-film filters for 200, 100 and 50 GHz channel spacing. These specifications illustrate why premium passive devices often require more sophisticated coating, assembly and reliability testing than commodity patch-cord connectors.
The industry is moving toward compact, modular fibre management in both data centres and metro networks. Corning announced a May 2025 collaboration supplying connector and fibre-array infrastructure for Broadcom co-packaged optics, demonstrating the need to deliver many optical paths to a densely integrated switching system. The active switching silicon is not passive-device revenue; detachable fibre interfaces and passive distribution assemblies are. This distinction matters when comparing optical networking announcements with the much narrower addressable sales of finished passive components.
Segment Analysis: By Type
By type, five groups shape the passive optical device market: Fiber Optic Connector, Fiber Optic Coupler, Optical Wavelength Division Multiplexer, Optical Attenuator and Optical Isolator. Connector products led with an estimated ~34% of 2025 revenue; couplers accounted for ~22%, multiplexers ~20%, attenuators ~14% and isolators ~10%. Multiplexers have the highest modeled growth rate, at ~9.4% CAGR, because dense fibre transport requires more wavelength channels per installed strand.
| Device type | Optical role and engineering requirements | Commercial position and demand outlook |
|---|---|---|
| Fiber Optic Connector | A connector provides a detachable optical junction between a fibre, transceiver interface, distribution panel or equipment enclosure. Low insertion loss requires accurately aligned ferrules, polished end faces and controlled mating pressure; repeatability matters because installers may reconnect a fibre several times during maintenance. High-density multifibre formats support cloud switching racks, while standard LC and SC interfaces remain common in telecommunications access and enterprise patching environments. | Largest type, ~34% of 2025 revenue, ~7.1% modeled CAGR. Connector sales benefit from the number of fibre terminations rather than the data rate of an individual optical channel. Corning’s MMC high-density connectivity initiatives illustrate a move toward more fibres per unit of panel space, while access-network procurement continues to favour standardised and price-competitive assemblies. Suppliers differentiate through factory termination yield, contamination control, return-loss performance and documented reliability under repeated mating. |
| Fiber Optic Coupler | A coupler or splitter distributes optical power between branches or combines paths without requiring a powered signal-processing stage. Planar lightwave circuit splitters support passive optical networks, whereas fused-fibre couplers and specialty tap couplers are selected for monitoring and measurement. Designers must balance insertion loss, split uniformity, wavelength range and environmental stability; a splitter deployed in an outside-plant cabinet may remain in service across multiple generations of access equipment. | ~22% share and ~7.2% modeled CAGR. Telecom access networks account for much of the installed volume because a single feeder fibre can be distributed to many premises. Operators extending full fibre in Europe and Asia require splitters at distribution points, but standard ratios and competitive manufacturing limit pricing power. Higher-quality specialty couplers serve optical monitoring, submarine systems and demanding instrumentation, where traceability and stable loss across operating temperatures carry more weight than minimum unit price. |
| Optical Wavelength Division Multiplexer | A wavelength-division multiplexer combines or separates distinct optical carriers so several services can share one physical fibre. Coarse WDM modules typically use broad wavelength channels; dense WDM filters and interleavers operate with narrower spectral separation and stricter passband requirements. The optical filter stack must keep adjacent-channel isolation high without imposing unacceptable insertion loss, making precision coating, packaging stress and thermal drift central manufacturing considerations. | ~20% share and fastest modeled growth, ~9.4% CAGR. More channels per fibre allow network owners to expand transport capacity without pulling new cable through constrained routes. Coherent markets passive CWDM modules with thin-film filter architectures, and Lumentum offers wavelength-management systems for flexible transport. The modeled growth premium reflects higher component value in metro upgrades and cloud interconnect, while the segment faces specification pressure as channel spacing narrows and optical budgets tighten. |
| Optical Attenuator | An attenuator intentionally reduces optical power to keep a receiver within its operating range and to balance channels in a wavelength-multiplexed link. Fixed units are common in patch panels and test setups; variable optical attenuation is used in channel equalisation and network maintenance. Device selection turns on calibration repeatability, return loss, wavelength flatness and power-handling limits, particularly when many channels share amplifiers or monitoring infrastructure. | ~14% share with ~6.3% modeled CAGR. Attenuator purchases rise as networks add optical channels and operators fine-tune signal levels during commissioning. Commodity fixed units are readily substitutable, but precision devices retain value in long-haul and laboratory applications. Suppliers can capture more revenue by integrating attenuation with monitoring or compact filter functions, provided the passive revenue boundary excludes powered control electronics sold as separate systems. |
| Optical Isolator | An optical isolator allows forward light transmission while suppressing reflected energy that can destabilise a laser or create interference. Designs use magneto-optic and polarising elements, sometimes in miniature inline or receptacle packages. Coherent specifies options reaching 38 dB isolation in selected formats, demonstrating the performance trade-off among insertion loss, size, wavelength band and protection from return signals. Reliability is especially important when replacement requires equipment disassembly. | ~10% share and ~7.2% modeled CAGR. Demand is tied to the protection of optical sources in communications equipment and to higher-density integration that leaves less room for separate optical components. Advanced isolators carry a greater engineering content than basic connectors, but their revenue base is smaller because a system uses fewer units. Miniaturisation and stable operation over wide temperature ranges support premium applications in high-speed optical modules and specialised photonic assemblies. |
Secondary segmentation: End User and Material
The end-user axis distinguishes telecom service providers at ~49% of 2025 revenue, cloud service providers at ~26%, enterprises at ~17% and government organisations at ~8%. Telecom operators buy passive distribution devices throughout access and transport networks, while cloud buyers increasingly specify connector density and tight loss budgets in switch fabrics. Enterprise and public-sector installations have longer replacement intervals but can command higher reliability and documentation requirements in specialised deployments.
By material, silica-based optical constructions account for ~74% of modeled 2025 value, plastic-based formats represent ~18% and other specialised materials contribute ~8%. The distinction is not simply the housing composition: low-loss silica paths enable demanding transport systems, while polymers can reduce weight and manufacturing cost in selected connectors and short-reach assemblies. Advanced coating stacks, ferrule ceramics and hybrid packages are treated within the relevant finished-device category rather than as independent end markets.
Segment Analysis: By Application
By application, Communication remains the largest category with an estimated ~55% of 2025 revenue, followed by Data Center at ~28% and IT at ~17%. Communication infrastructure uses passive components in fibre access, metro aggregation and backbone transport. Data centres exhibit the fastest modeled growth at ~9.2% CAGR because high-density switching and co-packaged optics place a premium on precision fibre connectivity, even though active modules and silicon chips are excluded from this revenue boundary.
| Application | Demand characteristics |
|---|---|
| Communication | Largest application, ~55% of 2025 revenue, ~6.9% modeled CAGR. Fibre access requires splitters and connectors at distribution points, while metropolitan transport adds multiplexers, filters, isolators and channel balancing components. The United Kingdom’s full-fibre rollout provides a measurable demand backdrop: Ofcom reported availability to 20.7 million homes in December 2024. The component value is generated when network equipment makers and installers purchase finished passive optical assemblies, not when operators collect broadband subscription fees. |
| Data Center | ~28% share and ~9.2% modeled CAGR. Artificial intelligence clusters demand tightly packed fibre links, consistent connector insertion loss and reliable routing around dense switching hardware. Corning’s collaboration on Broadcom’s 51.2 Tb/s co-packaged optical switching platform is evidence of the interface challenge rather than a direct measure of this market’s sales. Purchases favour multifibre connector assemblies, fibre arrays and compact wavelength-routing components, while servers, active transceivers and network switching silicon remain outside the market total. |
| IT | ~17% share and ~6.5% modeled CAGR. Corporate campuses, hospitals, universities and industrial networks replace copper runs with fibre where distance, electrical isolation or bandwidth make optical links advantageous. Procurement usually combines patch panels, standard connectors, couplers and occasional wavelength-routing devices, with attention to ease of field service and compatibility with existing equipment. Smaller project sizes and longer refresh intervals constrain growth compared with hyperscale installations, but quality assurance and documented low-loss performance can sustain value. |
Applications differ in purchasing authority. Communications providers specify long operating lives and standard interfaces, data-centre designers focus on density and installation speed, and enterprise facilities teams prioritise serviceability. The resulting mix means a supplier may win access-network volumes without qualifying for high-density cloud assemblies. Conversely, a vendor that excels at fibre arrays can participate in AI infrastructure growth without becoming a meaningful supplier of outdoor splitters.
The regional and application axes should be read independently. A data-centre connector shipped into North America from a factory in Asia-Pacific belongs to the North American demand region but reflects Asian production capability. Likewise, a wavelength multiplexer used in a telecom backbone remains a communication application even when the operator also sells cloud connectivity. These distinctions avoid double-counting hardware across adjacent end markets and clarify why supplier manufacturing locations cannot be substituted for customer geography.
Regional Analysis
Asia-Pacific leads global passive optical component demand with an estimated ~42% share in 2025, followed by North America at ~32%, Europe at ~18%, Latin America at ~5% and the Middle East and Africa at ~3%. The regional split reflects where fibre infrastructure is installed and upgraded, not where suppliers are incorporated. Asia-Pacific also has the highest modeled growth at ~8.1% CAGR, supported by manufacturing depth, urban data-centre construction and access-network investment.
How do network architectures and infrastructure investment affect regional demand?
Network owners buy passive optical components at different stages of development. Fibre access construction creates demand for connectors and splitters, while mature networks replace older transport filters and add wavelength capacity without digging new cable routes. Data-centre growth adds another layer of dense fibre assemblies, particularly around switching clusters. Consequently, the relative value of multiplexers, isolators and connectors varies by geography even when operators use similar international optical standards and equipment suppliers.
Trade flows also shape supplier competition. Asian factories produce many low-cost optical components for buyers on other continents, but high-reliability products can be specified and qualified by network equipment manufacturers in the United States, Europe and Japan. Country-of-origin reviews, installation standards and local distribution affect market access. The regional revenue shares therefore refer to customer demand, while the manufacturing analysis separately identifies fabrication and assembly locations to prevent the same transaction being counted twice.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~42%) | Fastest (~8.1% CAGR) | Fibre rollout and cloud expansion | Precision optics at scale; regional supply chains |
| North America | Second (~32%) | Strong (~7.2% CAGR) | Hyperscale data centres and backbone upgrades | High-density connector qualification and delivery |
| Europe | Third (~18%) | Steady (~6.8% CAGR) | FTTH completion and transport modernisation | Low-loss specifications and sustainable installation |
| Latin America | Emerging (~5%) | Growth (~7.4% CAGR) | Urban fibre coverage and access competition | Price, import logistics and distributor support |
| Middle East & Africa | Developing (~3%) | Moderate (~7.0% CAGR) | National digital infrastructure programmes | Environmental reliability and project delivery |
Optical Passive Device Manufacturers and Competitive Landscape
Competition combines large photonics suppliers with specialist component makers and integrated optical equipment groups. Coherent, Lumentum, Accelink, Hengtong, O-Net, NEL and other suppliers address different parts of the passive device value chain. Coherent is the successor to II-VI, while NeoPhotonics was acquired by Lumentum; these names are not counted as independent current competitors. Market positioning depends on optical performance, process yield, manufacturing scale and whether a supplier qualifies for high-density cloud or telecom transport programmes.
Coherent offers a broad catalog of filters, isolators, attenuators, circulators and other passive products, giving equipment manufacturers options across several optical bands. Its isolator specifications illustrate the importance of return-loss protection and low insertion loss when components are packaged near sensitive laser sources. Lumentum focuses heavily on wavelength-management technologies for advanced transport systems; some of its integrated platforms contain active controls, so only qualifying passive component revenue belongs in this market boundary. Comparing entire corporate sales would substantially overstate either company’s position in finished passive devices.
Asian suppliers compete strongly in volume optical connectivity and in specialist photonic subassemblies. Hengtong’s fibre infrastructure position supports distribution relationships, while Accelink and O-Net have optical component and communications equipment expertise. Japanese specialists such as NEL participate in precision photonic technologies. A company that supplies fibre cable, optical transceivers or silicon photonic chips is not automatically a leading passive-device manufacturer; the relevant test is whether it sells connectors, couplers, multiplexers, attenuation components or isolators into the defined applications.
Customer qualification is an important competitive barrier. An operator or equipment maker may require a component to pass optical loss, vibration, humidity and temperature testing before deployment in a multi-year platform. A lower-cost substitute can require expensive retesting and introduce service risk, particularly in dense wavelength networks where several channels share one fibre. Established suppliers therefore defend premium niches through documentation and repeatability, while standard connectors and splitters remain vulnerable to price competition and tender consolidation.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Global photonics | Coherent Corp.; Lumentum | Broad wavelength-management and passive component portfolios, extensive optical engineering, high-reliability qualification and established relationships with major equipment manufacturers. Their integrated active product lines are adjacent businesses and must not be conflated with the narrower passive component opportunity. |
| Integrated Asian suppliers | Accelink Technologies; Hengtong Group; O-Net Communications | High-volume manufacturing and regional customer access support connectors, couplers and optical subsystem sales. Competitive advantage depends on production yield, ability to customise optical specifications, distribution economics and compatibility with international network equipment platforms. |
| Specialist engineering | NEL; CoAdna Photonics and other specialist vendors | Precision optical processing, compact wavelength management and customer-specific assemblies can command value where ordinary catalog parts do not meet loss, size or reliability requirements. Scale is smaller but qualification creates customer switching costs. |
Key companies profiled
- Coherent Corp. (formerly II-VI)
- Lumentum Holdings (includes acquired NeoPhotonics)
- Accelink Technologies
- Hengtong Group
- O-Net Communications
- NEL
- CoAdna Photonics
- Corning Incorporated
Optical Passive Device Production and Supply Analysis
Manufacturing combines precision glass or polymer processing, optical coating, fibre alignment, connector termination and environmental testing. The simplest connectors can be produced at high volume with standard tooling, whereas dense WDM filters and miniaturised isolators require tighter tolerances and specialised process controls. Asia-Pacific hosts a substantial share of assembly capacity, but supplier qualification and final purchasing decisions are distributed across telecommunications and cloud equipment makers worldwide.
Connector production begins with fibre preparation, ferrule or array alignment, end-face finishing and measurement of insertion and return loss. High-density assemblies add complexity because a small mechanical error can affect many fibres simultaneously, creating rework and inspection costs. Automation can improve throughput, but the quality of raw fibre, ferrule geometry and connector cleanliness remains important. Manufacturers serving cloud customers must also provide consistent traceability and packaging suitable for rapid deployment into large switching racks.
Wavelength-routing devices rely on thin-film coatings, diffraction structures or planar waveguide fabrication to separate optical channels. Coherent describes passive CWDM modules built from cascaded thin-film filters with high temperature stability. Related component specifications include 50, 100 and 200 GHz filter spacing, 1270–1610 nm operating wavelength options, isolation exceeding 30 dB and insertion loss below 0.6 dB for one connectorised isolator family. Another isolator family offers 20 or 38 dB isolation with 80 or 250 µm fibre. These device-specific specifications are not industry averages. In these products, the manufacturing challenge is not merely producing a working prototype; it is holding spectral centre wavelength, isolation and loss specifications across many units and temperature cycles. Suppliers with stable coating recipes and controlled packaging processes can capture more value than firms assembling standard connector housings.
The supply chain includes glass and optical substrates, coating materials, ferrules, magnets for isolators, specialty adhesives, packaging hardware and precision test equipment. Component vendors then sell to optical module makers, network equipment manufacturers, fibre installers and system integrators. Purchasing cycles vary by customer: cloud infrastructure buyers may need rapid ramps, while telecom carriers can demand long qualification periods and multiyear spare-part support. Manufacturing location matters for lead time and trade risk, but product qualification remains the decisive constraint for premium applications.
Optical Passive Device Market Dynamics, Drivers, Restraints and Opportunities
Growth reflects the continuing need to connect, distribute and manage more optical channels in communications and cloud networks. Fibre-to-the-premises expansion provides a broad volume base, while denser data-centre interconnect and wavelength management raise the value of selected precision devices. These drivers are offset by standard-product price pressure, demanding qualification requirements and deployment delays. The contribution model below allocates the net annual growth rate across specific positive and negative forces without treating adjacent network spending as passive-component revenue.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Cloud and AI data-centre fibre density | High | +3.10% | High | High | High |
| Fibre access and distribution expansion | High | +2.80% | High | Medium | Medium |
| Metro and long-haul wavelength upgrades | Medium-High | +2.20% | Medium | High | High |
| Precision component miniaturisation | Medium | +1.40% | Medium | Medium | High |
| Enterprise and public fibre modernisation | Low-Medium | +0.90% | Medium | Medium | Low |
| Others (resilience, testing and specialist photonics) | Low | +0.60% | Low | Medium | Medium |
Dense optical connectivity for AI computing
Data-centre architectures place many fibres close to switches, accelerators and optical engines, increasing demand for compact connectors and fibre arrays. The Corning and Broadcom collaboration announced in May 2025 demonstrates a design in which passive interfaces connect to co-packaged optical engines. Higher density creates a commercial premium for precise alignment, low loss and installation efficiency. This is distinct from the sale of active switches or transceivers, whose much larger equipment values are not included in the passive-device revenue boundary.
Full-fibre access networks add passive distribution points
Operators building fibre access must install optical splitters, connectors and termination hardware between central offices and premises. The UK regulator’s 2024 coverage statistics show how many households can be reached by such networks, but coverage is only a demand indicator rather than a device-sales measure. Once installed, these networks generate additional purchases through customer activations, network repairs and upgrades. Standardisation supports large volumes while keeping the average selling price of commodity components under pressure.
Wavelength upgrades extract more capacity from existing fibre
Metro and backbone operators can raise transmission capacity by adding channels rather than constructing an entirely new cable route. This increases demand for multiplexers, filters, interleavers and optical channel management components that meet stricter spectral specifications. Coherent’s catalog includes filters for 50, 100 and 200 GHz spacing, demonstrating the precision required as channel density increases. Component suppliers gain where customers value lower insertion loss and stable channel isolation more than minimum initial purchase price.
Miniaturisation makes optical assemblies more valuable
As packaging space shrinks, designers seek smaller isolators, connector arrays and combined optical functions that retain stable performance. A miniature device must still survive thermal and mechanical stress, which raises the importance of assembly yield and inspection. Coherent’s compact isolator portfolio illustrates the move toward tighter footprints without sacrificing isolation. Suppliers capable of integrating several passive functions into reliable assemblies can increase their content per system even if the number of installed optical links rises more slowly.
Public and enterprise networks broaden the buyer base
Industrial campuses, hospitals, research institutions and government facilities install fibre where distance, electrical isolation and service resilience are important. These customers usually purchase through systems integrators and prioritise compatible connectors, documentation and maintenance support. Demand is less concentrated than hyperscale cloud spending and often depends on facilities budgets, but it provides a stable market for tested optical distribution products. Specialist applications can justify premium components where downtime would be costly.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Commodity connector and splitter price erosion | High | -1.70% | High | High | Medium |
| Optical loss and reliability qualification costs | Medium-High | -0.90% | High | Medium | Medium |
| Network construction and capex delays | Medium | -0.60% | Medium | Medium | Low |
| Others (trade friction and material bottlenecks) | Low | -0.30% | Medium | Low | Low |
Standard-product prices compress supplier margins
Basic connectors and splitters are widely available from multiple qualified factories, and network tenders reward scale and consistent delivery. Price reductions can absorb much of the value created by higher unit volumes, especially when customers purchase standardised components for mass access deployment. Manufacturers with poor assembly yield or expensive manual inspection struggle to compete. The pressure is less severe for premium wavelength filters and compact isolators, where optical performance and qualification restrict substitution.
Tight loss budgets increase the cost of qualification
A component with excessive insertion loss can reduce system margin and trigger a network failure even if it looks mechanically compatible. Dense optical systems also need reliable return loss, isolation and thermal stability, forcing manufacturers to invest in precision test equipment and extensive environmental qualification. These costs can delay product launches and disadvantage smaller suppliers. The same barriers, however, protect successful vendors once their products are designed into a platform with a long operating life.
Capital spending can postpone optical infrastructure orders
Passive devices are purchased when operators or cloud builders install and upgrade equipment, not merely when traffic rises. Civil engineering delays, data-centre construction schedules and uncertainty over network investment can shift orders between quarters. A planned fibre access route may need regulatory approval before any splitters are installed, while a cloud campus can delay connector purchases until switching hardware is ready. Suppliers therefore face demand volatility despite a favourable long-term growth outlook.
Material and logistics risks affect component availability
Optical components require specialised glass, coatings, ferrules, magnets and precise packaging materials. Disruptions in these inputs can constrain yield or lengthen lead times, especially for devices qualified to a narrow specification. Trade friction and origin checks add complexity for globally distributed production. Customers can reduce exposure through alternate qualified suppliers, but the requalification process itself consumes engineering time and may require fresh optical and environmental testing.
MARKET OPPORTUNITIES
Detachable fibre interfaces for co-packaged optics
Co-packaged architectures move optical engines close to switch silicon and create a need for precise, serviceable fibre connections. Corning and GlobalFoundries announced work on detachable glass-waveguide interfaces in September 2025, illustrating the engineering direction. Suppliers can participate through connector arrays, passive couplers and fibre management components without manufacturing the active photonic chip. Commercial success depends on repeatable assembly, low loss and a practical service model for dense equipment.
Integrated wavelength management in metropolitan transport
Transport networks can expand spectral capacity by combining compact multiplexers with filters, attenuation and monitoring interfaces. Manufacturers that offer low-loss modules with predictable channel characteristics can simplify equipment design and reduce field tuning. The opportunity is strongest where operators have limited spare fibre and need to extract more capacity from existing routes. Passive-device value remains separate from powered wavelength-selective switches and network control software.
Low-loss multi-fibre assemblies for faster installation
Large data-centre and enterprise deployments consume substantial technician time in connector preparation and verification. Factory-terminated high-density assemblies can reduce field handling and make optical loss more predictable, supporting a value proposition beyond component price. Suppliers that document end-face quality and connector cleanliness can win contracts where installation speed is critical. Compatibility with common panel formats and robust mechanical designs will determine whether premium assemblies achieve broad adoption.
Specialised components for resilient optical networks
Power-grid communications, secure public networks and industrial systems often require reliable fibre links in demanding environments. Compact isolators, rugged connectors and carefully calibrated attenuators can improve system resilience without requiring a full network redesign. These opportunities are smaller than telecom access or hyperscale cloud, but buyers may accept higher unit prices for documented reliability and long replacement intervals. Vendors need application-specific testing rather than generic marketing claims to capture this demand.
Optical Passive Device Value Chain and Procurement
Value moves from optical materials and precision components through coating, fibre alignment and finished-device assembly to equipment makers and network installers. Commodity access products compete on cost and delivery, while specialised filters and isolators command value through process know-how. The purchasing chain is influenced by system-level qualification: a network equipment manufacturer may select the passive part, even though a telecom operator or cloud provider ultimately funds the infrastructure.
Upstream materials. Silica fibre and glass substrates provide low-loss optical paths, while ferrules and coatings determine alignment and spectral behaviour. Small dimensional variations can affect connector performance or the wavelength response of a filter. Suppliers therefore need dependable material quality and metrology, not only access to inexpensive inputs. Specialist magnetic and polarising elements also influence isolator performance, creating supply constraints that differ from those of ordinary fibre termination hardware.
Manufacturing. The factory combines polishing, alignment, coating and packaging with optical measurements that confirm each product meets its specified loss and stability. In high-density assemblies, a single defect can affect several fibres and increase rework costs. Automation improves repeatability for standard connectors, but advanced wavelength-management products still depend on sophisticated calibration and environmental testing. Quality yield is a major determinant of gross margin, particularly when customers impose strict acceptance thresholds.
Commercial channels. Equipment makers often qualify passive devices as part of a transport or access platform, while installers and distributors supply replacement connectors and splitters. Cloud infrastructure buyers may work directly with assembly specialists to design fibre arrays around specific switch layouts. Each channel values different capabilities: equipment makers require documentation, installers need available stock and compatible tooling, and cloud integrators demand fast production ramps with consistent performance.
End users. Telecommunications operators remain the broadest buyers because passive distribution exists at many points in their networks. Cloud providers represent a faster-growing, more concentrated channel with high engineering requirements. Enterprises and public organisations purchase smaller volumes but often need long service lives and dependable local support. Supplier strategies that distinguish these buying patterns are better positioned than those treating every optical component as interchangeable across applications.
Recent Developments in the Optical Passive Device Market
- 16 September 2025 Demonstrated
Coherent announced a new wire-grid polarizer designed for optical isolators in high-speed data-communications transceivers. Its demonstration achieved a 50 dB extinction ratio and 98.5% efficiency, illustrating how specialised passive optical elements can support compact, high-performance interfaces. The device was undergoing reliability testing, so the announcement demonstrates technology progress rather than an established volume revenue contribution. Source - 29 September 2025 Collaborated
Corning and GlobalFoundries announced development of detachable glass-waveguide fibre connector solutions for the GF Fotonix silicon photonics platform. The partners described edge-coupled and vertically coupled approaches intended to connect photonic chips to optical fibres with high precision. These passive interfaces may improve serviceability and fibre density in co-packaged optics, although the associated active chip and switch values remain outside this market. Source - 22 May 2025 Deployed
Adtran announced that Netomnia deployed a commercial 50G PON service in the United Kingdom over existing infrastructure. Faster access equipment can increase the need for carefully specified passive splitting and optical connections without replacing every distribution fibre. The event indicates a potential upgrade path for existing networks, but it is not a direct disclosure of connector or splitter revenue and should not be interpreted as a market sales figure. Source - 27 March 2025 Recognised
Adtran reported two FTTH innovation awards for 50G PON and deep PON assurance and fibre monitoring technology. These developments illustrate operators’ interest in extending the useful life and observability of optical access infrastructure. Passive splitters and termination devices remain part of the physical path, while the monitoring electronics and access platforms are adjacent equipment categories rather than passive component revenue. Source - 27 March 2025 Launched
Corning introduced GlassWorks AI connectivity solutions aimed at simplifying optical infrastructure for artificial intelligence data centres. The programme included high-density connector and fibre management offerings intended to accelerate installation and support demanding network layouts. The relevant passive opportunity consists of fibre interfaces and connector assemblies; the total capital expenditure on data-centre servers, switching electronics and buildings is not included in this category. Source - 31 March 2025 Showcased
At the optical fibre communications exhibition, Corning demonstrated high-density optical connectivity and co-packaged optics concepts, including MMC connector assemblies and bend-resilient fibre solutions. The presentations highlighted the need to combine many low-loss fibre paths in compact infrastructure. Commercial adoption depends on customer qualification, assembly yield and interoperability, rather than simply on the maximum theoretical bandwidth of the attached active system. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2025–2034 |
| Historical Period | 2021–2024 |
| Market Size 2025 | USD 8,848.9 million |
| Market Size 2026 | USD 9,514.4 million |
| Market Size 2034 | USD 16,994.0 million |
| Growth Rate | CAGR of 7.5% from 2025–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By End User, By Material and By Region |
| By Type | Fiber Optic Connector · Fiber Optic Coupler · Optical Wavelength Division Multiplexer · Optical Attenuator · Optical Isolator |
| By Application | IT · Communication · Data Center |
| By End User | Telecom Service Providers · Enterprises · Government Organizations · Cloud Service Providers |
| By Material | Silica-based · Plastic · Others |
| By Region | Each region analysed by Type, Application and Country North AmericaUnited States, Canada, Mexico EuropeUnited Kingdom, Germany, France, Nordics, Rest of Europe Asia-PacificChina, Japan, India, South Korea, Southeast Asia Latin AmericaBrazil, Mexico, Chile, Colombia, Rest of Latin America Middle East & AfricaSaudi Arabia, UAE, South Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Coherent Corp., Lumentum, Accelink Technologies, Hengtong Group, O-Net Communications, NEL, CoAdna Photonics, Corning Incorporated |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the global size of the optical passive device market?
The global optical passive device market was valued at USD 8,848.9 million in 2025 and is projected to reach USD 16,994.0 million in 2034, a 7.5% CAGR over the period. Growth reflects fibre access installations, optical transport capacity upgrades and denser connectivity for cloud infrastructure. The total covers finished passive components, not optical transceiver electronics or the entire spending on network construction.
What devices are included in the market?
The 5 device families cover fibre optic connectors, couplers or splitters, wavelength-division multiplexers, optical attenuators and isolators. Each performs an optical routing, coupling, power-control or protection function without generating the optical signal itself. The scope excludes active transceivers, lasers, powered optical switches, standalone cable sales and network services, which have different revenue boundaries and purchasing economics.
Which device type contributes the largest revenue share?
Fibre optic connectors hold an estimated ~34% of the 2025 type mix because almost every fibre system needs detachable terminations at equipment, panels and distribution points. Couplers follow at ~22%, multiplexers at ~20%, attenuators at ~14% and isolators at ~10%. Multiplexers are modeled to grow faster than the connector category as operators add more optical channels to installed fibre routes.
Which applications use passive optical components most heavily?
Communication networks represent ~55% of the 2025 application split, including access distribution, metro transport and backbone systems. Data centres contribute ~28% and enterprise IT another ~17%. Cloud facilities are a particularly attractive growth channel because denser optical switching increases the value of precision connector arrays, although the switching hardware and transceivers attached to those assemblies are separate products.
Which geographic market is the largest?
Asia-Pacific leads with an estimated ~42% of 2025 revenue and a modeled ~8.1% annual growth rate. It combines major fibre networks with a deep optical manufacturing ecosystem in China and precision engineering capabilities in Japan. North America is the next largest customer market at ~32%, with strong demand from hyperscale data centres and communications operators that qualify high-reliability passive assemblies.
How do optical multiplexers create network value?
A wavelength-division multiplexer lets several optical channels share one fibre by separating their wavelengths at the receiving end. This can expand transport capacity without installing another long-distance cable route. High-quality filters must maintain channel isolation, low insertion loss and stable passbands as spacing narrows. The economic benefit is strongest where civil construction is expensive and existing fibre routes are already constrained.
What limits growth in passive optical components?
Commodity connector and splitter pricing is highly competitive, while premium components require expensive optical testing and long qualification cycles. Installation delays can shift orders even when traffic continues to rise. Component qualification also requires thermal cycling, calibrated optical measurements and repeatable alignment under mechanical stress. These risks make production yield, supplier diversity and after-sales support important alongside the underlying demand for additional optical capacity.
How does artificial intelligence infrastructure affect demand?
AI computing clusters use dense switching fabrics that need many low-loss fibre interfaces, particularly when optical engines sit close to high-bandwidth switching chips. Passive fibre arrays and connector assemblies become important for packaging and serviceability. The opportunity should not be confused with revenue from GPUs, optical transceivers or switching silicon; it is the narrower hardware content used to connect and route optical paths.
Which companies compete in this market?
Relevant suppliers include Coherent, Lumentum, Accelink, Hengtong, O-Net, NEL, CoAdna Photonics and Corning in overlapping passive connectivity and photonic component categories. The competitive field spans high-volume access hardware and specialised wavelength management. Former II-VI operations are now part of Coherent, and NeoPhotonics belongs to Lumentum, so those legacy names should not be counted as separate independent companies.
What segmentation and geography are covered?
The study covers five device types, three application groups, four end-user classes and three material categories across Asia-Pacific, North America, Europe, Latin America and the Middle East and Africa. It uses 2025 as the base year, 2026 as the estimate and 2034 as the terminal forecast. Regional demand is assigned to the customer location rather than to the country where a component was manufactured.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF