Key Statistics
Key Takeaways
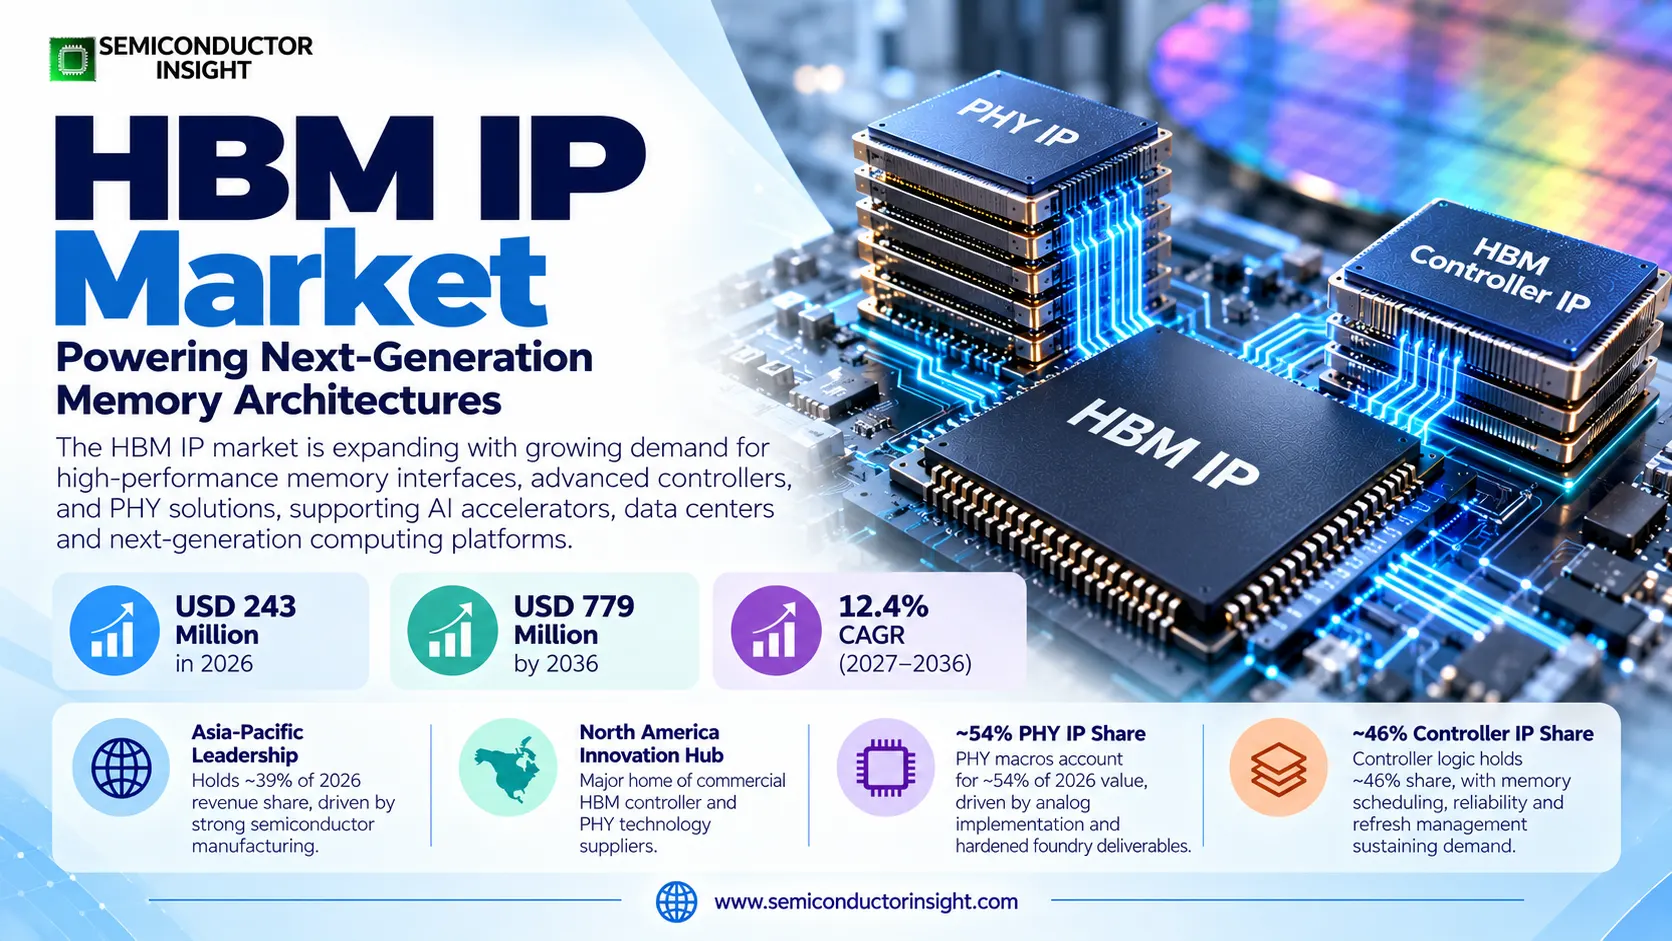
- Market trajectory: Global HBM interface intellectual property licensing and associated engineering revenue is valued at USD 243 million in 2026 and is projected to reach USD 779 million in 2036, representing a 12.4% annual expansion over the 2027–2036 planning horizon. The growth scenario follows controller and physical-layer design requirements, not sales of memory stacks.
- PHY IP: Physical-layer macros represent an estimated ~54% of 2026 HBM IP revenue. Hard PHY design requires analog signal-integrity engineering, advanced foundry characterization and silicon validation, which support premium licensing and integration work as HBM4 expands the interface to 2,048 data bits.
- Servers: Server platforms contribute an estimated ~62% of 2026 application revenue, ahead of Internet infrastructure and other uses. AI training accelerators and HPC systems increasingly require dedicated HBM controllers and PHYs to connect multiple stacked-memory devices within 2.5D and 3D packages.
- Regional position: Asia-Pacific leads with an estimated ~39% share in 2026, closely followed by North America at ~37%. The distinction reflects where licensing and integration value is assigned; Taiwan and South Korea are key manufacturing and packaging locations while United States vendors supply much of the commercial IP.
- Commercial constraints: Interface qualification at 12.8 Gbps, 16 Gbps and beyond increases validation spending, yet complex advanced packaging, limited foundry-portable PHY implementations and customer-specific license negotiations constrain the pace at which new designs turn into recognized IP revenue.
HBM IP Market Overview
HBM IP market was valued at USD 243 million in 2026 and is projected to reach USD 779 million by 2036, at a CAGR of 12.4% during 2027–2036. Asia-Pacific holds the largest modeled 2026 revenue share at ~39%, while North America remains a major home of commercial controller and PHY technology suppliers.
HBM interface IP comprises reusable controller logic and physical-layer circuitry licensed to designers of processors, accelerators, networking chips and custom silicon. The controller schedules commands, refreshes DRAM, manages errors and arbitrates competing data streams, while the PHY handles high-speed electrical signaling, timing, training and repair. Both blocks must operate with memory stacks and interposer routes selected for a particular package. Commercial revenue therefore arises from technology licenses, integration engineering and contract support rather than the selling price of HBM devices or completed compute boards.
Physical design requirements have changed sharply across memory generations. Synopsys documents a 1,024-bit HBM3 PHY with 16 independent 64-bit channels, while its HBM4 PHY uses a 2,048-bit interface with 32 independent channels and a DFI 5.1-compatible controller connection. That widening raises the number of pins and the amount of verification needed per interface, making PHY selection an early architectural decision. HBM4 controller variants may be placed alongside the processor or integrated into a customized base die.
Commercial suppliers differentiate their offerings through validated foundry process nodes, interoperability testing, reliability features and engineering support. Cadence introduced an HBM4 controller-and-PHY solution rated at 12.8 Gbps per pin in April 2025, with a hardened PHY targeted at TSMC N3 and N2 nodes. Rambus launched HBM4 controller IP in September 2024 and announced HBM4E controller IP in March 2026 supporting up to 16 Gbps per pin. These announcements demonstrate product availability, but not a disclosed worldwide licensing-revenue total.
Asia-Pacific accounts for an estimated ~39% of the modeled licensing and implementation value, driven by semiconductor integration programs in Taiwan, South Korea, China and Japan. North America follows at ~37%, reflecting the design centers and commercial IP licensors that serve accelerator makers. Europe represents ~14%, with smaller modeled shares in South America and the Middle East and Africa. These allocations are analyst estimates of a narrow technology-licensing market; semiconductor sales or HBM manufacturing capacity should not be interpreted as equivalent IP revenue.
The underlying industry provides a favorable demand backdrop but also a clear measurement boundary. The Semiconductor Industry Association reported worldwide semiconductor sales of USD 791.7 billion for 2025, including large logic and memory categories, yet those values encompass finished devices and are not directly comparable with IP royalties. HBM design wins are concentrated in long qualification cycles and revenue may be recognized through upfront licenses, customization milestones and support arrangements. Design delays, customer consolidation and changes in packaging strategy can therefore create uneven annual cash receipts even when underlying bandwidth requirements continue to rise.
Segment Analysis: By Type
By Type, HBM IP comprises PHY IP and HBM Controller IP. PHY macros hold an estimated ~54% share of 2026 value, reflecting analog implementation, hardened foundry deliverables and post-silicon characterization. Controller logic accounts for an estimated ~46%, with memory scheduling, reliability, refresh management and custom base-die architecture sustaining demand as HBM4 and HBM4E become more complex.
| Type | Technical function | Market position |
|---|---|---|
| PHY IP | The physical layer addresses 2,048-bit HBM4 I/O, channel calibration, clock distribution and interface training. In 2026, procurement decisions also depend on process-node hardening and silicon characterization. The practical constraint for the physical layer is sensitivity to interposer routing, power integrity and foundry qualification. For the physical layer, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The the physical layer business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. | The PHY category addresses high-speed analog circuitry with layout-dependent performance. In 2026, procurement decisions also depend on multi-year hard-macro support and validated interoperability. The practical constraint for the phy category is the expense of porting analog blocks across nodes; modeled share ~54% in 2026. For the phy category, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The the phy category business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
| HBM Controller IP | Digital memory controllers addresses command scheduling, refresh, ECC, pseudo-channel arbitration and DFI protocol logic. In 2026, procurement decisions also depend on configurable RTL, verification IP and accelerator architecture integration. The practical constraint for digital memory controllers is customer-specific command policies and changing HBM standards. For digital memory controllers, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The digital memory controllers business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. | Controller licensing addresses soft RTL reusable across multiple SoC implementations. In 2026, procurement decisions also depend on licensing flexibility and optional base-die placement. The practical constraint for controller licensing is complex memory traffic patterns and increasing RAS requirements; modeled share ~46% in 2026. For controller licensing, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The controller licensing business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
PHY IP
Hard PHY implementations addresses analog timing margins, I/O arrays and package-aware training. In 2026, procurement decisions also depend on Synopsys HBM4 and Cadence HBM4 product characterization. The practical constraint for hard phy implementations is silicon revisions and costly process migrations. For hard phy implementations, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The hard phy implementations business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Physical-layer vendors addresses DFI 5.1, 32 channels and 2,048 data lines in HBM4. In 2026, procurement decisions also depend on tested interfaces at 12.8 Gbps and process-specific support. The practical constraint for physical-layer vendors is variation in interposer topology and thermal conditions. For physical-layer vendors, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The physical-layer vendors business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
HBM Controller IP
Digital controller architectures addresses memory transaction arbitration, refresh management and end-to-end data protection. In 2026, procurement decisions also depend on Rambus HBM4E and Synopsys HBM4/4E product options. The practical constraint for digital controller architectures is compatibility with customer PHY choices and base-die logic. For digital controller architectures, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The digital controller architectures business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Controller economics addresses licensable RTL, verification and custom scheduling. In 2026, procurement decisions also depend on integration milestones and design reuse across accelerator generations. The practical constraint for controller economics is limited addressable customer count and bespoke qualification. For controller economics, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The controller economics business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Segment Analysis: By Application
The original application taxonomy covers Servers, Internet and Others. Servers account for an estimated ~62% of HBM IP revenue in 2026 as AI accelerators and high-performance computing devices integrate multiple stacked-memory channels. Internet infrastructure contributes an estimated ~24%, and other graphics, research and specialized computing designs contribute the remaining ~14%.
| Application | Demand characteristics |
|---|---|
| Servers | Server accelerators addresses large transformer training batches and bandwidth-sensitive inference. In 2026, procurement decisions also depend on integrated HBM4 PHY and controller subsystem qualifications. The practical constraint for server accelerators is rapid changes in accelerator package architecture; estimated ~62% of 2026 value. For server accelerators, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The server accelerators business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
| Internet | Network infrastructure processors addresses high-throughput packet buffering, AI-assisted networking and switch ASIC workloads. In 2026, procurement decisions also depend on predictable latency and energy per transferred bit. The practical constraint for network infrastructure processors is cost pressure and alternatives based on conventional DRAM; estimated ~24% of 2026 value. For network infrastructure processors, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The network infrastructure processors business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
| Others | Specialized graphics and scientific systems addresses simulation, rendering and instrumentation with intensive data movement. In 2026, procurement decisions also depend on design-specific memory interface blocks and long service lifecycles. The practical constraint for specialized graphics and scientific systems is smaller project volumes and long approval cycles; estimated ~14% of 2026 value. For specialized graphics and scientific systems, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The specialized graphics and scientific systems business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
Server-oriented design wins often require simultaneous qualification of memory controller RTL, hardened PHY macros and package routing. A controller that can operate with HBM4 devices at 10 Gbps per pin may still need adaptation to an accelerator with multiple stacks and complex scheduling policies. The economic result is a combination of license fees and engineering milestones. Network ASICs and specialist processors use similar technology but have different memory capacity, latency and bill-of-material priorities, making their revenue profile less closely tied to large AI training deployments.
Application demand must be measured at the interface IP level. The number of deployed AI servers, the selling price of a graphics processor and the revenue of a memory manufacturer are all useful indicators of design activity, but none is a direct substitute for a controller or PHY license. A single reusable block may support several product revisions, while a bespoke hard macro may require a new contract for a process migration. This distinction explains why application shares are modeled rather than assigned from accelerator shipments.
Regional Analysis
Regional allocations follow HBM interface IP licensing, customer engineering and package implementation activity rather than memory wafer output. Asia-Pacific is modeled at ~39% in 2026, North America at ~37%, Europe at ~14%, South America at ~5% and the Middle East and Africa at ~5%. Growth rates differ according to advanced packaging adoption, domestic custom silicon capability and availability of process-qualified PHY macros.
Which region is expected to lead HBM IP licensing and integration?
Asia-Pacific is the modeled leader at ~39% of 2026 revenue, followed closely by North America at ~37%. The Asia-Pacific allocation emphasizes Taiwan and South Korean foundry, memory and packaging collaboration, while North America reflects major controller and PHY licensors and accelerator architecture teams. Europe at ~14% is more specialist, with South America and the Middle East and Africa at ~5% each. None of these shares is presented as a disclosed audited national revenue statistic.
Growth rates also differ: Asia-Pacific is assigned ~13.8% annual expansion, North America ~12.2%, Europe ~10.8%, South America ~9.3% and the Middle East and Africa a higher scenario of ~8.1%. These rates reflect expected adoption of HBM4/4E interface solutions, but each region still faces foundry-specific qualification and licensing timing uncertainty. A 2025 tape-out may create revenue in a different year from a 2026 hardware launch, and geographic contract ownership can differ from the physical location of packaging.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | ~39% modeled | ~13.8% CAGR | Foundry and packaging ecosystems | Foundry qualification and advanced packaging |
| North America | ~37% modeled | ~12.2% CAGR | AI accelerator architecture | Licensor and SoC design-center relationships |
| Europe | ~14% modeled | ~10.8% CAGR | HPC and networking design | Long qualification cycles and reliability |
| South America | ~5% modeled | ~9.3% CAGR | Scientific computing projects | International licensor access |
| Middle East & Africa | ~5% modeled | ~8.1% CAGR | AI compute investment | Partner-led custom silicon projects |
HBM IP Competitive Landscape and Leading Technology Suppliers
HBM interface licensing is concentrated among a small group of global silicon IP providers with process-qualified PHY macros, advanced digital controllers and system-level validation capabilities. Synopsys, Cadence and Rambus document active HBM3, HBM4 or HBM4E solutions, while several additional companies appear in the original market company roster as ecosystem participants. Product availability does not by itself establish a specific supplier revenue share.
Synopsys supplies hard PHY and digital controller products across memory generations, including an HBM4 PHY with 2,048-bit data width and an HBM4/4E controller option that can be integrated into a customized memory base die. Cadence markets an HBM4 controller-and-PHY subsystem with verification and bring-up tools, and Rambus offers controller IP designed to interoperate with customer or third-party PHY technology. These differences matter commercially because customers may source the controller and physical layer from one vendor or negotiate separate licenses.
Foundry enablement can be as important as the headline bandwidth rating. Cadence targets TSMC N3 and N2 hard PHY implementations, while Synopsys has publicized HBM4 IP and advanced-node collaboration with TSMC. Customers consider foundry signoff, validated memory models, package routing and the cost of retesting an IP block on another process. A competitor with a nominally faster data rate may lose a design if its hard macro is not ready for the customer’s node or package schedule.
The publisher roster includes AMD, GUC, Broadcom and several specialist technology organizations in addition to the three established commercial interface IP suppliers. Some are primarily processor designers, ASIC service firms or broader semiconductor ecosystem participants, so inclusion in the roster should not be read as proof of merchant HBM PHY licensing revenue. Competitive tiers therefore distinguish directly documented interface IP products from integration partners and adjacent chip suppliers rather than inventing audited company market shares.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Synopsys, Cadence, Rambus | Established interface IP licensors addresses HBM3 and HBM4 controllers, PHY macros and interoperability tooling. In 2026, procurement decisions also depend on hard-macro qualification, RTL portability and silicon bring-up services. The practical constraint for established interface ip licensors is complex multi-vendor interoperability and custom base-die requirements. For established interface ip licensors, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The established interface ip licensors business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
| Tier 2 | GUC, MSquare Technology, Shanghai AkroStar Technology, INNOSILICON Technology | Specialist design ecosystem participants addresses ASIC integration, customer-specific memory subsystem engineering and related implementation services. In 2026, procurement decisions also depend on access to advanced foundry nodes and contract-specific design support. The practical constraint for specialist design ecosystem participants is limited public disclosure of independent HBM IP licensing revenue. For specialist design ecosystem participants, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The specialist design ecosystem participants business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
| Adjacent ecosystem | AMD, Broadcom, Shanghai UniVista Industrial Software Group | Processor and software ecosystem firms addresses accelerator platforms, semiconductor design tooling and broader integration activity. In 2026, procurement decisions also depend on qualification partnerships and architecture influence rather than merchant PHY revenue. The practical constraint for processor and software ecosystem firms is the risk of incorrectly treating processor sales or generic software as interface IP licensing. For processor and software ecosystem firms, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The processor and software ecosystem firms business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary. |
Key companies profiled
- AMD
- Synopsys
- GUC
- Broadcom
- Cadence
- Rambus
- MSquare Technology
- Shanghai UniVista Industrial Software Group
- Shanghai AkroStar Technology
- INNOSILICON Technology
HBM IP Design Capacity, Qualification and Commercial Delivery
Capacity in this market means engineering throughput and availability of validated intellectual-property implementations rather than wafer or DRAM stack output. Scarce capabilities include high-speed analog PHY design, advanced-node characterization, package signal-integrity simulation and controller verification. A 2026 customer program may need both a reusable RTL block and a process-specific hard macro, with revenue recognized through different licensing and support milestones.
PHY engineering capacity is constrained by process technology and silicon characterization. Synopsys documents an HBM4 PHY with 32 independent 64-bit channels, 2,048-bit interface width and support for data rates up to 12 Gbps per pin. Cadence markets a 12.8 Gbps HBM4 solution and provides lab bring-up software for post-silicon tuning. Delivering these products requires analog layout, clocking design, memory interface test structures and foundry-specific electrical models; hiring additional software developers alone cannot instantly expand validated hard-macro supply.
Controller development has a different resource profile. Digital teams create transaction schedulers, refresh logic, error correction, power-management functions and customer-specific arbitration policies. Rambus announced HBM4E controller IP supporting 16 Gbps per pin in March 2026, illustrating the continued need to update RTL as bandwidth and channel counts rise. Reusable controller designs can scale across several customer projects, but each new processor may require integration, verification and firmware-related customization that consumes engineering time.
Advanced packaging creates a third bottleneck. Synopsys and TSMC discussed HBM routing, through-silicon via planning and multi-die signoff in September 2025, while Synopsys and Samsung disclosed an HBM3 customer tape-out using I-CubeS technology in June 2025. These examples show why PHY and controller licensing decisions are made alongside interposer and package architecture. Delayed package signoff can defer recognized IP engineering revenue even when the underlying block is technically ready.
Commercial delivery can involve a one-time technology license, an engineering services agreement, maintenance and optional future process ports. A customer buying a 2026 hard PHY macro may request updates for 2027 silicon revisions and a separate 2028 migration to a new foundry node. That creates recurring engineering opportunity but also revenue timing variability. The modeled delivery mix allocates ~44% to hard PHY macro licenses, ~37% to soft controller RTL licenses and ~19% to customization and support, with no claim that vendors publish these categories separately.
HBM IP Market Dynamics: Drivers, Restraints and Growth Opportunities
Demand for HBM controller and PHY intellectual property is propelled by AI accelerator bandwidth requirements, the transition to HBM4/4E, growing 2.5D and 3D packaging complexity and customers seeking reusable verified subsystems. Offsetting forces include advanced-node qualification costs, concentrated buyer budgets, uncertain license recognition schedules and interface architecture fragmentation. The modeled impact analysis below reconciles positive and negative contributions to the forecast annual growth rate.
MARKET DRIVERS
Drivers Impact Analysis
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2027–2029 | 2030–2032 | 2033–2036 |
|---|---|---|---|---|---|
| AI accelerator memory bandwidth requirements | High | +4.80% | High | High | High |
| HBM4 and HBM4E interface generation upgrades | High | +3.90% | High | High | Medium |
| Advanced 2.5D and 3D package integration | Medium-High | +3.00% | High | High | High |
| Demand for reusable verified IP subsystems | Medium | +2.50% | Medium | High | High |
| Foundry process and custom base-die migration | Low-Medium | +1.70% | Medium | High | High |
| Others (specialized networking and scientific computing) | Low | +1.30% | Low | Medium | Medium |
AI accelerator bandwidth expansion
Artificial intelligence training and inference addresses repeated movement of model parameters and activations between compute engines and stacked DRAM. In 2026, procurement decisions also depend on controller scheduling and reliable multi-stack bandwidth delivery. The practical constraint for artificial intelligence training and inference is qualification of power and thermal behavior at full accelerator load. For artificial intelligence training and inference, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The artificial intelligence training and inference business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
HBM4 and HBM4E product migration
New HBM generations addresses 2,048-bit HBM4 interfaces and emerging 16 Gbps-per-pin HBM4E controller capability. In 2026, procurement decisions also depend on early design engagements for processor revisions planned several years ahead. The practical constraint for new hbm generations is rapid standard changes and revalidation of package electrical margins. For new hbm generations, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The new hbm generations business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Complex multi-die integration
Heterogeneous packages addresses memory PHY macros, interposer traces, base dies and compute chiplets. In 2026, procurement decisions also depend on foundry-certified design flows and joint signal-integrity analysis. The practical constraint for heterogeneous packages is yield sensitivity, routing congestion and cross-vendor design ownership. For heterogeneous packages, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The heterogeneous packages business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Reusable verified subsystems
Integrated controller-and-PHY offerings addresses complete interface operation from protocol to electrical layer. In 2026, procurement decisions also depend on shorter SoC integration schedules and coordinated post-silicon support. The practical constraint for integrated controller-and-phy offerings is licensing restrictions and mismatched validation versions. For integrated controller-and-phy offerings, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The integrated controller-and-phy offerings business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Foundry and base-die transitions
Advanced process migration addresses new hard-macro layouts, DFI revisions and controller placement alternatives. In 2026, procurement decisions also depend on customization services and long-term support agreements. The practical constraint for advanced process migration is non-portability of analog macros and rising mask costs. For advanced process migration, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The advanced process migration business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Other specialist workloads
Scientific and network processors addresses latency-sensitive data access in HPC and high-throughput ASICs. In 2026, procurement decisions also depend on small-volume custom interface licenses. The practical constraint for scientific and network processors is limited project budgets relative to hyperscale AI development. For scientific and network processors, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The scientific and network processors business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
MARKET RESTRAINTS
Restraints Impact Analysis
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2027–2029 | 2030–2032 | 2033–2036 |
|---|---|---|---|---|---|
| Advanced-node PHY qualification cost | High | -2.20% | High | High | Medium |
| Concentrated customer budgets and long design cycles | Medium-High | -1.30% | High | Medium | Medium |
| Interface architecture and packaging fragmentation | Medium | -0.90% | Medium | High | High |
| Others (royalty timing, integration rework and support burden) | Low | -0.40% | Medium | Medium | Low |
Costly silicon validation
PHY qualification addresses analog timing and power margins at 12 to 16 Gbps per pin. In 2026, procurement decisions also depend on silicon test vehicles and foundry-specific characterization. The practical constraint for phy qualification is expensive respins if signal integrity fails under production conditions. For phy qualification, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The phy qualification business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Few large license buyers
Customer concentration addresses a limited number of advanced AI accelerator and custom ASIC programs. In 2026, procurement decisions also depend on long negotiations and complex licensing rights. The practical constraint for customer concentration is budget postponements that can shift large contracts between fiscal years. For customer concentration, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The customer concentration business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Architecture fragmentation
Package diversity addresses different interposers, base-die architectures and PHY-controller partitioning. In 2026, procurement decisions also depend on customer-specific interfaces and verification plans. The practical constraint for package diversity is reduced reuse of hardened blocks across manufacturing platforms. For package diversity, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The package diversity business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Commercial timing and integration burden
Contract milestones addresses initial licenses, NRE support and later maintenance arrangements. In 2026, procurement decisions also depend on clear deliverables and interoperability responsibilities. The practical constraint for contract milestones is acceptance delays that can defer recognition without changing technical demand. For contract milestones, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The contract milestones business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
MARKET OPPORTUNITIES
HBM4E and future interface qualification
Early HBM4E design engagements addresses controllers supporting 16 Gbps per pin and broader multi-stack bandwidth. In 2026, procurement decisions also depend on pre-silicon design kits and interoperable PHY partnerships. The practical constraint for early hbm4e design engagements is customers choosing alternative physical implementation strategies. For early hbm4e design engagements, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The early hbm4e design engagements business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Custom base-die controller placement
HBM4 base-die architecture addresses movement of controller logic closer to memory through TSV PHY connections. In 2026, procurement decisions also depend on joint foundry, memory and accelerator engineering. The practical constraint for hbm4 base-die architecture is uncertain ownership of IP across compute and memory suppliers. For hbm4 base-die architecture, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The hbm4 base-die architecture business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Integrated test and bring-up services
Subsystem verification addresses DFI models, memory BIST, ECC testing and lab characterization. In 2026, procurement decisions also depend on recurring services beyond an initial IP license. The practical constraint for subsystem verification is project-specific engineering effort limiting gross margins. For subsystem verification, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The subsystem verification business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Regional foundry ecosystem expansion
Cross-border packaging partnerships addresses TSMC and Samsung advanced process enablement for AI designs. In 2026, procurement decisions also depend on multiple qualified IP implementations and local support teams. The practical constraint for cross-border packaging partnerships is geopolitical constraints and dependence on scarce packaging capacity. For cross-border packaging partnerships, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The cross-border packaging partnerships business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
HBM IP Licensing Value Chain and Integration Ecosystem
The HBM interface IP value chain starts with memory standards and architectural requirements, moves through controller RTL and hardened PHY development, and ends with foundry integration, packaging qualification and customer silicon bring-up. The licensed object is reusable design technology; the HBM DRAM device is an adjacent component. Commercial risk concentrates at the interfaces between independent vendors and at milestones that require a working packaged test chip.
Upstream standards. HBM specifications addresses interface width, channel timing, command behavior and electrical signaling requirements. In 2026, procurement decisions also depend on alignment among memory manufacturers, processor designers and IP vendors. The practical constraint for hbm specifications is standards evolving while silicon implementation is already underway. For hbm specifications, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The hbm specifications business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Technology development. Commercial IP suppliers addresses hardened analog PHY, digital controller RTL and protocol verification models. In 2026, procurement decisions also depend on licensing agreements, documentation and integration support. The practical constraint for commercial ip suppliers is validation of all combinations of process node and memory stack. For commercial ip suppliers, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The commercial ip suppliers business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Foundry implementation. Manufacturing partners addresses PHY layout integration, package routing, signal integrity and power integrity. In 2026, procurement decisions also depend on co-design of 2.5D interposers and custom base-die options. The practical constraint for manufacturing partners is timing closure and test-chip schedule changes across partners. For manufacturing partners, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The manufacturing partners business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Downstream users. Processor customers addresses AI accelerators, HPC processors and networking ASICs requiring stacked-memory interfaces. In 2026, procurement decisions also depend on production-qualified designs and post-silicon support. The practical constraint for processor customers is large program concentration and uncertain future design reuse. For processor customers, engineering teams balance silicon area, thermal headroom, timing closure, power consumption and the qualification work needed to bring a memory interface into production. The processor customers business earns contract value through licensed design deliverables and specialized support, while physical DRAM stack shipments remain outside its revenue boundary.
Recent Developments in HBM Controller and PHY IP
- 4 March 2026 Launched
Rambus introduced HBM4E Controller IP capable of operation up to 16 Gbps per pin, equivalent to 4.1 TB/s per memory device under the company’s specified interface configuration. The offering is available for licensing and can be paired with third-party PHY technology. This launch increases controller design choices for next-generation AI accelerators, while integration and electrical validation remain separate engineering responsibilities. Source - 18 April 2025 Launched
Cadence announced an HBM4 controller-and-PHY IP subsystem rated at 12.8 Gbps per pin and targeting TSMC N3 and N2 process nodes. Its package-aware test chip and lab bring-up tools address a critical obstacle to production deployment: proving interoperability across memory, PHY, controller and interposer. The commercial significance is stronger licensing differentiation through a prevalidated subsystem rather than a single digital or analog block. Source - 24 September 2025 Partnered
Synopsys and TSMC reported continued 3DIC and HBM routing collaboration supporting advanced multi-die designs and CoWoS packaging. Their work includes through-silicon via and bump planning, automated HBM routing and package signoff. The announcement highlights why memory interface IP is increasingly sold with implementation expertise, since package routing and signal integrity can determine whether an otherwise functional PHY reaches production. Source - 16 June 2025 Validated
Synopsys described an HBM3 customer design tape-out on Samsung Foundry SF2 technology with I-CubeS packaging and improved turnaround for 3D integration. The disclosure demonstrates progress in connecting high-speed memory interfaces to advanced process and packaging workflows. It is evidence of design activity, not a disclosed royalty amount or a direct measure of worldwide HBM IP revenue. Source - 23 April 2025 Expanded
Synopsys and TSMC announced advanced-node EDA and IP enablement that included HBM4 among high-bandwidth interface standards supported for next-generation chips. Their collaboration spans N2P and A16 process development and advanced packaging workflows. Availability of process-aware implementation tools reduces technical barriers for accelerator customers, but individual HBM PHY licensing agreements still depend on customer selection and qualification. Source - 9 September 2024 Introduced
Rambus announced HBM4 Memory Controller IP with support for the then-developing memory specification and potential operation up to 10 Gbps per pin. The controller can be paired with a customer or third-party PHY to create a complete subsystem. This modular approach increases sourcing flexibility for chip designers while making interface validation and responsibility allocation important parts of the commercial contract. Source - 25 October 2023 Upgraded
Rambus reported that its HBM3 Controller IP could support up to 9.6 Gbps per pin, a 50% increase over the initial 6.4 Gbps HBM3 data-rate baseline cited by the company. The announcement illustrated the speed at which controller technology must advance within a memory generation. Reusable RTL helps customers adopt faster memory, although package power and PHY capability may remain the limiting factors. Source - 6 February 2026 Reported
The Semiconductor Industry Association reported USD 791.7 billion in worldwide semiconductor sales for 2025, a 25.6% increase over 2024, with strong logic and memory demand. This broader industry result supports the investment backdrop for AI and memory interface design, but the figure includes finished chips and cannot be treated as the revenue of HBM controller or PHY licensors. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| Market Size 2026 | USD 243 million |
| Market Size 2027 | USD 273 million |
| Market Size 2036 | USD 779 million |
| Growth Rate | CAGR of 12.4% from 2027–2036 |
| Unit | Revenue (USD Million), licensable HBM interface IP and associated contract engineering |
| Segmentation | By Type, By Application, By Technology Generation, By Commercial Delivery, By Buyer Channel and By Region |
| By Type | PHY IP · HBM Controller IP |
| By Application | Servers · Internet · Others |
| By Technology Generation | HBM2/HBM2E IP · HBM3/HBM3E IP · HBM4/HBM4E IP |
| By Commercial Delivery | Hard PHY macro license · Soft controller RTL license · Customization and support |
| By Buyer Channel | AI accelerator design firms · Foundry and ASIC design partners · HPC and networking integrators |
| By Region | Regional analysis covers controller/PHY licensing and implementation value, with shares modeled for 2026. North AmericaUnited States · Canada · Mexico EuropeGermany · France · United Kingdom · Rest of Europe Asia-PacificTaiwan · South Korea · China · Japan · Rest of Asia-Pacific South AmericaBrazil · Argentina · Chile · Rest of South America Middle East & AfricaUnited Arab Emirates · Saudi Arabia · South Africa · Rest of Middle East and Africa |
| Key Companies Profiled | AMD · Synopsys · GUC · Broadcom · Cadence · Rambus · MSquare Technology · Shanghai UniVista Industrial Software Group · Shanghai AkroStar Technology · INNOSILICON Technology |
| Customization Scope | Generation-specific controller and PHY licensing, foundry-node qualification, commercial-delivery contracts, buyer channels and regional revenue allocation. |
Frequently Asked Questions
How large is the global HBM IP market in 2026?
The global market is valued at USD 243 million in 2026. This value covers licensable high-bandwidth-memory controller and PHY intellectual property together with closely associated integration contracts. It does not represent sales of HBM memory stacks, GPUs or complete servers. Vendor products demonstrate active licensing opportunities, while contract-level revenue remains less transparent than finished semiconductor shipments.
What is the HBM IP market forecast for 2036?
The market is projected to reach USD 779 million by 2036, reflecting a 12.4% growth scenario over the planning period. Demand is linked to HBM4 and HBM4E interfaces, complex AI accelerator memory subsystems and foundry-qualified PHY implementations. Annual realized royalties may differ because IP revenue is influenced by design milestones and the timing of custom engineering contracts.
Which HBM IP category leads by type?
PHY IP is the largest type with an estimated ~54% of 2026 revenue, compared with ~46% for HBM Controller IP. Hard PHY macros require process-specific analog design, high-speed timing characterization and silicon validation. Controller RTL is more portable but needs complex memory scheduling, reliability and refresh management. Both categories are complementary and often qualified as a subsystem.
Which application creates the most HBM IP demand?
Servers are the leading application, with an estimated ~62% of 2026 licensing and integration revenue. AI training and inference processors require high-throughput memory interfaces and frequently attach several HBM stacks. Internet infrastructure contributes an estimated ~24%, with specialized graphics and scientific computing in the remaining ~14%. These figures are modeled application allocations rather than measured vendor sales splits.
Which region has the largest HBM IP share?
Asia-Pacific leads with an estimated ~39% of 2026 value, narrowly ahead of North America at ~37%. Foundry and packaging integration in Taiwan and South Korea supports Asian demand, while United States design centers and IP licensors influence many commercial contracts. Europe accounts for an estimated ~14%, with smaller modeled allocations in South America and the Middle East and Africa.
What differentiates controller IP from PHY IP?
Controller IP is digital logic that schedules HBM transactions, manages refresh, coordinates error handling and supports performance priorities. PHY IP is the electrical interface that trains, transmits and receives high-speed signals across the package. A customer may license both blocks from one supplier or combine a controller with a different vendor’s PHY, making interoperability testing essential.
How does HBM4 change licensing requirements?
HBM4 expands the physical interface to 2,048 data bits and increases channel count, creating more demanding signal-integrity, packaging and validation tasks. Synopsys describes a 32-channel PHY, and Cadence has demonstrated a 12.8 Gbps HBM4 solution. The change encourages process-qualified hard macros and subsystem-level engineering services, but increases the cost and duration of customer qualification.
Who are the principal commercial HBM interface IP suppliers?
Synopsys, Cadence and Rambus publish direct HBM controller or PHY offerings across multiple memory generations. The wider ecosystem includes ASIC design firms, processor suppliers and semiconductor software organizations. Participation in the ecosystem should not be confused with documented merchant HBM IP sales. Procurement teams compare node support, tested interoperability, memory generation coverage, reliability features and licensing conditions.
What are the main barriers to adoption?
The most important constraints are advanced-node PHY qualification expense, concentration among a small number of high-end accelerator buyers and uncertainty around package integration schedules. A hardened analog macro may not transfer directly to another foundry process, while a digital controller can require substantial customer customization. These risks affect both engineering budgets and the timing of revenue recognition.
Does HBM IP market revenue include HBM DRAM devices?
No. The revenue boundary includes licensable controller and PHY design blocks and closely related integration or support work. It excludes physical HBM stacks, semiconductor wafer fabrication, graphics processors, AI servers and generic software licenses unrelated to the memory interface. This distinction is critical because the finished memory market is much larger than the specialized intellectual-property market.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF