Key Statistics
Key Takeaways
- Notebook PC programs represent the largest type because major global brands rely on large Asian ODM platforms for design engineering, procurement, system integration, production ramp and lifecycle management across mainstream, commercial, gaming and AI-enabled notebooks.
- Consumer electronics is the dominant application, while military and specialized programs form a smaller high-reliability niche that places greater weight on controlled configuration, security, traceability and long product availability.
- Asia Pacific is the structural manufacturing center because the leading supplier base is concentrated in Taiwan and China and major ODMs operate large production networks across China, Taiwan, Vietnam, Thailand and other Asian locations.
- AI PC refresh demand is changing notebook design requirements. Compal reported 2025 global notebook shipments of 202 million units and described enterprise refresh plus AI adoption as important growth drivers for the year.
- Geographic diversification is becoming a sourcing requirement. Compal is adding U.S. capacity in Texas and expanding Taiwan and Vietnam, while Quanta describes manufacturing sites spanning Taiwan, China, Thailand, Vietnam, the United States, Mexico and Germany.
Tablet and Notebook PC ODM and EMS Market Overview
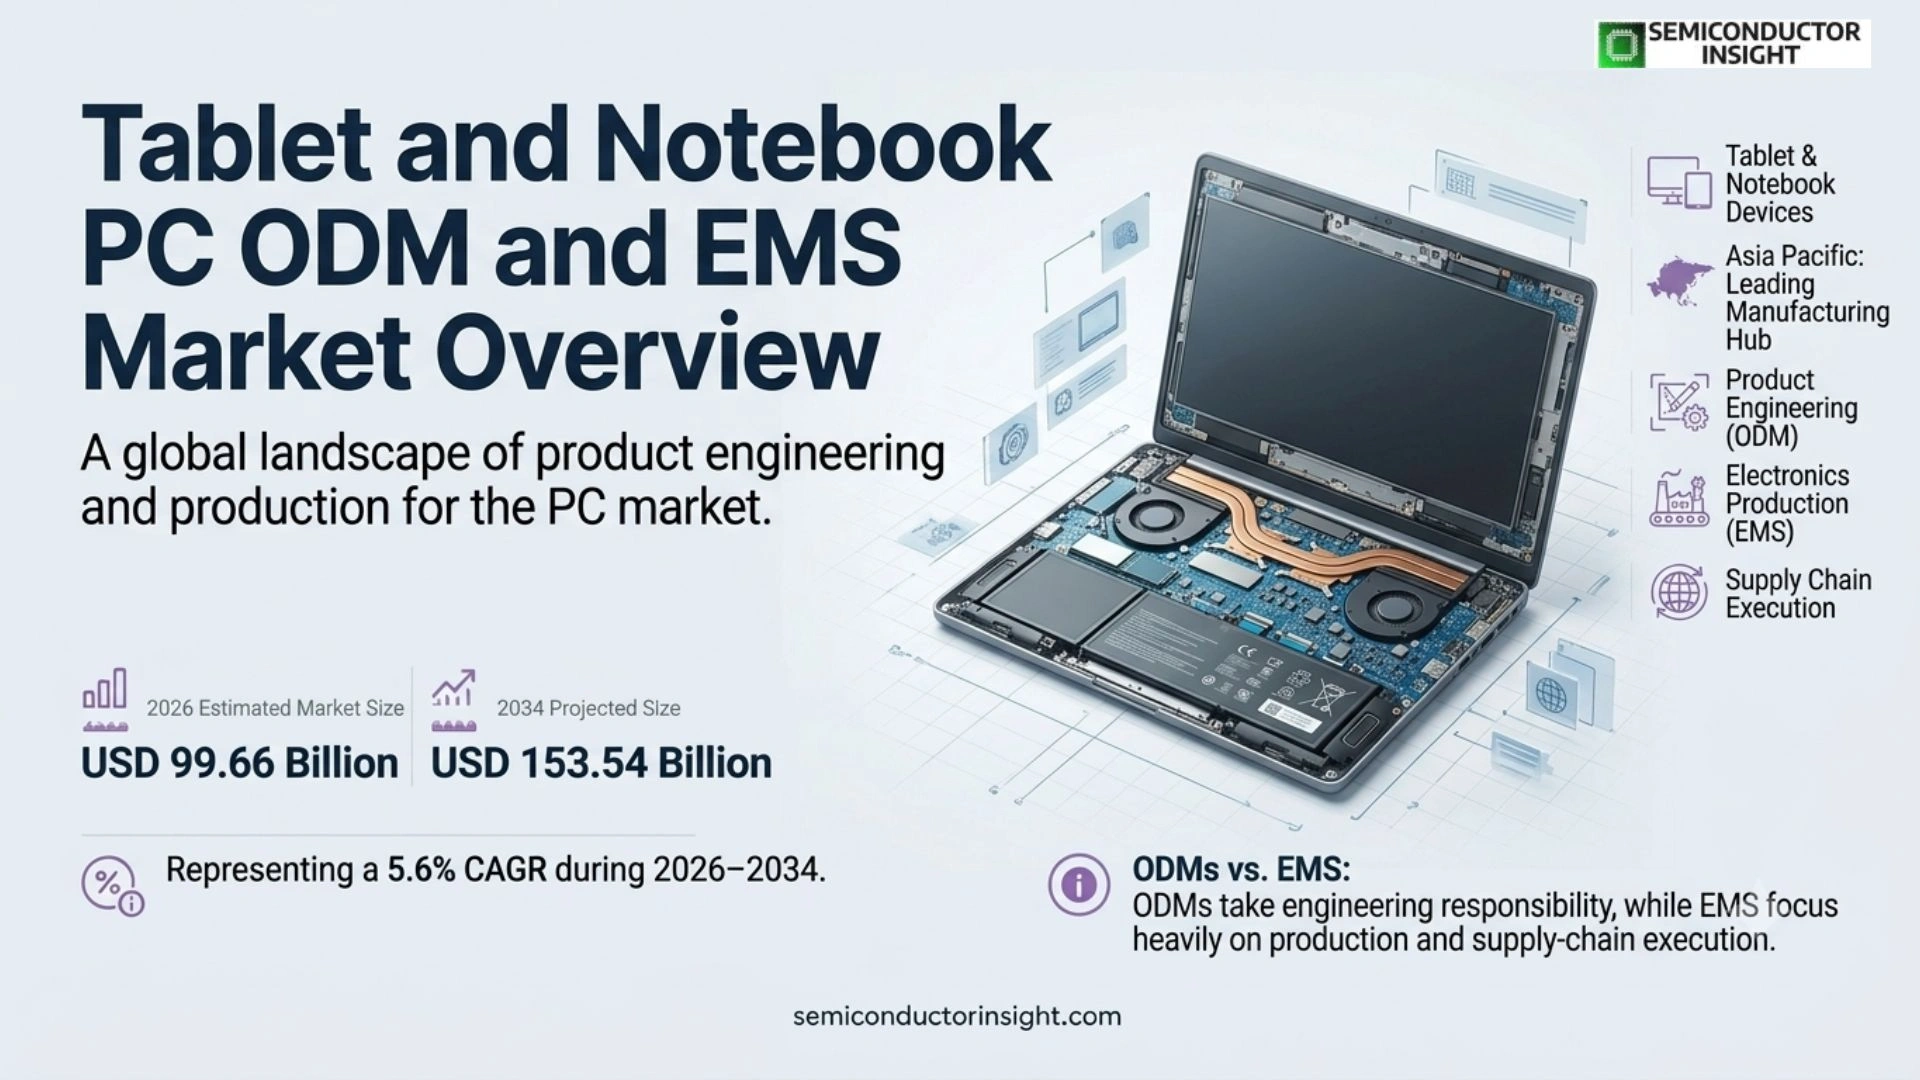
Tablet and Notebook PC ODM and EMS market is valued at USD 94.42 billion in 2025 and is projected to reach USD 153.54 billion by 2034, representing a 5.6% CAGR during 2026–2034. The 2026 estimated market size is USD 99.66 billion. Asia Pacific is the largest manufacturing market because the leading ODM and EMS supplier base is concentrated in Taiwan, China and the wider Asian electronics-production network.
Original design manufacturers take responsibility for substantial portions of product engineering and manufacturing on behalf of branded PC companies, while electronics manufacturing services providers focus more heavily on production, assembly, testing, sourcing and supply-chain execution. In practice the boundary can overlap: large contractors may contribute mechanical design, motherboard integration, thermal engineering, validation, procurement and final assembly within the same customer program.
The commercial model is driven by scale, yield, procurement leverage and the ability to ramp new products quickly. Notebook programs have short technology cycles tied to CPU, GPU, memory, display and wireless platform changes. A contractor that can coordinate hundreds of component suppliers, absorb late engineering changes and move volume among factories creates value beyond direct labor cost. This is why large ODM relationships remain concentrated among a relatively small group of established manufacturers.
AI PCs add another design cycle rather than replacing the outsourcing model. Lenovo reported that AI PC penetration reached 33% of its PC shipments in the second quarter of fiscal 2025/26, while Compal described enterprise refresh and AI adoption as major notebook-market drivers. For ODMs, the implication is higher engineering content around NPU-enabled boards, thermal design, memory, power management and premium form factors, together with renewed demand for rapid platform qualification.
Segment Analysis: By Type
By type, the market is segmented into Tablet and Notebook PC. Notebook programs form the larger commercial base because global PC brands outsource substantial product engineering and manufacturing to specialist ODMs, while tablets remain important in education, enterprise mobility, consumer entertainment and value-oriented computing.
| Type | Manufacturing requirements | Market position |
|---|---|---|
| Tablet | Tablet programs combine thin mechanical design, touch-display integration, battery packaging, camera modules, wireless connectivity and cost-sensitive final assembly. ODMs must coordinate display, enclosure and battery suppliers while maintaining tight weight, thermal and cosmetic targets across consumer, education and enterprise variants, making turnkey reference designs and fast customization important capabilities. | A meaningful but more price-sensitive segment. Demand can be concentrated around education refreshes, value consumer devices and specialized enterprise tablets. Supplier advantage comes from reusable design platforms, flexible order volumes and the ability to share processors, memory, wireless modules and mechanical components across several customer programs without sacrificing final-product differentiation. |
| Notebook PC | Notebook ODM work spans motherboard design, chassis engineering, thermal systems, display integration, firmware validation, supplier management and high-volume assembly. Product families range from entry notebooks and Chromebooks to gaming, commercial and AI PCs, creating a wide engineering and cost envelope that rewards experienced program management and fast new-product introduction. | Largest type. Compal’s annual reporting places global notebook shipments at 202 million units in 2025, while Quanta reported 45.9 million notebook shipments in 2024. Scale, platform engineering and customer qualification make notebooks the core volume business for major ODMs and provide repeated opportunities each processor and operating-system generation. |
ODM and EMS service boundary
ODM and EMS are different but overlapping service models rather than a separate product segmentation axis. ODM engagements can begin with product architecture and detailed engineering, whereas EMS engagements more often start with a customer-owned design and emphasize sourcing, assembly, test and logistics. Large suppliers increasingly provide both models, allowing brand customers to decide how much engineering responsibility to outsource by product family and geography.
| Service model | Typical responsibility | Commercial implication |
|---|---|---|
| ODM | Product design, engineering validation, sourcing, manufacturing, assembly and often lifecycle support under the brand customer’s specification framework. The contractor owns more of the design execution and must coordinate many technical decisions before the program enters mass production. | Higher engineering content and deeper platform integration can create stickier relationships, but the supplier also carries greater development risk, tooling coordination and program-management responsibility. Design reuse and engineering scale are therefore important to profitability. |
| EMS | Contract manufacturing, component sourcing, assembly, testing, packaging, logistics and related supply-chain services for customer-defined products. The contractor’s differentiation centers on manufacturing execution, quality systems and the ability to operate several factories under common process controls. | Competition emphasizes yield, cost, geographic footprint, delivery and the ability to rebalance production across sites when tariffs, logistics or customer demand change. Strong EMS execution can support long programs even when the customer retains most product design responsibility. |
Segment Analysis: By Application
By application, the market covers Consumer Electronics and Military. Consumer electronics is the largest application because notebooks and tablets are mass-market computing platforms, while military programs are smaller but require stronger configuration control, longer support periods, security review and ruggedization.
| Application | Demand characteristics |
|---|---|
| Consumer Electronics | Consumer and commercial PCs create the main outsourcing volume. Brand vendors use ODM and EMS partners to compress development time, leverage component purchasing scale and shift manufacturing among Asian and non-Asian plants. AI PCs, premium notebooks, gaming systems and education devices create differentiated programs, but all depend on disciplined cost, yield, quality and new-product-introduction execution throughout the product cycle. |
| Military | Military and government computing programs are smaller in unit volume but can require rugged design, secure supply chains, controlled firmware, extended product availability and country-specific sourcing. Contractors able to document component provenance and maintain stable configurations over longer lifecycles can compete on reliability and compliance rather than consumer-style price alone, creating a specialized higher-engineering niche. |
Regional Analysis
Asia Pacific is the manufacturing center of the Tablet and Notebook PC ODM and EMS market. Taiwan-headquartered Quanta, Compal, Wistron, Pegatron and Foxconn, together with China-based LCFC, Huaqin, Wingtech and other suppliers, anchor the ecosystem. North America and Europe are major end-demand and brand-management markets, while Mexico, Vietnam and Thailand are gaining manufacturing relevance as customers diversify production.
How is ODM and EMS activity distributed across the global tablet and notebook supply chain?
The manufacturing map is becoming more distributed without losing its Asian center of gravity. Quanta describes production sites spanning Taiwan, China, Thailand, Vietnam, the United States, Mexico and Germany. Compal is expanding Taiwan and Vietnam while preparing a Texas facility for mass production in the second half of 2026. This pattern reflects customer demand for resilient regional supply rather than a wholesale exit from the established Asian component ecosystem.
| Region | Market position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest manufacturing base | Moderate to high | ODM engineering and high-volume production | Scale, component proximity, engineering depth and manufacturing yield |
| North America | Largest brand/customer hub | Moderate | Demand, engineering and selective production | Tariff exposure, proximity to customers and resilient supply |
| Europe | Major commercial demand market | Moderate | Enterprise and premium devices | Product compliance, lifecycle support and logistics |
| South America | Emerging demand market | Selective | Consumer and education demand | Affordability, import structure and service coverage |
| Middle East & Africa | Emerging demand market | Selective | Government, education and consumer demand | Cost, channel support and regional availability |
Competitive Landscape
Competition is concentrated among large Asian ODM and EMS companies with long-standing relationships to global PC brands. Compal, Quanta, LCFC, Inventech, Wistron, Pegatron, Huaqin, Wingtech, Baolongda Group, Emdoordigi, Chuwi and Foxconn represent a supplier structure that spans global-scale notebook contractors, China-based design manufacturers and smaller value-device specialists. Competitive advantage comes from engineering depth, component purchasing scale, factory footprint, yield performance and fast production ramp.
Quanta and Compal illustrate the scale economics of the sector. Quanta reported 45.9 million notebook shipments in 2024 and a manufacturing network that spans Asia, North America and Europe. Compal reported 52.5 million 5C product shipments in 2025 and is expanding production in the United States, Taiwan and Vietnam. Large installed bases let these companies amortize engineering, automation and supplier-management capability across many programs.
The competitive structure is also changing as ODMs diversify beyond PCs. Compal raised the contribution of non-PC businesses in 2025, while Quanta has expanded deeply into AI servers. Diversification can improve margins and reduce PC-cycle exposure, but it also reallocates capital and engineering resources. PC customers therefore evaluate whether a contractor can preserve notebook execution while investing aggressively in higher-growth businesses.
China-based design manufacturers and smaller specialists compete through lower cost, faster reference designs and strength in value devices. Their opportunity is greatest in tablets, education devices and emerging-market notebooks where a complete turnkey platform can matter more than a decades-long relationship. Premium global brands still demand quality systems, secure sourcing, global service and financial capacity that favor larger incumbents.
Competitive tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Quanta; Compal; Wistron; Pegatron; Foxconn; LCFC | Large-scale notebook programs, global factories, major-brand relationships, deep engineering and procurement leverage. These suppliers can support several customer platforms simultaneously and move selected production among countries while maintaining common quality systems and program-management ownership. |
| Tier 2 | Huaqin; Wingtech; Inventech | Strong design-manufacturing capability, competitive cost structures and expanding customer portfolios. They can win value and mid-range programs by combining turnkey engineering with high-volume production, although the breadth of global customer relationships can differ from the largest incumbents. |
| Specialists | Baolongda Group; Emdoordigi; Chuwi | Value devices, smaller programs, specialized tablets and flexible turnkey designs. These suppliers can compete where customers value speed, lower development cost and smaller order quantities more than the full geographic footprint and financial scale of the leading notebook ODMs. |
Key companies profiled in the report scope
- Compal
- Quanta
- LCFC
- Inventech
- Wistron
- Pegatron
- Huaqin
- Wingtech
- Baolongda Group
- Emdoordigi
- Chuwi
- Foxconn
ODM/EMS Manufacturing Capacity & Footprint Analysis
Capacity in this market is measured less by a single factory’s theoretical unit output than by the ability to launch multiple models, secure components, control yield and shift production between sites. Leading ODMs are adding geographically diverse capacity because customers increasingly treat tariff exposure, logistics resilience and business continuity as part of the manufacturing specification.
Quanta describes manufacturing sites in Taiwan, China, Thailand, Vietnam, the United States, Mexico and Germany, while Compal is expanding Taiwan and Vietnam and preparing a Texas site for mass production in the second half of 2026. This does not mean Asia loses relevance. The deeper component and engineering ecosystem remains concentrated there, so new locations are most effective when linked back to established Asian supply and program-management networks.
Notebook production also requires synchronized capacity across displays, memory, SSDs, batteries, chassis, keyboards, power adapters and wireless modules. A final-assembly line can only operate at planned output when upstream allocations arrive on time. The commercial advantage of a large ODM is therefore its ability to coordinate multi-tier suppliers and reallocate scarce components across customer programs without breaking qualification requirements or delivery commitments.
Market Dynamics
Market growth is supported by AI-PC refresh demand, continued outsourcing by global brands and manufacturing-footprint diversification. The principal restraints are price pressure, short product cycles, component volatility and customer concentration. The strongest opportunities lie in AI-enabled premium notebooks, regional manufacturing and specialized tablet or notebook platforms that justify more engineering value per program.
MARKET DRIVERS
Drivers Impact Analysis*
| Factor | Forecast impact* | Geographic relevance | Impact timeline |
|---|---|---|---|
| Enterprise refresh and AI PC adoption | High | North America, Europe, Asia Pacific | Short to medium term |
| Brand outsourcing of engineering and manufacturing | High | Global | Persistent |
| Regionalized manufacturing footprints | Medium to high | Asia Pacific, North America | Medium term |
| Premium gaming and creator notebooks | Medium | North America, Asia Pacific, Europe | Medium term |
*Directional analytical rating used to compare market forces; it is not a measured contribution to the headline CAGR.
AI PC refresh creates a new platform cycle
AI PCs introduce NPU-enabled processors, new memory requirements, revised thermal profiles and premium software experiences. Lenovo reported AI PCs at 33% of its PC shipments in Q2 FY2025/26, while Compal identifies AI adoption and enterprise refresh as important notebook drivers. ODMs benefit because every platform transition creates new engineering, validation, tooling and production-ramp work.
Outsourcing lets brands focus capital on products and channels
Global PC brands avoid duplicating large manufacturing networks by using specialist ODM and EMS partners for engineering, procurement and assembly. The contractor spreads factories and supplier relationships across several customers, which can lower unit cost and accelerate new-product introduction. The model remains attractive as long as contractors maintain confidentiality, quality and reliable delivery across highly seasonal demand.
Geographic diversification has become a customer requirement
Tariffs, geopolitical risk and pandemic-era disruptions changed sourcing priorities. Compal’s Texas investment and parallel Taiwan and Vietnam expansion show how suppliers are building optionality. Customers gain a way to shift future programs among regions while keeping the same engineering partner, which can reduce the cost and risk of redesigning the supply chain after a disruption.
Premium notebooks increase engineering value per unit
Gaming, creator, enterprise and AI notebooks use higher-power processors, advanced cooling, high-refresh displays and denser batteries. These products require stronger co-design between brand and ODM and can support better economics than commodity entry systems. Contractors with thermal, mechanical and motherboard engineering depth can capture more program value even when overall unit growth remains modest.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Factor | Forecast impact* | Geographic relevance | Impact timeline |
|---|---|---|---|
| Brand-driven pricing pressure | High | Global | Persistent |
| Short product lifecycles and inventory risk | High | Consumer markets | Persistent |
| Component and memory cost volatility | Medium to high | Global | Short to medium term |
| Customer concentration | Medium | Large ODM suppliers | Persistent |
*Directional analytical rating used to compare market forces; it is not a measured contribution to the headline CAGR.
Large customers retain substantial bargaining power
PC brands place large volumes with a limited number of contractors and can benchmark pricing across suppliers. ODMs must continually improve automation, procurement and yield to protect margins. When components become cheaper, customers expect savings to flow through; when components become more expensive, contractors may face timing gaps before pricing can be adjusted.
Short product cycles increase execution risk
Notebook and tablet platforms change quickly around processor, GPU and display launches. A late production ramp can miss the strongest selling window, while excess inventory can lose value rapidly after a new platform arrives. ODMs therefore need disciplined forecasting, flexible labor and tight coordination with component suppliers during each new-product introduction.
Component volatility can disrupt healthy demand
Memory, storage, panels, batteries and semiconductor components can experience tight supply or abrupt price moves. Compal’s 2026 outlook highlights rising material costs and memory-supply fluctuations as pressures on traditional device markets. Contractors need procurement scale and customer agreements that allow them to manage allocation without absorbing all cost risk.
Diversification can compete for capital and engineering resources
Leading ODMs are investing in AI servers, automotive electronics, communications and medical systems because those markets can grow faster than PCs. The strategy reduces dependence on notebooks, but management must ensure that notebook engineering, automation and customer support remain strong. A contractor that underinvests in its core PC platforms can lose design wins even if the broader company is growing.
MARKET OPPORTUNITIES
Win higher-value AI notebook platforms
The strongest near-term opportunity is to become the primary design and manufacturing partner for AI notebooks rather than only an assembler. NPU-enabled architectures require coordinated motherboard, thermal, battery and firmware engineering. ODMs that shorten validation cycles and help brands differentiate premium products can capture more design content and improve the durability of customer relationships.
Use regional factories as a commercial differentiator
Customers increasingly want manufacturing options in more than one country. Contractors can package China, Vietnam, Thailand, Mexico and U.S. capacity as a single flexible network, allowing future programs to move without changing the engineering owner. The opportunity is strongest where suppliers standardize quality systems, test equipment and digital manufacturing data across sites.
Develop specialized tablets and rugged notebooks
Education, healthcare, industrial and field-service customers may need rugged enclosures, custom I/O, secure firmware or long support periods. These programs are smaller than mainstream consumer PCs but can carry more engineering content and less direct price competition. Smaller ODMs can use specialization to avoid competing only on scale with the largest notebook manufacturers.
Monetize sustainability and repairability engineering
Brands face increasing requirements around recycled materials, energy efficiency and product repairability. Quanta reports use of recycled plastics and metals in notebook products. ODMs that can quantify material traceability, design for disassembly and lifecycle carbon performance can turn compliance work into a differentiated engineering service rather than treating it as a documentation burden.
Tablet and Notebook PC ODM/EMS Supply Chain Analysis
Component allocation determines manufacturing flexibility
Notebook production depends on synchronized supply across high-value components with different lead times. ODMs with scale can negotiate allocations, validate alternate suppliers and rebalance components among customer programs. This procurement layer is a major source of economic value because a factory with open labor capacity still cannot ship if one critical display, memory or power component is missing.
Engineering converts a reference platform into a brand product
Processor vendors provide reference architectures, but branded notebooks still need chassis, cooling, acoustics, battery, antenna, display and firmware integration. ODM engineering teams perform this work repeatedly across sizes and price points. The ability to reuse proven design blocks without creating quality problems is one of the main reasons outsourcing can be faster than building every product internally.
Manufacturing excellence is measured by yield and ramp speed
High-volume production must deliver consistent cosmetic quality, electrical test performance and software configuration across many variants. New-product introduction is especially important because early yields are lower and customer demand is concentrated around launch windows. Digital manufacturing systems, automated inspection and disciplined corrective-action loops can materially improve program profitability.
Brands monetize the platform through segmentation and services
The same underlying ODM architecture can support consumer, gaming, enterprise or education models through different displays, memory, security features and software bundles. Brand customers create the final pricing and service model. ODMs benefit when their platform is reused across many SKUs because engineering investment is amortized across a larger volume base.
Recent Developments in the Tablet and Notebook PC ODM and EMS Market
Compal outlines notebook growth and manufacturing-footprint expansion
Compal’s 2025 annual report says global notebook shipments reached 202 million units in 2025 and identifies enterprise refresh plus AI adoption as key demand drivers. The company is also expanding Taiwan and Vietnam capacity and plans Texas mass production in the second half of 2026.
Lenovo reports strong full-year PC and AI performance
Lenovo reported a strong fiscal year and continued leadership in intelligent devices, reinforcing the platform refresh that drives new notebook design and manufacturing programs for ODM and EMS partners.
Quanta documents a diversified global manufacturing network
Quanta’s official sustainability disclosures describe manufacturing in Taiwan, China, Thailand, Vietnam, the United States, Mexico and Germany, while its 2024 notebook shipments reached 45.9 million units.
Lenovo AI PCs reach one-third of company PC shipments
Lenovo reported AI PCs at 33% of its PC shipments in the quarter, showing that NPU-enabled systems are becoming a mainstream product category rather than a small premium niche.
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2019–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2019–2025 |
| Market Size 2025 | USD 94.42 billion |
| Market Size 2034 | USD 153.54 billion |
| Growth Rate | CAGR of 5.6% from 2026–2034 |
| Unit | Value (USD Million/Billion) and device shipments where applicable |
| Segmentation | By Type, By Application, By Region |
| By Type | Tablet · Notebook PC |
| By Application | Consumer Electronics · Military |
| By Region | Each global region analysed by device type, application and country marketNorth AmericaUSA, Canada, MexicoEuropeGermany, UK, France, Russia, Italy, Rest of EuropeAsia PacificChina, Japan, South Korea, India, Southeast Asia, Rest of Asia PacificSouth AmericaBrazil, Argentina, Colombia, Rest of South AmericaMiddle East & AfricaSaudi Arabia, UAE, Egypt, Nigeria, South Africa, Rest of MEA |
| Key Companies Profiled | Compal · Quanta · LCFC · Inventech · Wistron · Pegatron · Huaqin · Wingtech · Baolongda Group · Emdoordigi · Chuwi · Foxconn |
| Customization Scope | Free report customization equivalent to up to four analyst working days with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the 2025 size of the Tablet and Notebook PC ODM and EMS market?
The market is valued at USD 94.42 billion in 2025 and is projected to reach USD 153.54 billion by 2034, representing a 5.6% CAGR during 2026–2034. The 2026 estimated market size is USD 99.66 billion. These values form the normalized production series used consistently throughout the overview and scope table.
Which type is the largest?
Notebook PC is the largest type because major global PC brands rely on specialist ODMs for substantial product engineering, sourcing, validation and high-volume assembly. Tablets remain an important outsourcing category, especially in education, value consumer and enterprise mobility, but notebook programs support a broader range of premium, gaming, commercial and AI-enabled platforms.
Which application leads the market?
Consumer electronics is the dominant application because tablets and notebooks are mass-market computing products sold through consumer, enterprise and education channels. Military programs are smaller but place greater value on ruggedization, configuration control, secure sourcing and long lifecycle support, which can support higher engineering content and more specialized supplier requirements.
Which region is the largest in 2025?
Asia Pacific is the largest manufacturing region in 2025 because the leading supplier base is concentrated in Taiwan and China and major ODMs operate extensive Asian factory networks. North America and Europe are major demand and brand-management centers, while production is also expanding in Vietnam, Thailand, Mexico and the United States.
What is the 2026 estimated market size?
The estimated market size for 2026 is USD 99.66 billion. The value is consistent with the growth path used between the 2025 base and 2034 forecast and is repeated throughout the Key Statistics, Market Overview, Report Scope and FAQ sections so that the publication uses one internally consistent forecast series.
What are the main growth drivers?
The main drivers are enterprise PC refresh, AI-PC platform adoption, continued outsourcing by global brands, premium notebook demand and manufacturing-footprint diversification. These forces create engineering and production work for ODMs even when overall PC unit growth is modest because each new platform requires design, validation, tooling, supplier qualification and production-ramp activity.
What are the main restraints?
The principal restraints are customer pricing pressure, short product lifecycles, component and memory-cost volatility, inventory risk and customer concentration. Large brands can benchmark multiple contractors, while ODMs must invest continuously in automation and engineering to protect margins and keep pace with rapid processor, display, memory and connectivity platform changes.
How is AI changing the ODM market?
AI PCs increase design complexity through NPU-enabled processors, new memory configurations, revised power and thermal requirements and premium software experiences. Lenovo reported AI PCs at 33% of its PC shipments in Q2 FY2025/26, and Compal described AI adoption as an important notebook-market driver, indicating a broad platform transition.
Why are ODMs expanding outside China?
Customers increasingly want manufacturing options that reduce tariff, logistics and geopolitical concentration. Compal is expanding the United States, Taiwan and Vietnam, while Quanta lists production across Asia, North America and Europe. Regional capacity gives customers flexibility, but it still depends on Asian engineering teams and component ecosystems for efficient new-product introduction.
What does the report cover?
The report covers tablets and notebook PCs, applications in consumer electronics and military markets, five global regions, country-level markets and the full profiled supplier list including Compal, Quanta, LCFC, Inventech, Wistron, Pegatron, Huaqin, Wingtech, Baolongda Group, Emdoordigi, Chuwi and Foxconn. The forecast window uses 2025 as base year, 2026 as estimated year and 2034 as forecast end year.
Research Sources & Evidence Base
View primary and authoritative evidence used in this overview
- Compal Electronics. 2025 Annual Report – Primary company filing covering notebook-market conditions, 2025 shipment trends, AI-PC demand and Compal’s manufacturing expansion.
- Quanta Computer. Sustainable Management – Company Profile and Market Overview – Official disclosure describing Quanta’s notebook business, global manufacturing sites and major export markets.
- Quanta Computer. Operations and Governance – Economic Performance – Official disclosure reporting 45.9 million notebook shipments in 2024 and supply-chain information.
- Lenovo. FY2025/26 full-year results – Official company results supporting strong PC demand, premium mix and AI-related growth.
- Lenovo. Q2 FY2025/26 results – Official company results reporting AI PCs at 33% of Lenovo PC shipments in the quarter.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF