Key Statistics
Key Takeaways
- SoC Test Solutions is a leading product category because it addresses the largest current application base.
- Automotive is a major application, with demand shaped by performance, reliability and system integration.
- Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
- Higher parallelism, ai/hpc test coverage and data-driven adaptive testing is the main technology direction influencing new design wins.
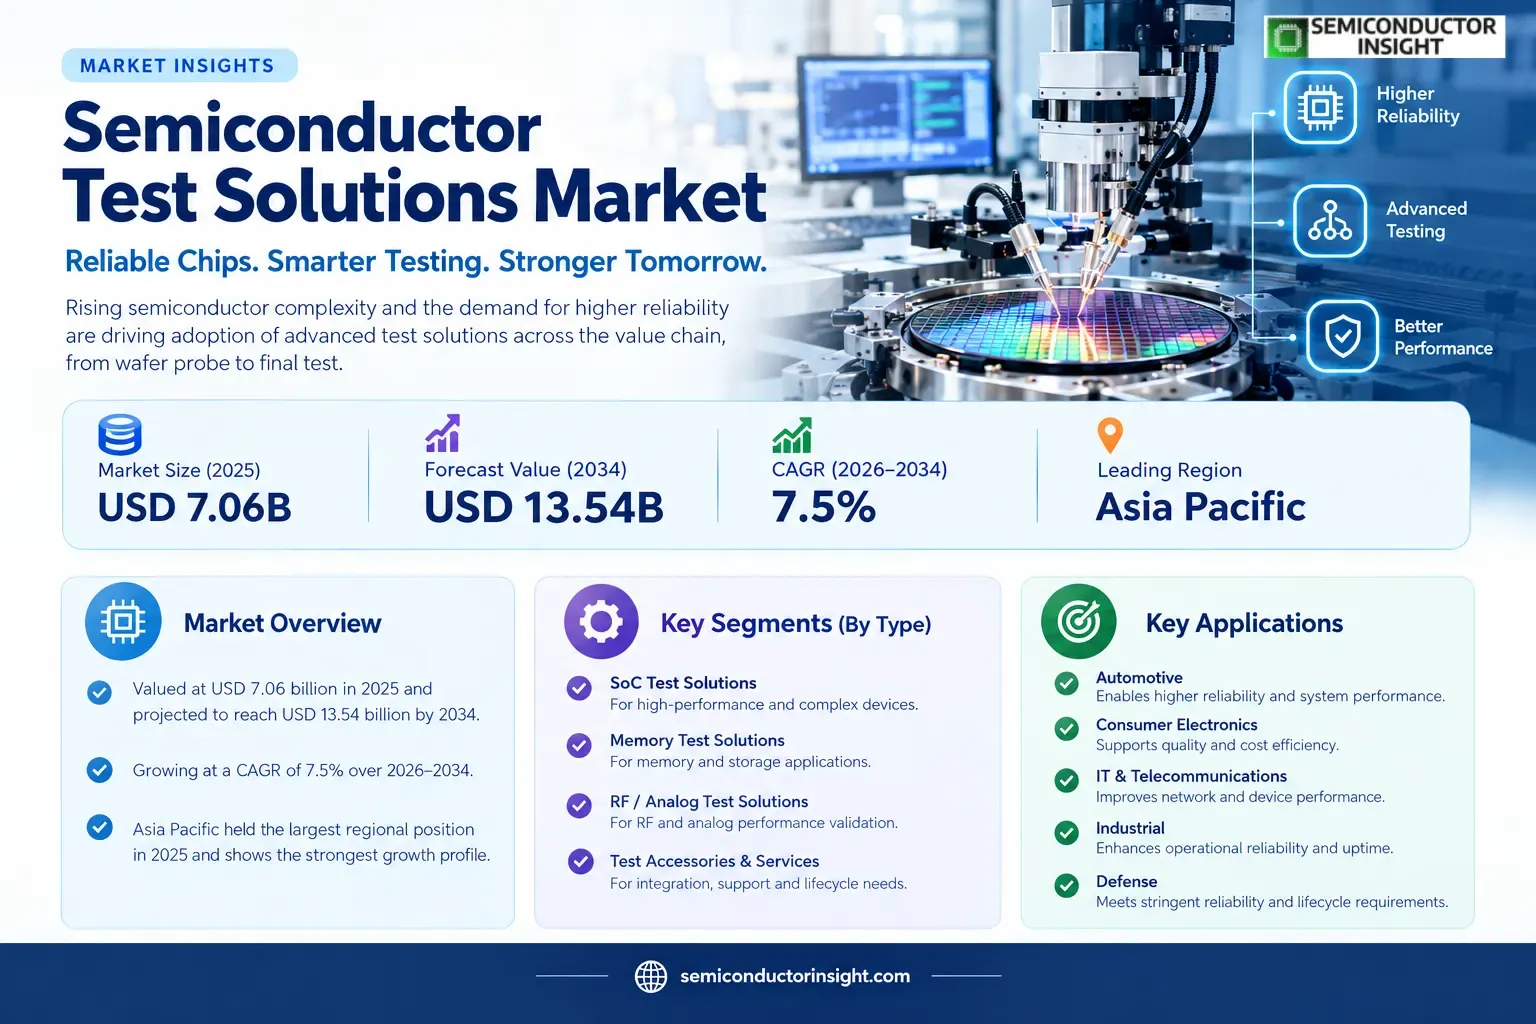
- Market size and growth: USD 7.06 billion in 2025 is projected to reach USD 13.54 billion by 2034 at a 7.5% CAGR during 2026–2034.
Semiconductor Test Solutions Market Overview
Test solutions market was valued at USD 7.06 billion in 2025 and is projected to reach USD 13.54 billion by 2034, growing at a CAGR of 7.5% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
Semiconductor test solutions combine automated test equipment, handlers, interfaces, software and services used to verify device functionality, performance and reliability from wafer probe through final and system-level test. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The market was valued at USD 6.112 billion in 2023 and is projected forward at a 7.5% CAGR, reaching USD 7.06 billion in 2025 and USD 13.54 billion by 2034. Asia Pacific leads because most semiconductor assembly, memory production and high-volume device test is concentrated in the region.
Advantest’s current ATE portfolio includes V93000 EXA Scale for high-performance SoC and AI/HPC devices, T2000 modular testers, memory test systems and cloud-linked analytics through Advantest Cloud Solutions. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Segment Analysis: By Type
By type, the semiconductor test solutions market is segmented into SoC Test Solutions, Memory Test Solutions, RF / Analog Test Solutions, Test Accessories & Services. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row.
| Type | Function | Market position |
|---|---|---|
| SoC Test Solutions | SoC Test Solutions addresses a distinct architecture or performance requirement within the Semiconductor Test Solutions market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Memory Test Solutions | Memory Test Solutions addresses a distinct architecture or performance requirement within the Semiconductor Test Solutions market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| RF / Analog Test Solutions | RF / Analog Test Solutions addresses a distinct architecture or performance requirement within the Semiconductor Test Solutions market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Test Accessories & Services | Test Accessories & Services addresses a distinct architecture or performance requirement within the Semiconductor Test Solutions market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
SoC and memory platforms command the largest system values, while RF/analog and specialty test solutions earn premiums where timing accuracy, channel density or application-specific instrumentation is required. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Segment Analysis: By Application
By application, the market is segmented into Automotive, Consumer Electronics, IT & Telecommunications, Industrial, Defense. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Application | Demand characteristics |
|---|---|
| Automotive | Automotive creates demand where semiconductor test solutions improves integration, performance, reliability or system economics. |
| Consumer Electronics | Consumer Electronics creates demand where semiconductor test solutions improves integration, performance, reliability or system economics. |
| IT & Telecommunications | IT & Telecommunications creates demand where semiconductor test solutions improves integration, performance, reliability or system economics. |
| Industrial | Industrial creates demand where semiconductor test solutions improves integration, performance, reliability or system economics. |
| Defense | Defense creates demand where semiconductor test solutions improves integration, performance, reliability or system economics. |
Regional Analysis
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile. Regional demand is shaped by manufacturing concentration, technology adoption, customer investment cycles and local supplier ecosystems. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
How does regional demand differ across the semiconductor test solutions market?
Asia Pacific provides the deepest manufacturing scale, North America contributes high-value technology and enterprise demand, and Europe remains important in industrial, automotive and regulated applications. South America and the Middle East & Africa are smaller but developing markets. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest | memory production, OSAT capacity and high-volume semiconductor manufacturing | Supply scale and qualification |
| North America | High | Moderate-high | AI/HPC, automotive and advanced semiconductor design | Technology capability and service |
| Europe | Moderate-high | Moderate | automotive, industrial and communications semiconductor testing | Compliance and lifecycle |
| South America | Smaller | Moderate | Import/industrial led | Cost and distribution |
| Middle East & Africa | Smallest base | Emerging | Infrastructure led | Project support |
Key Semiconductor Test Solutions Manufacturers and Competitive Landscape
The competitive landscape includes Advantest, Teradyne, Cohu, Tokyo Seimitsu, Hangzhou Changchuan Technology, Tokyo Electron, Beijing Huafeng Test & Control Technology, Chroma ATE, SPEA, Hon Precision. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Competition centers on higher parallelism, AI/HPC test coverage and data-driven adaptive testing, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Advantest, Teradyne, Cohu, Tokyo Seimitsu | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | Hangzhou Changchuan Technology, Tokyo Electron, Beijing Huafeng Test & Control Technology, Chroma ATE | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- Advantest
- Teradyne
- Cohu
- Tokyo Seimitsu
- Hangzhou Changchuan Technology
- Tokyo Electron
- Beijing Huafeng Test & Control Technology
- Chroma ATE
- SPEA
- Hon Precision
Semiconductor Test Solutions Production Capacity Analysis
Production capacity in the Semiconductor Test Solutions market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Semiconductor Test Solutions Market Dynamics: Drivers, Restraints and Opportunities
The Semiconductor Test Solutions market is shaped by growth is driven by ai accelerators, hbm, automotive semiconductors, advanced packaging and greater device complexity, all of which increase test time and coverage requirements. At the same time, growth is constrained by high tester cost, longer qualification, interface complexity, rapidly changing device protocols and pressure to reduce cost of test per device. The strongest commercial opportunities are concentrated in silicon-photonics test, system-level test, hbm/ai device test and adaptive analytics create the strongest opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion |
+1.2%Application-specificNear term
Higher value per system+0.8%Premium and advanced systemsMedium term
Technology adoption expands addressable demand
Growth is driven by AI accelerators, HBM, automotive semiconductors, advanced packaging and greater device complexity, all of which increase test time and coverage requirements. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by high tester cost, longer qualification, interface complexity, rapidly changing device protocols and pressure to reduce cost of test per device. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
Silicon-photonics test, system-level test, HBM/AI device test and adaptive analytics create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Regional capacity and supply resilience
Higher parallelism, ai/hpc test coverage and data-driven adaptive testing can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Semiconductor Test Solutions Supply Chain Analysis
Upstream. ATE mainframes, pin electronics, handlers, probe cards, sockets, interface boards, calibration tools, test software and analytics platforms form the supply chain. Supply quality at this stage directly affects downstream yield, reliability and cost. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Semiconductor Test Solutions Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Commercial decisions in the Semiconductor Test Solutions market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
- 2026 Current
Advantest showcases next-generation test platforms Advantest presented scalable semiconductor test systems, software and memory-test solutions at SEMICON India 2026 for increasingly complex devices. Source - 2026 Partnership
Advantest and OpenLight develop silicon-photonics test Advantest and OpenLight announced plans to develop scalable high-volume test solutions for silicon-photonics optical engines used in AI infrastructure. Source - 2026 Current
ATE analytics and automation expand Advantest describes V93000 EXA Scale, T2000, memory testers and cloud analytics as core platforms for complex semiconductor test workflows. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 7.06 billion |
| Market Size 2034 | USD 13.54 billion |
| Growth Rate | CAGR of 7.5% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Test Stage, By End User, and By Region |
| By Type | SoC Test Solutions · Memory Test Solutions · RF / Analog Test Solutions · Test Accessories & Services |
| By Application | Automotive · Consumer Electronics · IT & Telecommunications · Industrial · Defense |
| By End User | IDMs · Foundries · OSATs · Fabless Semiconductor Companies |
| By Test Stage | Wafer Probe · Package / Final Test · System-Level Test · Burn-In |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | Advantest, Teradyne, Cohu, Tokyo Seimitsu, Hangzhou Changchuan Technology, Tokyo Electron, Beijing Huafeng Test & Control Technology, Chroma ATE, SPEA, Hon Precision |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Semiconductor Test Solutions market?
The market is valued at USD 7.06 billion in 2025 and is projected to reach USD 13.54 billion by 2034, expanding at a 7.5% CAGR during 2026–2034.
Which companies lead the Semiconductor Test Solutions market?
Key participants include Advantest, Teradyne, Cohu, Tokyo Seimitsu, Hangzhou Changchuan Technology, Tokyo Electron, Beijing Huafeng Test & Control Technology, Chroma ATE.
What is Semiconductor Test Solutions?
Semiconductor test solutions combine automated test equipment, handlers, interfaces, software and services used to verify device functionality, performance and reliability from wafer probe through final and system-level test.
What are the main product types?
The market includes SoC Test Solutions, Memory Test Solutions, RF / Analog Test Solutions, Test Accessories & Services.
What are the key applications?
The principal applications are Automotive, Consumer Electronics, IT & Telecommunications, Industrial, Defense.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by AI accelerators, HBM, automotive semiconductors, advanced packaging and greater device complexity, all of which increase test time and coverage requirements.
What are the main challenges?
Growth is constrained by high tester cost, longer qualification, interface complexity, rapidly changing device protocols and pressure to reduce cost of test per device.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF