Key Statistics
Key Takeaways
- Dot Matrix LCD Modules are the leading type because they support high-resolution graphics and flexible interfaces across consumer, industrial and transportation applications.
- Consumer Electronics is the largest application, representing more than 45% of revenue in the market overview and over 60% of application volume in the current demand structure.
- Asia Pacific leads with more than 65% market share, supported by large display manufacturing ecosystems in China, Japan and South Korea.
- TFT-LCD remains the dominant technology due to its image quality, cost efficiency and manufacturing scale, while OLED creates the strongest substitution pressure in premium consumer devices.
- 2026 innovation is focused on higher resolution, integrated touch, low power and specialized displays. Tianma showcased new LTPS-LCD, oxide-LCD, AMOLED and medical/industrial products, while BOE continues to expand intelligent-display solutions across consumer and automotive markets.
Liquid Crystal Display Module (LCM) Market Overview
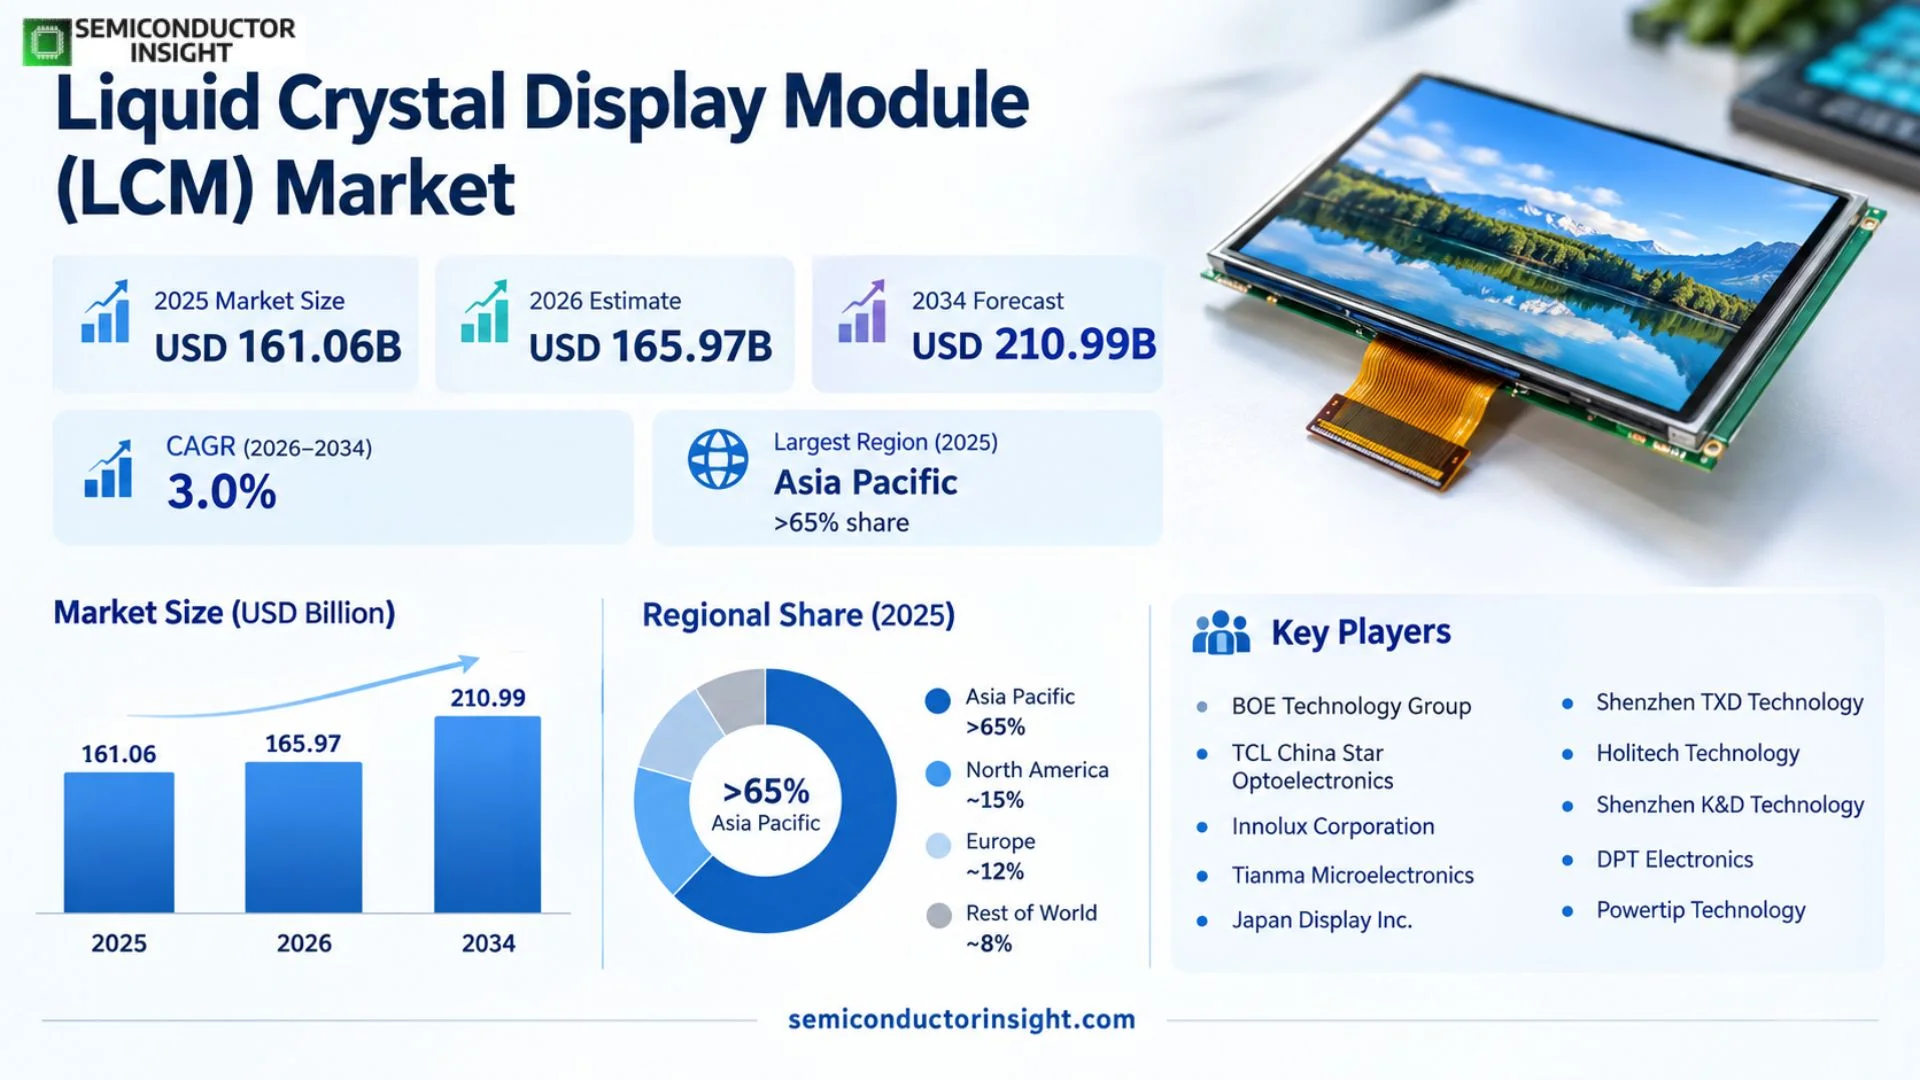
Liquid Crystal Display Module (LCM) market is valued at USD 161.06 billion in 2025 and is projected to reach USD 210.99 billion by 2034, representing a 3.0% CAGR during 2026–2034. The 2026 estimated market size is USD 165.97 billion. Asia Pacific is the dominant regional market with more than 65% share.
Liquid crystal display modules combine the LCD panel with driver electronics, backlight, interfaces and often touch or optical bonding into an integrated display subsystem. Modules range from simple segmented numeric displays to complex high-resolution TFT assemblies used in smartphones, monitors, industrial HMIs and vehicle dashboards.
The market remains broad because LCD technology spans very low-cost monochrome products through advanced oxide and LTPS TFT displays. Mature module ecosystems support long product lifecycles, wide-temperature operation and customized mechanical interfaces, making LCD especially durable in industrial, medical and transportation applications.
Competitive pressure is strongest in premium consumer products where OLED can deliver thinner form factors and deeper contrast. LCD module suppliers are responding with higher refresh rates, advanced backlights, touch integration, narrow borders, energy-efficient oxide backplanes and specialized 2D/3D visualization.
Segment Analysis: By Type
By type, the market includes Segment LCD Modules, Character LCD Modules, Dot Matrix LCD Modules, Font Type LCD Modules and Others. Dot Matrix modules lead because they can display graphics, text and dynamic interfaces across many device classes.
| Type | Technical characteristics | Market position |
|---|---|---|
| Dot Matrix LCD Module | Pixel-addressable matrices support alphanumeric and graphical interfaces, from monochrome industrial displays to color TFT modules. They can integrate touch, controller ICs and high-speed digital interfaces. | Leading type. Broad use in consumer electronics, industrial HMIs, transport and instrumentation supports the largest value pool. |
| Character LCD Module | Predefined character matrices provide reliable text output with simple controller interfaces and low power consumption. | Stable mature segment for industrial equipment, test instruments, appliances and embedded systems. |
| Segment LCD Module | Dedicated segments display numbers, symbols and simple icons with very low power and cost. | Durable high-volume segment in meters, appliances, healthcare and battery-powered equipment. |
| Font Type / Custom Module | Customized display layouts combine predefined symbols, fonts and application-specific interfaces. | Niche segment where readability, low power and product-specific form factor matter more than graphics flexibility. |
Technology and interface segmentation
The market also segments by display technology and electrical interface. TFT-LCD holds the major technology share because it supports high resolution and color performance, while TN/STN remain important in simpler modules. Interface choice depends on bandwidth, pin count and installed controller architecture.
| Axis | Segments | Commercial implication |
|---|---|---|
| By Technology | TN · STN · TFT-LCD · OLED / Hybrid Display Modules · Others | TFT-LCD dominates value; TN/STN support low-cost embedded applications; OLED is the main competitive substitute in premium products. |
| By Interface | Parallel · SPI · I2C · USB · LVDS / MIPI / eDP and Others | Parallel and serial interfaces serve embedded modules, while high-resolution displays require faster links such as LVDS, MIPI or eDP. |
Segment Analysis: By Application
By application, Consumer Electronics is the largest segment, followed by industrial control, transportation, optical instruments and other specialized applications.
| Application | Key market insight |
|---|---|
| Consumer Electronics | Smartphones, TVs, tablets, notebooks, smart-home products and appliances create the largest volume base. Cost, resolution, refresh rate and power efficiency determine module selection. |
| Industrial Control Equipment | Factory HMIs and control panels prioritize wide temperature range, sunlight readability, glove touch, rugged construction and long product availability. |
| Transportation Equipment | Automotive clusters, center displays, rail systems and aviation interfaces use high-brightness, durable modules with strict reliability requirements. |
| Optical / Medical Instruments | Diagnostic and measurement equipment requires consistent brightness, fine detail, color accuracy and long lifecycle support. |
| IoT / Smart Devices | Thermostats, meters and connected appliances create customized low-power opportunities between simple segment displays and full TFT modules. |
Regional Analysis
Asia Pacific leads the global LCM market with more than 65% share. China, Japan and South Korea form the core manufacturing base, with Taiwan also important through panel and module production. North America and Europe remain major demand markets for premium consumer, automotive, industrial and medical displays.
Why is Asia Pacific central to LCM manufacturing?
Display production benefits from very large panel fabs, controller IC suppliers, optical films, backlight makers and electronics assembly located close together. This gives Asian suppliers cost and speed advantages while enabling rapid customization for consumer, automotive and industrial OEMs.
| Region | Market position | Growth outlook | Core demand | Commercial priority |
|---|---|---|---|---|
| Asia Pacific | Largest >65% | Moderate to high | Consumer, auto & industrial | Scale, cost and technology breadth |
| North America | Premium demand | Moderate | Consumer, medical & industrial | Specialized performance and OEM design |
| Europe | Industrial / automotive | Moderate | Auto, machinery & medical | Reliability and compliance |
| South America | Emerging | Moderate | Consumer & industrial | Affordability and imports |
| Middle East & Africa | Emerging | Moderate | Retail, telecom & infrastructure | Import availability and price |
Competitive Landscape
Key participants include BOE Technology Group, TCL China Star Optoelectronics, Innolux Corporation, Tianma Microelectronics, Japan Display Inc., Shenzhen TXD Technology, Holitech Technology, Shenzhen K&D Technology, DPT Electronics and Powertip Technology.
BOE is a large global display manufacturer with products spanning consumer electronics and automotive applications. Its scale, panel technology and module integration support cost competitiveness across multiple device categories.
Tianma competes strongly in automotive, industrial, medical and consumer displays. Its 2026 portfolio demonstrates continuing LCD innovation in oxide backplanes, high refresh, medical 3D visualization and rugged industrial formats even as AMOLED expands.
Innolux, TCL CSOT and JDI provide additional scale and technology depth, while smaller module companies compete through custom dimensions, interfaces and industrial lifecycle support. Competitive advantage depends on panel access, driver electronics, optical bonding, quality and application engineering.
Competitive tier structure
| Competitive tier | Representative companies | Competitive strengths |
|---|---|---|
| Global panel / module leaders | BOE; TCL CSOT; Innolux; Tianma; JDI | Panel scale, high-resolution TFT, automotive qualification and global OEM relationships |
| Module specialists | TXD; Holitech; K&D; DPT; Powertip | Customized modules, industrial interfaces and flexible production volumes |
| Application specialists | Regional industrial / medical suppliers | Long lifecycle, ruggedization, optical bonding and specialized certification |
Key companies profiled
LCM Production Capacity & Module Integration Analysis
LCM capacity depends on panel supply, backlight assembly, driver ICs, touch sensors, optical films, bonding, PCB assembly and final testing. High-volume consumer modules use automated lines, while industrial and medical modules require more customization and smaller-lot production.
Panel-fab cycles influence module pricing because LCD glass and TFT capacity represent the largest fixed-cost layer. When panel utilization changes, downstream module prices can move quickly even if final-device demand is stable.
Customization is a second capacity constraint. Mechanical frames, connectors, firmware, cover glass and touch integration differ by customer, so effective capacity depends on engineering resources and changeover efficiency as well as nominal line throughput.
Market Dynamics
Growth is driven by consumer electronics, automotive displays, industrial automation and smart devices. Restraints include OLED substitution, price competition, panel cycles and commoditization. Opportunities center on high-resolution TFT, touch integration, industrial durability, automotive displays and energy-efficient backlights.
MARKET DRIVERS
LCD remains cost effective at scale
Large manufacturing capacity keeps TFT-LCD competitive in televisions, monitors, industrial displays and mid-range devices.
Vehicles use more displays
Digital clusters, infotainment and passenger screens increase module count per vehicle.
Factories need durable HMIs
Industrial modules require brightness, ruggedness and long product availability that favor established LCD platforms.
Smart devices create custom display niches
Appliances, meters and connected devices need low-power, application-specific modules.
Drivers Impact Analysis
| Driver | Impact | Primary markets | Time horizon |
|---|---|---|---|
| Consumer electronics demand | High | Asia, North America, Europe | Persistent |
| Automotive digitization | High | Global vehicle markets | Medium to long term |
| Industrial automation | Medium to high | Europe, Asia, Americas | Persistent |
| IoT / smart devices | Medium | Global | Persistent |
MARKET RESTRAINTS
OLED is taking premium share
Self-emissive displays offer contrast, thinness and flexible form factors in smartphones and premium electronics.
Commodity modules face margin pressure
Asian scale and standardization reduce differentiation in basic TFT products.
Panel cycles affect pricing
Large fixed-cost fabs can create periods of excess or tight capacity.
Industrial customers require long support
Small-volume customized modules can remain active for years, increasing engineering and inventory complexity.
Restraints Impact Analysis
| Restraint | Impact | Exposure | Time horizon |
|---|---|---|---|
| OLED substitution | High | Premium consumer devices | Persistent |
| Price competition | High | High-volume modules | Persistent |
| Panel utilization cycles | Medium to high | Global supply chain | Recurring |
| Long industrial qualification | Medium | Industrial / medical | Persistent |
MARKET OPPORTUNITIES
Expand automotive modules
Larger cockpit screens, touch integration and high-brightness panels create higher value per vehicle.
Grow medical and industrial LCD
Specialized 3D, sunlight-readable and rugged displays offer stronger margins than commodity consumer modules.
Improve energy efficiency
Oxide TFT, adaptive refresh and advanced backlights can extend battery life and reduce system power.
Integrate touch and optical bonding
Combined modules simplify OEM assembly and improve optical performance.
Liquid Crystal Display Module Value Chain Analysis
Glass / TFT panel fabrication
Driver / backlight / touch components
Module integration
OEM device integration
Panel technology sets the cost base
Generation size, TFT process and utilization determine much of module economics.
Optical components determine visible performance
Polarizers, backlights and bonding affect brightness, contrast and viewing angle.
Interfaces determine integration complexity
Controller choice and communications protocol affect PCB design and firmware.
OEM qualification creates long-term programs
Automotive and industrial designs can ship for years after module approval.
Recent Developments in the Liquid Crystal Display Module (LCM) Market
Tianma wins Display Week award for LCD medical 3D technology
Tianma’s 27-inch 4K medical display with multi-region 2D/3D switching was recognized as Best LCD-Based Technology.
Tianma expands professional and industrial display portfolio
Display Week 2026 products included a 27-inch QHD oxide monitor and new workplace displays across LCD and AMOLED technologies.
BOE showcases smart-display innovation at AWE 2026
BOE presented AI-enabled display, smart cockpit and next-generation consumer-display solutions across multiple scenarios.
Tianma presents next-generation automotive display systems at CES
The portfolio included LTPS-LCD, AMOLED and MicroLED technologies integrated into Smart Cockpit 7.0.
Tianma industrial portfolio emphasizes rugged TFT-LCD modules
Current products include high-brightness, wide-temperature and integrated-touch displays for HMI, industrial vehicles and monitors.
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2019–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2019–2025 |
| Market Size 2025 | USD 161.06 billion |
| Market Size 2034 | USD 210.99 billion |
| Growth Rate | 3.0% during 2026–2034 |
| Unit | Value (USD Million/Billion) and display-module shipments |
| By Type | Segment LCD Module · Character Type LCD Module · Dot Matrix LCD Module · Font Type LCD Module · Others |
| By Application | Consumer Electronics · Industrial Control Equipment · Transportation Equipment · Optical Instruments · Others |
| By Technology | TN · STN · TFT-LCD · OLED / Hybrid · Others |
| By Interface | Parallel · SPI · I2C · USB · LVDS / MIPI / eDP and Others |
| By Region | Each region analysed by module type, application, technology, interface and country display ecosystem North AmericaUnited States, Canada, Mexico EuropeGermany, France, United Kingdom, Italy and other European markets Asia PacificChina, Japan, South Korea, Taiwan, India and other Asian markets South AmericaBrazil, Argentina, Chile and other South American markets Middle East & AfricaUAE, Saudi Arabia, South Africa and other MEA markets |
| Key Companies Profiled | BOE Technology Group · TCL China Star Optoelectronics · Innolux Corporation · Tianma Microelectronics · Japan Display Inc. (JDI) · Shenzhen TXD Technology · Holitech Technology · Shenzhen K&D Technology · DPT Electronics · Powertip Technology |
| Customization Scope | Free report customization equivalent to up to four analyst working days with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the 2025 size of the Liquid Crystal Display Module market?
The market is valued at USD 161.06 billion in 2025 and is projected to reach USD 210.99 billion by 2034. The 2026 estimate is USD 165.97 billion and the 2026–2034 CAGR is 3.0%.
Which LCM type leads the market?
Dot Matrix LCD Modules lead because they support graphical, alphanumeric and high-resolution interfaces across consumer, industrial and transport applications.
Which application is the largest?
Consumer Electronics is the largest application, supported by smartphones, TVs, computers, appliances and smart devices.
Which region leads the market?
Asia Pacific leads with more than 65% share through the display manufacturing ecosystems of China, Japan, South Korea and Taiwan.
What is the estimated market size in 2026?
The 2026 estimated market size is USD 165.97 billion within the consistent long-term market series.
Why does LCD remain competitive?
LCD combines mature manufacturing, broad size coverage, reliable industrial operation and lower cost than OLED in many applications.
What are the main market restraints?
OLED substitution, pricing pressure, display-panel utilization cycles and commoditization are the main constraints.
Which technology has the largest share?
TFT-LCD holds the major technology share because it combines full-color image quality, resolution and manufacturing scale.
Which companies are active in the market?
Major participants include BOE, TCL CSOT, Innolux, Tianma, JDI, TXD, Holitech, K&D, DPT and Powertip.
What does the report cover?
The report covers module type, application, display technology, interface, five global regions, competitive landscape, capacity, dynamics, recent developments and value chain.
Research Sources & Evidence Base
View primary and authoritative evidence used in this overview
- BOE. Automotive Display – Official evidence on BOE’s LCD and integrated automotive-display capabilities.
- BOE. AWE 2026 Display Innovation – March 2026 evidence on display, AI and smart-cockpit innovation.
- Tianma. Industrial Displays – Official evidence on rugged TFT-LCD products, integrated touch and wide-temperature operation.
- Tianma. Consumer Displays – Official evidence on LTPS TFT-LCD, AMOLED and low-power consumer display technologies.
- Tianma. Display Week 2026 Press Information – 2026 evidence on medical, industrial, automotive and consumer display development.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF