Key Statistics
Key Takeaways
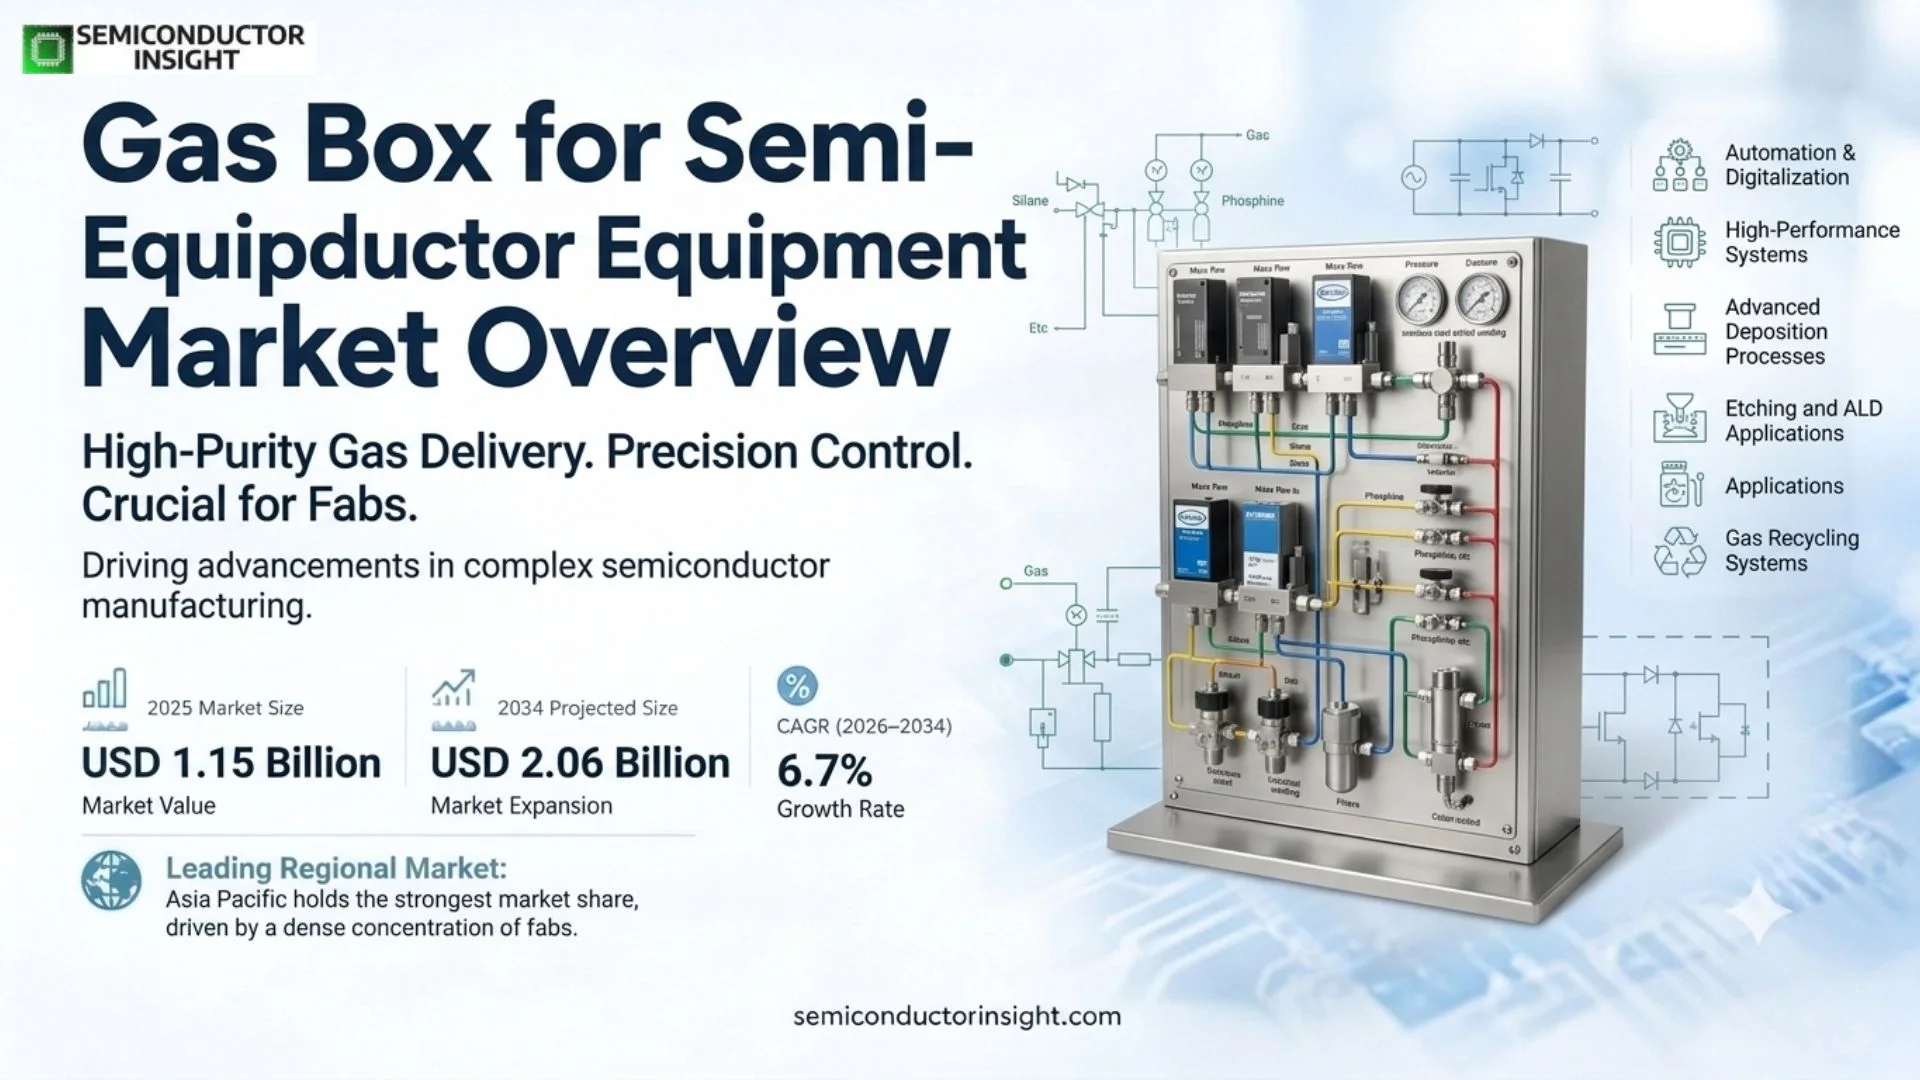
- Market size and growth: the market is estimated at USD 1.23 billion in 2026 and is projected to reach USD 2.06 billion by 2034, representing a 6.7% CAGR during 2026–2034.
- 300mm gas boxes dominate because advanced logic and memory fabs use 300mm tools and require more sophisticated gas-delivery assemblies for deposition, etch and thermal processes.
- Thin-film deposition equipment is the leading application because CVD and ALD processes depend on highly precise flow, pressure control and precursor isolation across multiple gas channels.
- Asia Pacific leads through large fab clusters in Taiwan, South Korea, China and Japan, while U.S. and European fab localization is creating a second wave of regional demand.
- Component integration is increasing: gas boxes increasingly combine mass-flow controllers, regulators, filters, valves, sensors and digital monitoring into modular assemblies supplied directly to semiconductor equipment OEMs.
Gas Box for Semiconductor Equipment Market Overview
Gas Box for Semiconductor Equipment market was valued at USD 1.15 billion in 2025 and is estimated at USD 1.23 billion in 2026. The market is projected to reach USD 2.06 billion by 2034, representing a CAGR of 6.7% during 2026–2034. Asia Pacific is the largest regional market because Taiwan, South Korea, China and Japan contain the world’s densest concentration of semiconductor fabs, process-equipment suppliers and specialty-gas infrastructure.
Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated
Gas boxes are modular gas-distribution assemblies installed inside or adjacent to semiconductor process equipment. They integrate valves, mass-flow controllers, pressure regulators, filters, gauges and safety functions so toxic, corrosive, flammable or inert process gases can be delivered precisely to deposition, etch, ion-implant and thermal tools. The assembly must maintain leak integrity, low particle generation and repeatable flow while operating under the stringent contamination and safety requirements of wafer fabrication.
The market scales with both new equipment shipments and the installed base of semiconductor process tools. Advanced nodes use more process steps, more precursor gases and tighter flow tolerances, increasing gas-channel density and the value of the delivery subsystem. 300mm tools dominate leading-edge production, but 200mm demand remains resilient in analog, power, MEMS and automotive fabs. Gas boxes also generate recurring service demand through valve, filter, regulator and mass-flow-controller replacement or refurbishment.
Supplier capability extends beyond assembling purchased components. Companies must design compact manifolds, optimize dead volume, select corrosion-resistant wetted materials and validate leak performance against specific gases. Fujikin’s semiconductor systems portfolio includes integrated gas systems and thermal or pressure-based flow-control products, illustrating the degree of component integration in advanced gas delivery. Large equipment suppliers increasingly prefer pre-engineered modules that reduce tool assembly time and simplify quality control.
Segment Analysis: By Type
By type, the market is segmented into 200mm, 300mm and other gas-box configurations. 300mm systems lead because advanced logic, memory and high-volume fabs are built around 300mm process tools with complex multi-gas recipes. The 200mm segment remains commercially important for mature-node automotive, analog, power and MEMS manufacturing, where fabs continue to add capacity and extend tool lifetimes. Other formats include specialized pilot, compound-semiconductor and non-standard equipment architectures.
| Type | Technical / commercial role | Market position |
|---|---|---|
| 200mm | Gas-delivery assemblies for mature-node and specialty wafer equipment. | Stable demand from analog, power, MEMS and automotive fabs. |
| 300mm | High-density gas boxes for advanced logic, memory and high-volume production tools. | Largest segment; benefits from leading-edge fab and equipment investment. |
| Others | Specialized sizes and custom configurations for pilot or compound-semiconductor tools. | Niche growth where process recipes or equipment footprints differ from mainstream 200/300mm systems. |
Segment Analysis: By Application
Applications include etchers, ion implantation equipment, thin-film deposition equipment, heat-treatment equipment and other dry-process tools. Thin-film deposition is the leading application because CVD and ALD systems use multiple high-purity precursors with demanding flow accuracy. Etch tools also require sophisticated gas mixing and isolation, while ion implantation and thermal equipment use specialized gas-delivery modules matched to process chemistry and safety requirements.
| Application | Demand characteristics |
|---|---|
| Etcher | Multi-gas plasma processes require precise flow control, isolation and corrosion-resistant components. |
| Ion Implantation Equipment | Specialty source gases require rigorous safety, purity and pressure regulation. |
| Thin Film Deposition Equipment | Leading application; CVD and ALD tools use multiple controlled precursor and carrier-gas channels. |
| Heat Treatment Equipment | Thermal processes require repeatable purge, carrier and reactive gas delivery. |
| Others | Includes cleaning, epitaxy and specialized compound-semiconductor tools. |
Segment Analysis: By Component
Component segmentation explains where value is captured inside the gas-delivery assembly. The enclosure and manifold provide safe modular integration, mass-flow controllers determine accurate dosing, pressure regulators stabilize upstream conditions and high-precision filters protect the process from particles. Valves, sensors and fittings complete the system. Suppliers that can integrate these components into a tested module reduce equipment-OEM assembly work and can capture more value than vendors selling individual components alone.
| Component | Commercial role |
|---|---|
| Gas Box / Manifold | Mechanical integration, isolation and safe routing of process gases. |
| Mass Flow Controllers | Critical metering component controlling gas dose and recipe repeatability. |
| Pressure Regulators | Stabilize pressure before precision flow-control elements. |
| High-Precision Filters | Protect tools and wafers from particles and contamination. |
| Others | Valves, sensors, gauges, fittings and monitoring electronics. |
Segment Analysis: By End User
End users include foundries, integrated device manufacturers, semiconductor equipment OEMs and research or pilot fabs. Equipment OEMs are the direct design-in customers for many gas boxes because modules are engineered into etch, deposition or thermal platforms before shipment. Foundries and IDMs influence approved-component lists, safety requirements and maintenance practices, while pilot fabs and compound-semiconductor lines create smaller customized opportunities with different gas chemistries and tool footprints.
| End User | Demand logic |
|---|---|
| Foundries | High equipment volumes and advanced-node process complexity. |
| IDMs | Memory, analog, power and logic fabs with long installed-equipment lifecycles. |
| Semiconductor Equipment OEMs | Primary design-in customers integrating gas modules into process tools. |
| Research & Pilot Fabs | Small-volume custom systems for process development and specialty semiconductors. |
Regional Analysis
Asia Pacific leads the market because the majority of semiconductor wafer fabrication and equipment installation occurs in Taiwan, South Korea, China and Japan. North America is gaining strategic importance as new U.S. fabs expand local tool and subsystem demand. Europe maintains a smaller but high-specification market around automotive, power and equipment ecosystems. Regional service and spare availability are important because a gas-delivery failure can stop an expensive process tool.
Gas-box demand follows the location of process-equipment manufacturing and wafer fabs. Asia Pacific has the largest installed base and the deepest specialty-gas supply chain. U.S. localization creates opportunities for suppliers with domestic engineering and manufacturing support, while Europe values traceability, safety and long service life. A single equipment platform may be assembled in one country and installed in another, so suppliers need global qualification consistency even when manufacturing is regionally distributed.
| Region | Position | Growth outlook | Demand profile | Supplier-selection factor |
|---|---|---|---|---|
| Asia Pacific | Largest | High | Fab and tool concentration | Purity, capacity and service |
| North America | Strategic growth | High | New fabs and equipment suppliers | Domestic support and qualification |
| Europe | Established | Moderate | Automotive / power semiconductors | Safety and reliability |
| South America | Small | Selective | Limited front-end capacity | Import cost |
| Middle East & Africa | Emerging | Selective | Israel and new technology projects | Technical support |
Competitive Landscape
Competition in the Gas Box for Semiconductor Equipment market is shaped by technology performance, customer qualification, application engineering and continuity of supply. Leading companies use product breadth and global support to win large programs, while specialist suppliers can defend attractive niches through deeper technical performance in specific applications. As the market expands, customers increasingly evaluate total system value and lifecycle support rather than relying only on initial component price.
The leading suppliers compete through a combination of proprietary technology, manufacturing scale and customer relationships. In the Gas Box for Semiconductor Equipment market, design wins can remain in place for several product generations because switching suppliers often requires requalification, software changes or manufacturing adjustments. This creates durable revenue positions for vendors that deliver reliable performance and responsive technical support.
Regional suppliers can still gain share where local availability, cost and fast engineering response matter. Their strongest opportunities are generally in standardized or mature applications, while the highest-performance segments remain concentrated among companies with deeper intellectual property, process control and qualification histories. This creates a market structure with both global platform leaders and specialized regional competitors.
Competitive strategy is increasingly moving toward integrated solutions. Customers prefer suppliers that can combine the core product with software, interface components, testing, support or adjacent technologies because integration reduces project risk and development time. Companies able to solve a broader customer problem therefore have more pricing power than vendors competing only on a single specification.
| Competitive tier | Representative companies | Competitive basis |
|---|---|---|
| Global technology leaders | Ultra Clean Holdings, Ichor Systems, CKD Corporation, Fujikin Group | Scale, broad product portfolios, strong R&D and global customer support. |
| Established specialists | FITOK Group, Shanghai Gentech, Shenyang Fortune Precision Equipment, UNILOK | Application-specific engineering and strong qualification in selected segments. |
| Regional / emerging suppliers | Regional suppliers | Local service, competitive pricing and focused customer relationships. |
Key Participants
The profiled competitive set includes Ultra Clean Holdings, Ichor Systems, CKD Corporation, Fujikin Group, FITOK Group, Shanghai Gentech, Shenyang Fortune Precision Equipment, UNILOK. Supplier position depends on engineering performance, customer qualification, manufacturing continuity and the ability to support design changes over long product cycles. Larger vendors benefit from broad portfolios and application teams, while specialists can retain strong positions in narrow, technically demanding subsegments where historical qualification and process know-how create meaningful switching costs.
Production Capacity Analysis
Production capacity for Gas Box for Semiconductor Equipment is constrained by the combination of specialized equipment, qualified materials, process know-how and customer-specific validation. Nominal factory output can overstate commercial supply because a new line or material source must often demonstrate consistent performance before it can serve high-value customers. This makes qualified capacity more important than raw nameplate capacity.
Regional manufacturing and service capacity influence lead time and resilience. Customers increasingly prefer suppliers that can support major production clusters from more than one site, reducing exposure to logistics disruption and single-factory events. At the same time, duplicating specialized processes can be difficult because equipment recipes, trained engineers and quality systems must be transferred without changing product performance.
The strongest capacity investments are aligned with structural demand drivers rather than short-term cycles. Suppliers expanding around AI, advanced semiconductor manufacturing, automotive electronics or industrial automation seek to secure positions before customer volumes scale. Effective capacity therefore includes engineering resources, test capability and local technical support in addition to physical manufacturing equipment.
| Capacity factor | Market implication |
|---|---|
| Specialized manufacturing | Determines qualified output and technical performance. |
| Critical materials / components | Can constrain supply despite available factory floor space. |
| Qualification and test | Controls how quickly new capacity becomes usable by customers. |
| Regional support | Improves lead time, resilience and customer retention. |
Market Dynamics
The Gas Box for Semiconductor Equipment market is driven by higher system performance, automation, digitalization and expanding use in high-value applications. Growth is moderated by development cost, qualification requirements and supply-chain concentration. The strongest opportunities occur where new architectures or applications create a clear performance advantage and where suppliers can reduce integration complexity for customers.
MARKET DRIVERS
| Driver | Relative impact | Commercial mechanism |
|---|---|---|
| Structural end-market growth | High | Expanding deployments increase unit demand and installed-base requirements. |
| Technology upgrade cycle | High | Higher performance raises value per product and accelerates replacement. |
| Customer integration needs | Medium-High | Validated solutions reduce engineering time and project risk. |
| Regional capacity expansion | Medium | New manufacturing clusters create local supplier demand. |
Structural end-market expansion
Growth in the Gas Box for Semiconductor Equipment market is supported by rising deployment across its principal applications. Customers are investing because the technology improves performance, efficiency, automation or product capability in ways that are difficult to replicate with older approaches. This expands both new-system demand and the installed base that later requires replacement, upgrades or related services.
Higher technical requirements increase value per system
New product generations demand tighter performance, greater integration and better reliability. These requirements can increase selling prices even when unit volumes grow more slowly, because customers are willing to pay for solutions that protect yield, uptime or user experience. Suppliers with stronger engineering capability therefore benefit disproportionately from technology transitions.
Regional investment broadens customer access
Manufacturing and infrastructure investment in North America, Europe and Asia is creating additional customer clusters outside traditional centers. Local engineering support and shorter supply chains help suppliers qualify products earlier in new projects, creating an opportunity to win design positions before production reaches full scale.
MARKET RESTRAINTS
| Restraint | Relative impact | Commercial mechanism |
|---|---|---|
| Development and qualification cost | High | Raises barriers to entry and lengthens customer adoption. |
| Supply-chain concentration | Medium-High | Critical components or materials can limit output. |
| Price pressure | Medium | Customers seek lower total system cost as volumes increase. |
| Technology substitution | Medium | Alternative architectures can replace incumbent solutions in selected uses. |
Qualification slows supplier switching
Customers in technical markets cannot change suppliers based only on purchase price. New products must demonstrate performance, reliability and compatibility in the actual application, which can require months of engineering work. This limits the pace at which new entrants gain share and can delay commercialization of technically promising products.
Specialized inputs can constrain supply
Advanced products depend on a limited number of qualified materials, components or manufacturing tools. Shortages or long lead times at one upstream stage can restrict finished-product output even when downstream assembly capacity is available. Suppliers therefore carry strategic inventory or qualify alternate sources, but those actions increase cost.
Customer cost pressure remains persistent
As a technology becomes more widely adopted, customers expect lower unit costs and may redesign systems to use standardized components. Suppliers must offset this pressure through better performance, lower manufacturing cost and additional software or service value. Vendors that cannot maintain differentiation can face margin erosion even in a growing market.
MARKET OPPORTUNITIES
Smart gas-delivery modules
Adding pressure, flow, leak and valve-health sensors allows gas boxes to feed fab-wide monitoring systems and support predictive maintenance. The opportunity is to reduce unplanned tool downtime and identify drift before it affects process yield. Suppliers that integrate diagnostics with the hardware can create recurring software and service value beyond the original module sale.
Compound-semiconductor tools
SiC, GaN and photonics processes use specialty and sometimes highly reactive gases that require corrosion-resistant materials and strong leak control. Growth in compound-semiconductor capacity creates customized gas-box opportunities with higher engineering content than standard silicon tools. Suppliers can capture premium pricing where safety and chemical compatibility are critical.
Regionalized subsystem manufacturing
Fab localization in the United States and Europe increases the need for local gas-box assembly, test and spare-parts support. Equipment OEMs benefit from shorter lead times and lower logistics risk, while fabs gain faster service for production-critical components. Suppliers with qualified regional facilities can become preferred sources for new tool platforms.
Higher-density modular gas panels
Advanced process tools use more gas channels while equipment footprints remain tightly constrained. Compact modular designs that integrate MFCs, regulators, valves and filters can help OEMs increase channel density without expanding the tool frame. The opportunity rewards suppliers with precision machining, clean assembly and digital flow-control expertise.
Supply Chain Analysis
Specialized materials and components
Core product manufacturing
Qualification and system integration
End-user deployment, service and replacement
The upstream supply chain provides the specialized materials, semiconductor devices, mechanical components or substrates that determine baseline product performance. Qualified inputs are important because changes in composition or manufacturing source can alter reliability, electrical behavior or process compatibility. Suppliers therefore maintain close technical relationships with upstream partners and often approve alternate sources before a disruption occurs.
Manufacturing converts these inputs into finished products using process-specific equipment, inspection and test. Quality systems are central because customers expect lot-to-lot consistency and traceability, particularly in semiconductor, automotive and industrial applications. High-value suppliers differentiate through process control rather than simple assembly scale, and they invest heavily in metrology or validation to protect yield.
Downstream value is created when the product is integrated into the customer system and validated under real operating conditions. Application engineers support installation, software, calibration or process optimization, while service teams maintain the installed base. This lifecycle relationship creates recurring revenue through replacement, updates, refurbishment or expansion and makes customer support an important part of the market structure.
Recent Developments
23 Feb 2026 – Ultra Clean publishes 2025 annual report
Ultra Clean’s current reporting provides an updated view of a major semiconductor subsystem supplier serving gas delivery, precision manufacturing and advanced equipment markets. Source
2026 – Fujikin continues integrated gas-system and flow-control portfolio
Fujikin’s semiconductor product catalog includes integrated gas systems, pressure-based flow-control systems and thermal mass-flow controllers, reflecting increasing subsystem integration in advanced gas delivery. Source
2026 – Fab investment supports continued demand for precision gas delivery
Advanced logic, memory and compound-semiconductor manufacturing require more complex gas channels, leak control and contamination management, sustaining demand for integrated gas boxes and high-precision components. Source
REPORT SCOPE & SEGMENTATION
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Year | 2034 |
| 2025 Market Size | USD 1.15 billion |
| 2026 Market Size | USD 1.23 billion |
| 2034 Market Size | USD 2.06 billion |
| CAGR | 6.7% during 2026–2034 |
| Largest Market / Leading Geography | Asia Pacific |
| By Type | 200mm; 300mm; Others |
| By Application | Etcher; Ion Implantation Equipment; Thin Film Deposition Equipment; Heat Treatment Equipment; Others |
| By Component | Gas Box; Mass Flow Controllers; Pressure Regulators; High-Precision Filters; Others |
| By End User | Foundries; IDMs; Semiconductor Equipment OEMs; Research & Pilot Fabs |
Frequently Asked Questions
What is the size of the gas box for semiconductor equipment market?
The market is estimated at USD 1.23 billion in 2026 and is projected to reach USD 2.06 billion by 2034, representing a 6.7% CAGR during 2026–2034. The 2025 market size is USD 1.15 billion.
Which type leads the market?
300mm gas boxes lead because advanced logic and memory fabs predominantly use 300mm tools with complex multi-gas process requirements.
Which application is largest?
Thin-film deposition is the leading application because CVD and ALD equipment require precise control of multiple precursors and carrier gases.
Which region leads the market?
Asia Pacific leads because Taiwan, South Korea, China and Japan contain the largest concentration of semiconductor fabs and process-equipment manufacturing.
Which components are most important?
Mass-flow controllers, valves, pressure regulators, filters and the manifold or enclosure are core components. Their integration determines flow accuracy, cleanliness and safety.
What are the main constraints?v
Qualification cycles, high-precision component cost, hazardous-gas safety requirements and dependence on semiconductor capital-spending cycles are the main constraints.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF