Key Statistics
Key Takeaways
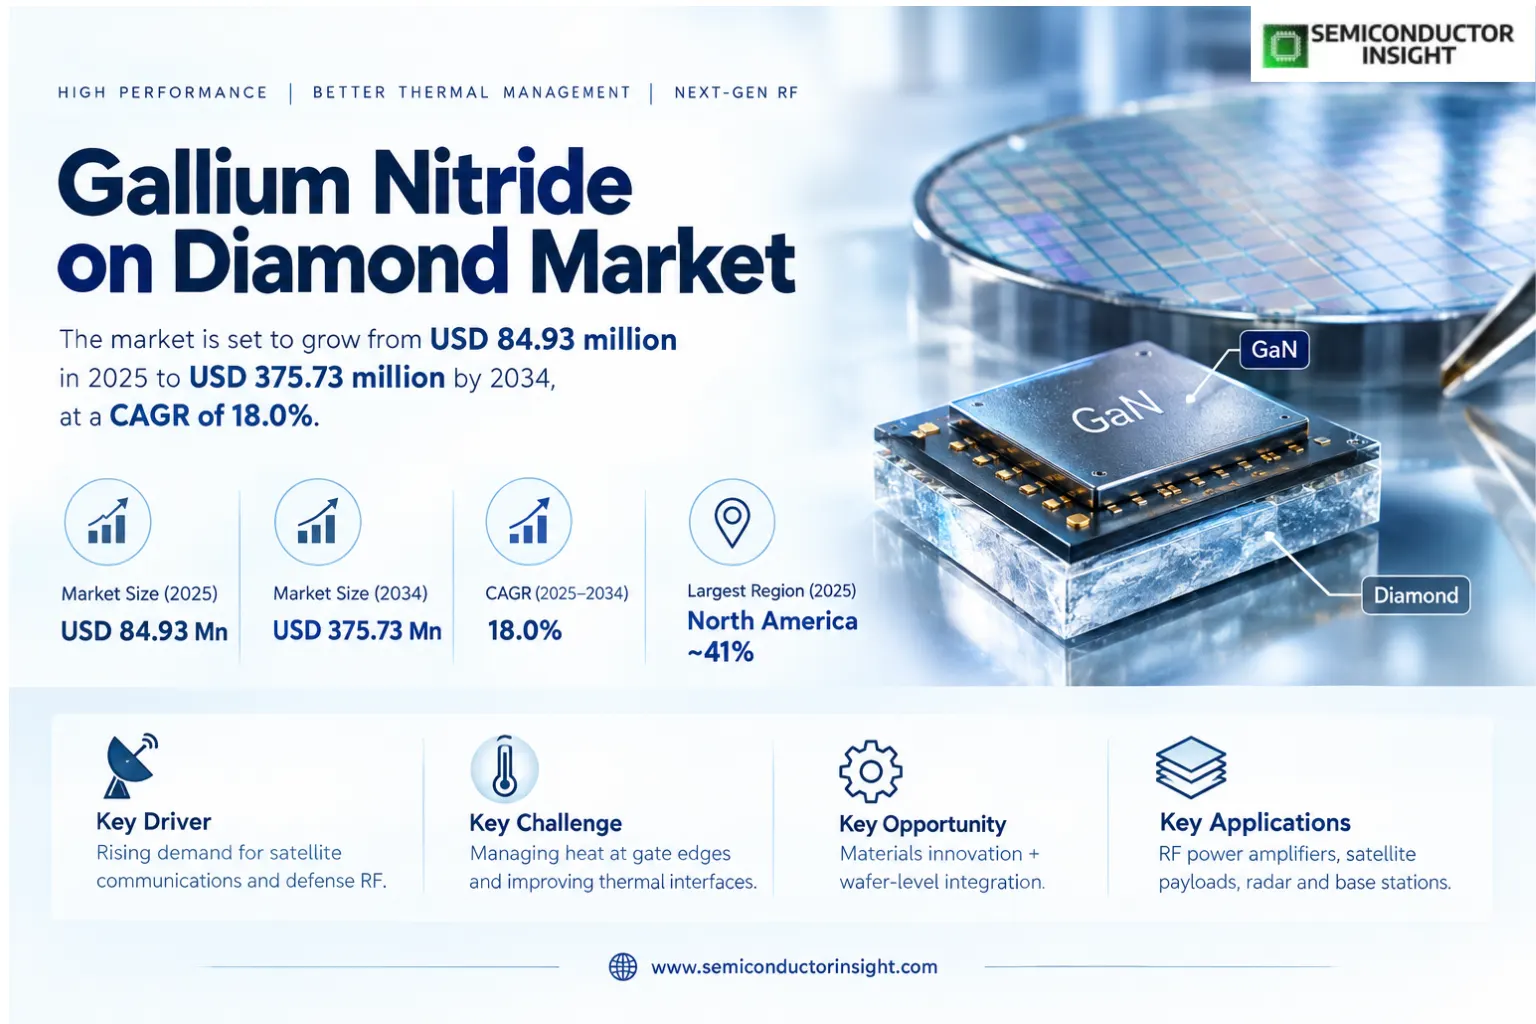
- Market trajectory: The 2025 market stands at USD 84.93 million, with the 2034 value projected at USD 375.73 million and a 18.0% compound annual growth rate; integrated diamond heat spreading is being explored where RF transistor junction temperature constrains power density.
- Wafer dimensions: Six-inch wafers represent the largest modeled type at ~42% of 2025 revenue, reflecting anticipated economics of higher die output per processing cycle rather than proof that six-inch GaN-on-diamond manufacturing is already mature.
- Priority application: Aerospace and military RF electronics hold the leading estimated application share at ~40%, because radar transmitters and space communication payloads place an unusually high premium on compact thermal management.
- Buyer concentration: RF component manufacturers account for an estimated ~42% of end-user spending; the commercial route typically passes through specialist process developers before reaching defense and network equipment integrators.
- Geographic position: North America holds the largest modeled regional share at ~41% in 2025, while Asia-Pacific hosts notable substrate transfer research and Europe contributes synthetic diamond and interface engineering expertise.
Gallium Nitride on Diamond Market Overview
Gallium nitride on diamond market was valued at USD 84.93 million in 2025 and is projected to reach USD 375.73 million by 2034, exhibiting a CAGR of 18.0% over 2025–2034. North America is the largest modeled regional market in 2025 at ~41%, reflecting its satellite communications and defense RF development base.
Gallium nitride transistors can sustain high electric fields and operate at microwave frequencies, yet the concentrated heat generated near their gate edges can force designers to reduce power or increase package size. Integrating a GaN active layer with a diamond thermal path addresses that specific bottleneck. Diamond conducts heat exceptionally well through its bulk, but the temperature benefit depends on bonding quality, interfacial materials and the distance between the transistor channel and the diamond layer. The commercial proposition therefore combines materials science with wafer-level process integration rather than simply replacing one commodity substrate with another.
The defined revenue boundary includes merchant GaN-on-diamond integrated wafers, transferred epitaxial structures, semiconductor dies and qualifying finished devices in which diamond is part of the active device thermal architecture. Development, prototype and pilot shipments are relevant to the emerging supply base. Standalone diamond heat spreaders sold for other chips, GaN-on-silicon-carbide products without diamond integration, completed satellite radios and generic diamond-cooled artificial intelligence servers fall outside the product boundary. Those adjacent products still matter because they develop polishing, deposition and bonding capabilities that may lower the cost of future GaN-diamond devices.
A critical manufacturing choice is whether to grow diamond near an existing nitride device layer, transfer GaN onto a prepared diamond surface, or embed small GaN dielets within a diamond interposer. These routes differ in attainable thermal resistance, wafer throughput, process damage and yield. The optimum interface is not necessarily the one with the highest nominal diamond conductivity: voids, thick adhesive films or electrically unsuitable intermediate layers can erase a substantial part of the thermal advantage. Buyers consequently require transistor-level thermal maps and reliability data, not merely a material supplier specification.
The industry remains a mixture of laboratory demonstrations, qualification programs and specialist commercial opportunities. A two-inch polycrystalline-diamond GaN transistor structure shows that direct bonding can move beyond tiny test coupons, while a diamond-interposer power amplifier illustrates an alternative assembly strategy. Neither demonstration alone establishes high-volume production at six-inch diameter. This distinction is especially important when interpreting modeled segment shares: the shares describe a forecast market allocation, not a certified census of current wafer fabrication capacity.
Purchasing decisions are shaped by the system-level value of reduced cooling mass and increased RF power density. A satellite payload may trade a higher device price for less thermal hardware; an airborne radar designer may seek more output from a restricted aperture; and a base-station supplier may prioritize amplifier lifetime under continuous load. Those benefits are conditional on repeatable die attachment, RF performance, long-duration thermal cycling and supplier qualification. Consequently, materials innovators, device foundries and module manufacturers must coordinate much earlier than in a conventional commodity-wafer supply chain.
Segment Analysis: By Type
By type, the market comprises 2-inch Wafers, 4-inch Wafers, 6-inch Wafers and Others. Six-inch material holds an estimated ~42% of the modeled 2025 value because wafer area can improve future unit economics, but publicly documented research remains more advanced at smaller diameters. The distinction between commercial aspiration and demonstrated process capability is central to this segmentation.
| Wafer type | Technical and commercial role | Market outlook |
|---|---|---|
| 2-inch Wafers | Small-diameter polycrystalline diamond supports device-transfer trials, interface characterization and repeatable electrical measurements across several dies. Its manageable handling cost makes it a practical platform for experiments that require repeated polishing, bonding and destructive cross-section analysis. | This class accounts for a modeled ~22% of 2025 revenue and grows at ~13.6% annually in the allocation. Its modeled values are USD 18.69 million in 2025, USD 21.23 million in 2026, USD 35.35 million in 2030 and USD 58.87 million in 2034. The smaller diameter is valuable for proof-of-concept work, yet it yields fewer saleable devices per batch and does not by itself establish a cost-competitive RF production platform. |
| 4-inch Wafers | Intermediate-diameter development connects university process demonstrations with industrial wafer handling and metrology. It is particularly relevant to scaling uniform bonding, monitoring wafer bow and assessing whether diamond surface preparation can meet device yield targets beyond small research coupons. | An estimated ~31% base-year share reflects its role as a process-transfer bridge, with a modeled ~17.2% CAGR. Corresponding category revenue is USD 26.33 million in 2025, USD 30.86 million in 2026, USD 58.22 million in 2030 and USD 109.85 million in 2034. Manufacturers seeking larger process windows can use this format before risking the capital and material loss associated with a full six-inch integration flow. |
| 6-inch Wafers | A larger wafer offers the prospect of more RF dies per lithography pass and better compatibility with established semiconductor process equipment. Realizing that advantage requires diamond availability, acceptable flatness and bond integrity across the full area, rather than merely cutting a larger disc. | The leading modeled ~42% share and ~20.7% annual growth represent anticipated revenue mix, not independently demonstrated mass production. The allocation moves from USD 35.67 million in 2025 to USD 43.07 million in 2026, USD 91.51 million in 2030 and USD 194.45 million in 2034. Commercial qualification will depend on defect density, substrate cost, thermal uniformity and whether wafer-scale yields offset the higher cost of large diamond surfaces. |
| Others | Nonstandard wafer diameters, test structures and custom bonded pieces serve process development when geometry is dictated by specialized equipment or a particular transistor layout. These items may be ordered in small batches for failure analysis, packaging trials or early customer evaluations. | A modeled ~5% allocation and ~12.8% growth capture bespoke work that is unlikely to benefit from the economies of standard wafer tooling. Modeled revenue increases from USD 4.25 million in 2025 to USD 4.79 million in 2026, USD 7.76 million in 2030 and USD 12.56 million in 2034. Buyers often accept higher unit prices in exchange for rapid iteration, traceability and flexible surface preparation. |
6-inch Wafer Economics and Qualification
Scaling to six inches changes the commercial equation because the number of possible die sites rises faster than diameter, while the acceptable number of bonding defects does not. A large diamond surface can reduce nominal cost per die only if its polishing, flatness and thermal interface remain consistent over the active area. The modeled ~42% share therefore reflects prospective adoption by process developers pursuing standardized RF wafer flows, and not a claim that all suppliers already ship qualified six-inch GaN-on-diamond wafers.
A manufacturer contemplating six-inch transfer must evaluate stress introduced by thermal expansion mismatch, dielectric and metal compatibility, lithographic overlay after bonding, and wafer-level thermal mapping. These are process-integration costs rather than ordinary raw-material expenses. The transition can be delayed even when device-level thermal results are compelling, because qualification demands statistically meaningful wafer lots and field reliability evidence.
2-inch and 4-inch Development Pathways
Smaller diameters remain strategically important despite their lower modeled revenue allocation. Two-inch substrates enable repeatable transistor comparisons against GaN on silicon or silicon carbide, while four-inch trials test whether those improvements survive a broader process window. Research teams can vary diamond grain structure, polish, surface activation and intermediate layers without committing an expensive full-size wafer to each experiment.
The industry benefits when laboratories disclose device-level temperature, power-added efficiency and interface measurements alongside wafer size. Diameter alone is a poor proxy for maturity: a two-inch device with reliable bonding may be more commercially relevant than a larger substrate with unproven yield. Consequently, pilot revenue may concentrate in smaller formats even while the modeled longer-term revenue mix favors larger wafers.
Segment Analysis: By Application
By application, the market covers Aerospace and Military, Automobile, Communication Network and Others. Aerospace and Military is the largest modeled application at ~40% of 2025 spending, followed by Communication Network at ~35%; the former values mission-level thermal performance while the latter demands a clearer cost-per-watt case for volume adoption.
| Application | Demand characteristics |
|---|---|
| Aerospace and Military | The leading ~40% allocation reflects radar transmit/receive modules, satellite RF payloads and other high-power microwave circuits where thermal headroom can improve duty cycle or reduce cooling mass. The modeled application progresses from USD 33.97 million in 2025 through USD 40.15 million in 2026 and USD 78.30 million in 2030 to USD 152.70 million in 2034. Defense procurement imposes stringent reliability, traceability and qualification conditions, so even a strong laboratory result must survive long customer validation before recurring production orders emerge. |
| Automobile | A modeled ~16% share captures prospective vehicle radar, high-frequency sensing and selected power-electronics integration experiments rather than broad replacement of established automotive GaN or SiC devices. Its revenue path is USD 13.59 million for 2025, USD 16.39 million for 2026, USD 34.67 million for 2030 and USD 73.34 million for 2034. Automotive programs emphasize thermal cycling, vibration, supply continuity and aggressive unit cost, creating a different commercialization path from low-volume aerospace electronics. |
| Communication Network | At an estimated ~35%, this segment includes high-power RF amplifiers for cellular infrastructure, microwave backhaul and specialized wireless links. Its projected revenue changes from USD 29.73 million in 2025 to USD 34.93 million in 2026, USD 66.58 million in 2030 and USD 126.91 million in 2034. Diamond integration can help where compact radios dissipate concentrated heat, but operators and equipment makers require a demonstrable reduction in lifetime cooling and maintenance cost before accepting a device premium. |
| Others | The remaining modeled ~9% includes industrial RF experiments, advanced instrumentation and specialist electronic research programs that may purchase custom devices in limited quantities. Its allocation corresponds to USD 7.64 million in 2025, USD 8.63 million in 2026, USD 14.02 million in 2030 and USD 22.78 million in 2034. These uses can establish technical references for later mainstream markets, but their heterogeneous specifications and uncertain production schedules make forecasting less predictable. |
End-user segmentation adds a separate view of the purchasing chain: RF Component Manufacturers are modeled at ~42%, Defense Contractors at ~28%, Semiconductor Foundries at ~20%, and Telecom Infrastructure Providers at ~10%. The RF component category grows from USD 35.67 million in 2025 to USD 42.23 million in 2026, USD 82.90 million in 2030 and USD 162.75 million in 2034. Defense contractors follow a different profile: USD 23.78 million for 2025, USD 27.68 million for 2026, USD 50.82 million for 2030 and USD 93.29 million for 2034. The manufacturer category is the largest because device designers must qualify thermal interfaces and amplifier characteristics before downstream system companies can specify a GaN-diamond solution. These buyer classes should not be summed with the application categories; they describe who purchases the product rather than where the final circuit operates.
Semiconductor foundries can become critical gatekeepers by determining whether transferred nitride layers are compatible with wafer handling, cleanroom contamination controls and high-frequency test procedures. The foundry buyer allocation is USD 16.99 million in 2025, USD 20.27 million in 2026, USD 41.05 million in 2030 and USD 83.15 million in 2034. Telecom infrastructure providers represent USD 8.49 million in 2025, USD 9.99 million in 2026, USD 19.10 million in 2030 and USD 36.54 million in 2034. Defense integrators often commission qualification lots tied to a specific radar or satellite architecture, whereas telecom infrastructure suppliers seek standardized parts that can be substituted without redesigning entire radio chains. Each channel therefore creates a distinct revenue profile, spanning engineering samples, process-transfer contracts and repeat component procurement.
Regional Analysis
North America is the largest modeled region at ~41% of 2025 value, with Asia-Pacific at ~28%, Europe at ~21%, South America at ~5% and the Middle East & Africa at ~5%. The regional distribution reflects differences in defense RF research, diamond materials production, device-integration capability and the availability of customers prepared to fund early qualification.
How do research capabilities and RF end markets shape regional demand?
Demand for GaN-on-diamond is not distributed in the same way as mature silicon wafer sales. Regions with large RF system design communities may lead prototype purchases even when the underlying diamond material is fabricated elsewhere. North America benefits from defense, satellite and university-led heterogeneous integration, while Asia-Pacific is important for nitride process engineering and wafer-scale transfer. Europe contributes synthetic diamond expertise and interface research; smaller regions more commonly access integrated devices through imports and research partnerships.
Five regional allocations are modeled for 2025, with differentiated growth rates based on the maturity of the local research-to-qualification pathway. North America remains the largest base-year market, but Asia-Pacific can expand faster as two-inch work advances toward four-inch process trials. Regional revenue should be understood as the location of product demand and integration activity, not a claim that every country possesses a commercial GaN-on-diamond foundry.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| North America | Largest (~41%) | ~17.7% CAGR | Defense and space RF qualification | System-level performance, export controls and reliability evidence |
| Asia-Pacific | Second (~28%) | ~20.5% CAGR | Nitride transfer and wafer scale-up | Bonding uniformity, materials cost and pilot manufacturing access |
| Europe | Third (~21%) | ~16.3% CAGR | Diamond materials and interface science | Material traceability, thermal characterization and integration partners |
| South America | Smaller (~5%) | ~13.5% CAGR | Imported specialist components | Application funding, academic links and procurement lead times |
| Middle East & Africa | Smaller (~5%) | ~14.7% CAGR | Satellite and defense electronics | Project qualification, vendor support and system integration |
Gallium Nitride on Diamond Market Competitive Landscape
The competitive structure combines diamond materials producers, GaN RF device specialists, semiconductor process developers and academic integration partners. These roles are not interchangeable: a company selling a high-conductivity diamond plate does not automatically supply GaN-on-diamond transistor wafers, and a GaN-on-SiC amplifier portfolio does not prove diamond integration. Qualification evidence must be assessed at the exact wafer or device architecture a prospective buyer intends to purchase.
Akash Systems is associated with GaN-on-diamond technology for satellite communications and RF applications, making it a relevant specialist in the integrated-device ecosystem. Sumitomo Electric and Osaka Metropolitan University have demonstrated direct integration on polycrystalline diamond, while MIT researchers have explored a different dielet-in-interposer approach. These efforts illustrate multiple technical routes competing to solve the same thermal bottleneck. The path that wins customer qualification will depend on assembly yield, thermal cycling, microwave gain and manufacturability rather than laboratory temperature improvement alone.
Element Six supplies engineered diamond materials and contributes upstream capability in thermal grades and surface engineering. Cardiff and Oak Ridge National Laboratory research addresses the interface physics that determine whether that material advantage reaches the transistor channel. RFHIC and Qorvo are relevant RF ecosystem participants, but publicly described GaN-on-SiC products and standalone diamond heat spreaders must be separated from direct GaN-on-diamond sales. Competitive analysis therefore distinguishes demonstrated integration, enabling material supply and adjacent RF customer access.
Corporate identities require care. II-VI adopted the Coherent name in 2022, so those labels represent a continuing corporate lineage rather than two independent competitors. Mitsubishi Electric and MACOM have RF semiconductor expertise, although inclusion in a broad publisher company list does not by itself establish shipment of integrated GaN-diamond wafers. Buyers should request device-level qualification evidence, including the thermal interface stack, substrate diameter and test conditions, before treating any listed organization as a volume supplier.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Integration specialists | Akash Systems; Diamontronics; Sumitomo Electric research collaboration | Demonstrated or developing GaN-diamond architectures; differentiation depends on thermal interface integrity and credible path to reproducible device output. |
| Diamond materials | Element Six; Coherent-related engineered materials capabilities | Synthetic diamond quality, polishing, surface finish and material consistency support device development without necessarily constituting integrated device revenue. |
| RF ecosystem and research | Qorvo; RFHIC; MACOM; Mitsubishi Electric; MIT; Cardiff; ORNL | Microwave device requirements and scientific evidence influence adoption, but supplier capability must be verified at the actual GaN-on-diamond product level. |
Key companies profiled
- Akash Systems
- Element Six
- Sumitomo Electric Industries
- RFHIC Corporation
- Qorvo
- MACOM Technology Solutions
- Mitsubishi Electric
- Coherent Corp.
- Diamontronics
- Wolfspeed
Gallium Nitride on Diamond Manufacturing and Capacity Analysis
Commercial production capacity remains constrained by the difficulty of combining a device-quality GaN layer with a polished diamond thermal path. Pilot processes may use direct bonding, layer transfer, diamond deposition or heterogeneous dielet assembly; the available public evidence does not establish a unified high-volume industry capacity figure. Effective capacity also depends on the yield of electrically functional devices rather than the gross area of processed substrates.
Diamond polishing is an early bottleneck because polycrystalline surfaces can contain grain-related roughness that compromises direct attachment of nitride layers. Surface activation, cleaning and pressure or temperature conditions must produce a stable bond without degrading the transistor. Even when a wafer looks uniform, localized voids can generate hot spots that negate the bulk thermal benefit. Process engineers therefore need maps of bond quality and thermal boundary resistance before scaling production.
Layer transfer introduces a separate sequence of release, handling, alignment and inspection steps. The GaN device layer may originate on silicon or another conventional growth substrate, then be transferred to diamond after front-end processing. A successful integration flow must preserve electrical performance and contact metallurgy while preventing cracking or contamination. Pilot manufacturing can be viable for expensive aerospace devices even if its throughput is too low for mainstream wireless infrastructure.
The alternative interposer route places small GaN dies into diamond structures, potentially reducing the amount of diamond material required per functional circuit. Its challenges shift toward placement accuracy, heterogeneous packaging yield and the reliability of thin attachment films. Comparing these architectures requires a common metric such as temperature reduction at a specified dissipated power, rather than assuming that larger diamond area always produces the better commercial device.
Gallium Nitride on Diamond Market Dynamics: Drivers, Restraints and Opportunities
Growth is driven by the value of improved RF thermal headroom, defense and satellite power-density requirements, and advances in wafer bonding and diamond interface engineering. High substrate cost, incomplete production yield evidence, thermal boundary resistance and long qualification cycles limit the pace at which promising demonstrations become recurring product revenue.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| High-power satellite and defense RF density | High | +7.00% | High | High | Medium |
| Diamond interface and layer-transfer advances | High | +5.50% | Medium | High | High |
| Communication amplifier cooling efficiency | Medium-High | +4.20% | Medium | High | High |
| Wafer diameter and pilot throughput progress | Medium | +3.10% | Low | Medium | High |
| Heterogeneous packaging integration | Low-Medium | +2.30% | Low | Medium | High |
| Others (industrial RF and scientific instrumentation) | Low | +1.40% | Low | Low | Medium |
Thermal headroom supports demanding RF payloads
Microwave power amplifiers generate heat close to the transistor channel, where localized temperature can degrade gain and lifetime. Diamond integration seeks to remove that heat without relying exclusively on bulky external cooling hardware. The strongest initial business case is a system in which lower cooling mass or greater output power has direct operational value, such as a satellite link or radar array. Qualification budgets in these markets can support expensive engineering samples before a mature volume supply chain exists.
Interface research reduces an important material penalty
High diamond conductivity is useful only when heat crosses the nitride-to-diamond boundary efficiently. Research into surface preparation, carbide interlayers and engineered interface structures targets that loss mechanism. Better control of thermal boundary resistance can translate into more stable amplifier behavior at elevated power, provided the process preserves RF characteristics. The commercial effect is an improved probability that a laboratory demonstration survives package-level qualification rather than an immediate guarantee of lower wafer prices.
Telecommunications creates a potential repeat-order channel
Cellular radio manufacturers increasingly seek compact high-efficiency amplifiers, but they usually require lower component cost and broader supplier support than aerospace customers. Diamond-enhanced GaN may be attractive at the highest power densities where cooling infrastructure limits radio design. Successful adoption would require a repeatable device platform, standardized testing and a convincing cost-per-watt improvement against established GaN-on-SiC alternatives. Those requirements make the telecom channel a longer-term opportunity than isolated research sales.
Wafer scaling could improve integration economics
Increasing usable substrate diameter can reduce processing overhead per die if bond defects, polishing losses and wafer bow remain under control. Four-inch development work is an intermediate test of those assumptions, while six-inch production represents a more demanding manufacturing goal. The growth contribution arises from the possibility of moving beyond bespoke devices to repeatable wafer lots, but realized value depends on saleable yield and process equipment compatibility.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Diamond substrate and polishing expense | High | -2.40% | High | High | Medium |
| Thermal boundary and bonding yield variability | Medium-High | -1.80% | High | Medium | Medium |
| Lengthy RF reliability and customer qualification | Medium | -0.90% | Medium | Medium | Low |
| Others (GaN-on-SiC competition and packaging complexity) | Low | -0.40% | Medium | Medium | Low |
Materials cost restricts the accessible market
High-quality synthetic diamond requires specialized growth and finishing, and the finished surface must satisfy demanding semiconductor integration requirements. Defective bonds or a failed process step can consume both the GaN layer and an expensive diamond component. This makes early device cost much higher than a simple comparison of bulk substrate thermal conductivity would imply. Applications with tight unit-price ceilings are therefore likely to adopt more established thermal solutions until process yield improves.
Thermal interfaces can undermine expected performance
A diamond substrate may exhibit excellent bulk conductivity while the bonded stack retains high thermal resistance at the GaN interface. Adhesive thickness, interfacial voids, grain structure and stress can all affect channel temperature. Suppliers must demonstrate the complete device stack under realistic electrical load, because an isolated diamond specification does not predict package performance. The need for detailed thermal metrology adds engineering time and raises the risk of late qualification failures.
Reliability cycles extend commercialization timelines
Defense, aerospace and telecom customers require evidence that thermal cycling, mechanical stress and continuous RF operation do not degrade the bonded interface or transistor characteristics. Testing can reveal defects that are invisible in an initial power-amplifier demonstration. Small suppliers may need to finance multiple fabrication and validation iterations before obtaining a repeat order, so the pace of recognized product revenue can lag the pace of scientific announcements.
MARKET OPPORTUNITIES
Diamond interposers open a packaging route
Embedding GaN dielets within a diamond interposer offers an alternative to bonding a continuous nitride layer over a large wafer. The architecture can target localized thermal hot spots and allow integration with established die fabrication processes. Commercial potential rests on precise placement, reliable thermal attachment and cost-effective package assembly, which may be easier to optimize for specialist RF modules than for commodity discrete devices.
Materials suppliers can sell process-ready surfaces
Diamond vendors may capture higher value by offering engineered surfaces with controlled roughness, defect density and traceable thermal properties rather than generic heat spreaders. Customers developing transferred GaN layers need repeatable interface conditions, and that requirement can support collaborative process specifications. However, upstream diamond revenue must remain separate from integrated GaN-on-diamond device sales when assessing the size of the defined market.
Defense and space programs can establish reference designs
A qualified microwave component for a demanding payload can become a reference for other high-reliability programs. The initial opportunity is not necessarily high unit volume; it is a documented improvement in thermal stability or reduced cooling burden that system designers can incorporate into a procurement specification. Such references may shorten later customer evaluations, although export controls and program-specific qualification remain obstacles.
Manufacturing partnerships could bridge research and volume
Collaboration among diamond growers, GaN foundries and RF package manufacturers can distribute the cost of scaling bonding and test processes. Joint development may produce a clearer handoff between material supply and device fabrication, reducing integration surprises. The most valuable milestones will be repeatable pilot yields, measured transistor performance and successful environmental testing rather than announcements of nominal wafer diameter alone.
Gallium Nitride on Diamond Supply Chain and Technology Outlook
The supply chain runs from engineered diamond and nitride epitaxy through surface preparation, layer transfer, microwave device fabrication and RF system qualification. Value is created at each interface, and a failure in any one step can prevent the thermal properties of the raw materials from becoming a commercial advantage. Supplier collaboration must also establish ownership of test data and responsibility for defective bonded lots.
Materials sourcing. The first commercial risk is obtaining diamond with a surface finish and dimensional tolerance suitable for the chosen GaN integration method. Diamond plates designed as external heat spreaders may require additional polishing and cleaning before they can be bonded directly to an active semiconductor layer. Material traceability and wafer mapping are important because local defects can have a disproportionate effect on transistor thermal behavior.
Integration and yield. Process transfer between a diamond specialist and a GaN foundry can introduce handling, contamination and equipment-compatibility problems. A pilot flow should document bond strength, interface thickness, device yield and thermal resistance at multiple wafer locations. These data allow customers to distinguish a scalable production method from a single successful sample, and they determine whether larger wafers will genuinely reduce unit cost.
Customer economics. A purchaser ultimately compares the total RF subsystem cost, not just the price of an integrated wafer. Higher output density may reduce heat sinks or improve reliability, but only if the thermal benefit survives packaging and operating conditions. Defense and satellite buyers may accept a high initial premium; commercial network equipment programs generally require clearer repeatability and long-term supplier support before design-in.
Recent Developments in the Gallium Nitride on Diamond Market
- 8 June 2026 Research milestone
MIT researchers described a heterogeneous microwave power amplifier with GaN-on-silicon dielets embedded in a single-crystal diamond interposer. The demonstrated circuit produced a four-watt-class result, highlighting a route in which diamond acts as both a thermal platform and a packaging substrate. The commercial significance lies in potential integration flexibility; mass-production yield and long-term thermal cycling still require separate validation. Source - 30 May 2025 Wafer demonstration
Sumitomo Electric and Osaka Metropolitan University announced a GaN-HEMT structure directly integrated on a two-inch polycrystalline diamond substrate. The project combined improved diamond polishing with transfer of a nitride layer, addressing a major barrier to wafer-scale bonding. The partners identified four-inch development as a subsequent target, but did not establish that this larger format had entered routine commercial manufacturing. Source - 2025 Interface research
Cardiff University researchers examined GaN and diamond interface engineering and reported substantially reduced effective thermal boundary resistance through surface nanopatterning. The work matters because poor heat transfer across a bond can negate the advantage of diamond bulk conductivity. Translation into production would require process repeatability, electrical characterization and compatibility with the temperature and cleanliness limits of semiconductor fabrication. Source - 2025 Materials research
Oak Ridge National Laboratory-associated work investigated engineered carbide interlayers and phonon transport at diamond and nitride boundaries. The research adds physical understanding of why interface chemistry can determine effective device cooling. Its immediate contribution is to process design and thermal measurement rather than to reported shipment volume, and customers will still require proof at the level of functioning microwave transistors. Source - 22 January 2025 Adjacent materials
Element Six introduced copper-diamond thermal composite materials intended for demanding electronics cooling environments. The development demonstrates continued investment in engineered diamond thermal products, but a composite heat spreader is not itself a GaN-on-diamond transistor or wafer. Its relevance is upstream know-how that may support future integration processes, not a directly additive revenue stream for the defined semiconductor market. Source - 7 September 2026 Adjacent product
RFHIC announced DiaFlux diamond heat spreader materials for thermal management of RF devices. Such materials can improve the thermal environment of GaN amplifiers and broaden access to engineered diamond components. However, standalone heat spreaders should not be equated with active GaN layers bonded to diamond, so this announcement is evidence of adjacent supply-chain development rather than verified integrated-wafer sales. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Context | 2020–2024 |
| Market Size 2025 | USD 84.93 million |
| Market Size 2026 | USD 100.19 million |
| Market Size 2034 | USD 375.73 million |
| Growth Rate | CAGR of 18.0% over 2025–2034 |
| Unit | Revenue (USD million) |
| Segmentation | By Type, By Application, By End User, and By Region |
| By Type | 2-inch Wafers · 4-inch Wafers · 6-inch Wafers · Others |
| By Application | Aerospace and Military · Automobile · Communication Network · Others |
| By End User | Semiconductor Foundries · RF Component Manufacturers · Defense Contractors · Telecom Infrastructure Providers |
| By Region | Each region evaluated by Type, Application and End User North AmericaUnited States, Canada, Mexico EuropeUnited Kingdom, Germany, France, Rest of Europe Asia-PacificJapan, China, South Korea, India, Rest of Asia-Pacific South AmericaBrazil, Argentina, Chile, Rest of South America Middle East & AfricaUnited Arab Emirates, Saudi Arabia, South Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Akash Systems, Element Six, Sumitomo Electric Industries, RFHIC Corporation, Qorvo, MACOM Technology Solutions, Mitsubishi Electric, Coherent Corp., Diamontronics, Wolfspeed |
| Customization Scope | Country-level and device-architecture customization, including qualification requirements, wafer diameter, thermal-interface technology and end-user procurement pathways. |
Frequently Asked Questions
How large is the gallium nitride on diamond market?
The global market is valued at USD 84.93 million in 2025 and is projected to reach USD 375.73 million by 2034, reflecting an 18.0% CAGR. These values describe integrated GaN-diamond semiconductor structures and qualifying devices, including early pilot sales. They should not be combined with the larger standalone diamond heat spreader market or with revenue from complete communications systems.
What makes diamond attractive for GaN transistors?
GaN devices can generate concentrated heat near high-field regions during microwave operation. Diamond provides a potential high-conductivity route for moving that heat away from the active layer, reducing the need to compromise power density. The realized advantage depends on interface resistance, bonding integrity and package design, so a high diamond thermal-conductivity specification alone cannot establish a superior commercial transistor.
Which wafer diameter has the highest modeled share?
Six-inch wafers lead the modeled type allocation at ~42% in the base year, mainly because their prospective die count could improve processing economics if yield is adequate. This share is a market model, not a claim of proven industry-wide six-inch production. Two-inch experiments and planned four-inch scale-up remain important indicators of the technical work still needed to make larger formats viable.
Where are the most important applications?
Aerospace and military electronics account for the largest estimated application share at ~40%, with communication networks another important outlet. High-power radar, satellite RF payloads and compact microwave amplifiers are relevant because thermal constraints directly affect equipment architecture. Automotive and specialist industrial uses offer additional potential but face different reliability, price and qualification requirements from defense electronics.
Who purchases integrated GaN-on-diamond products?
RF component manufacturers are the largest modeled buyer class at ~42%, followed by defense contractors, semiconductor foundries and telecom infrastructure providers. The category describes the organization buying a wafer or device rather than its final end-use. Component makers frequently qualify the thermal and electrical properties first, after which systems integrators decide whether the device improves an amplifier or payload design.
Which geography leads demand?
North America has the largest modeled regional allocation at ~41% of 2025 value, reflecting its defense, satellite and heterogeneous semiconductor research activity. Asia-Pacific has a strong wafer-transfer development base, while Europe contributes diamond materials and interface science. Smaller markets are expected to participate through imported specialist RF devices and collaborative research rather than through extensive local GaN-diamond wafer fabrication.
What is the main technical commercialization barrier?
The central difficulty is achieving a reliable low-resistance interface between GaN and diamond over enough usable device area to justify production. Surface roughness, trapped voids, stress and process contamination can erode the cooling benefit. Commercial buyers need wafer maps, transistor-level measurements and environmental cycling results that demonstrate repeatability beyond an isolated successful laboratory sample.
How does the market differ from conventional GaN-on-SiC?
GaN-on-silicon-carbide is an established route for many high-power RF devices, whereas GaN-on-diamond introduces a different thermal substrate or heterogeneous packaging architecture. Diamond may offer better heat spreading in selected designs but can require more complex bonding and expensive surface preparation. The commercial decision depends on measured device and system performance relative to cost, reliability and supplier availability.
What developments show progress toward commercialization?
Research has demonstrated direct integration of nitride structures onto polished polycrystalline diamond and the use of small GaN dielets in diamond interposers. Separate work on engineered interfaces and carbide layers targets thermal resistance at the bond itself. These advances are technically meaningful, although they do not establish a common mass-production yield, a standardized device catalogue or independently audited industry shipment totals.
What is included in the market scope?
The coverage spans 2025 base-year revenue, a 2026 estimate and a 2034 forecast, with historical context from 2020 through 2024. Segmentation addresses wafer type, application, end user and five world regions. Integrated GaN-diamond wafers, die and qualifying devices are included, while standalone thermal plates, unrelated power modules and finished radio or computing systems are excluded.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF