Flexible Flat Cable (FFC) Market Insights
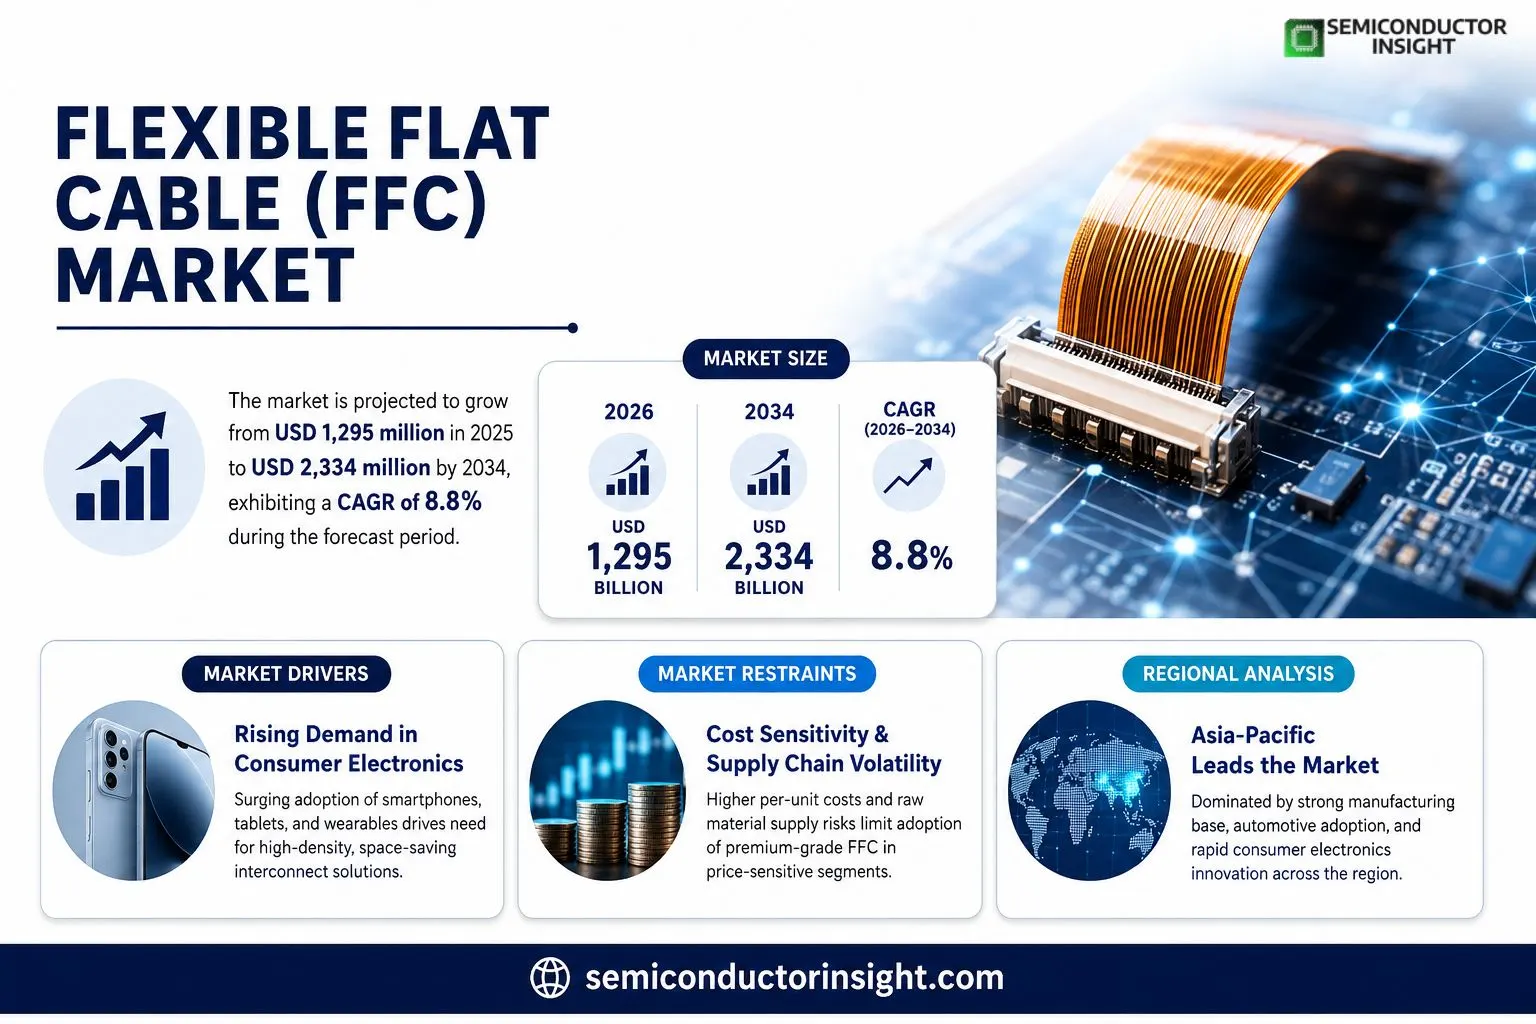
global Flexible Flat Cable (FFC) market size was valued at USD 1,295 million in 2025. market is projected to grow from USD 1,295 million in 2025 to USD 2,334 million by 2034, exhibiting a CAGR of 8.8% during forecast period.
FFC (Flexible Flat Cable) is an ultra‑thin, flexible interconnect used inside electronic devices. Its construction comprises multiple parallel flat conductors laminated between insulating films, with reinforced or plated contact pads at each end. Manufacturers promote its thinness, light weight, flexibility and high conductor density, making it suitable for board‑to‑board, board‑to‑display and inter‑module connections.market gains momentum because consumer electronics demand for slimmer form factors drives micro‑pitch and ultra‑thin designs, while automotive electrification fuels high‑speed, high‑frequency variants that support PCIe 4/5 and Gigabit Ernet. Prices for automotive‑grade FFC are three‑to‑five times higher than consumer grades, positioning this segment as primary growth engine. Chinese suppliers have leveraged cost advantages and agile supply chains to dominate consumer markets and are now expanding into automotive applications where fine‑pitch (0.3–0.5 mm) and low‑dielectric materials are critical.
MARKET DRIVERS
Rising Demand in Consumer Electronics
proliferation of smartphones, tablets, and wearables has compelled OEMs to seek interconnect solutions that combine high pin density with a slim profile. Flexible Flat Cable (FFC) technology satisfies se constraints, enabling designers to layer more functionality without increasing board thickness. This trend pushes manufacturers to expand capacity and refine material formulations, reby lowering unit cost over time.
Miniaturization Pressure in Automotive Systems
Advanced driver‑assistance systems (ADAS) and infotainment suites require thousands of signal routes within confined compartments. Engineers increasingly replace ribbon cables with flexible flat variants to meet stringent weight and space targets. As vehicle electrification matures, need for reliable, vibration‑resistant interconnects amplifies, creating a steady stream of orders for FFC market.
➤ “Design teams that prioritize flat‑cable architecture report up to a 15 % reduction in assembly time, directly translating into higher line efficiency.”
Manufacturing innovations such as laser‑cut routing and high‑temperature lamination are shortening lead times and improving yield. Companies that adopt se processes gain a competitive edge, because customers value quick turnaround as much as technical performance.
MARKET CHALLENGES
Cost Sensitivity in High‑Volume Production
While FFCs deliver design flexibility, ir per‑unit expense can exceed that of traditional round‑wire bundles, especially when exotic materials are specified for heat resistance. Price‑conscious contract manufacturers refore scrutinize bill‑of‑materials and may opt for lower‑spec alternatives, limiting premium‑segment growth.
Or Challenges
Supply‑Chain Volatility
Raw‑material pool for copper foils and dielectric films is concentrated in a handful of regions. Geopolitical tensions or logistical bottlenecks can disrupt feedstock availability, forcing buyers to lock in longer contracts at higher prices, which erodes margin flexibility.
MARKET RESTRAINTS
Stringent Qualification Requirements
Automotive and aerospace customers mandate exhaustive testing for rmal cycling, EMI shielding, and bend endurance. Meeting se standards demands extensive laboratory resources, inflating development costs for smaller suppliers and narrowing competitive field.certification timelines for safety‑critical applications often add months to product launch schedules. Companies that cannot allocate needed engineering bandwidth risk losing contracts to established players with pre‑qualified portfolios.Furrmore, emerging alternatives such as high‑speed coaxial flex circuits are beginning to carve out niche segments where ultra‑low loss is paramount, reby capping total addressable volume for conventional flat cables.
MARKET OPPORTUNITIES
Expansion into Medical Device Interfaces
medical sector is embracing minimally invasive diagnostics that rely on compact sensor arrays. Flexible flat cables offer biocompatible encapsulation and ability to route numerous signals within a single, sterilizable bundle. This creates a foothold for suppliers willing to certify products under ISO 13485.Anor promising avenue lies in industrial IoT gateways, where dense connectivity and ruggedness are prized. By pairing FFCs with flexible printed circuit boards, system integrators can deliver turnkey edge modules that fit into constrained enclosures.Finally, advent of 5G‑enabled smartphones is stimulating demand for high‑frequency, low‑profile interconnects. Vendors that tailor dielectric formulations to mitigate signal loss at millimeter‑wave bands position mselves to capture a share of this emerging vertical.
Flexible Flat Cable (FFC) Market Trends
Micro‑Pitch Ultra‑Thin Evolution
shift toward sub‑0.5 mm pitches and sub‑0.15 mm thicknesses is redefining interconnect strategies across consumer and industrial devices. Designers of foldable smartphones, augmented‑reality headsets, and true‑wireless earbuds are demanding cables that fit within ever‑tighter mechanical envelopes while preserving signal integrity. Manufacturers have responded by refining lamination processes and adopting finer copper foils, which enable higher conductor density without compromising flexibility. This engineering focus reduces overall board stack‑up height, allowing product engineers to meet aggressive form‑factor targets without resorting to costly redesigns of host chassis. For suppliers, ability to produce reliable micro‑pitch cables creates a defensible niche, as tooling investments and quality controls become barriers to entry for lower‑cost competitors. Consequently, Flexible Flat Cable (FFC) Market is witnessing a migration of capital toward firms that can guarantee ultra‑thin tolerances at volume.
Or Trends
High‑Speed, High‑Frequency Adoption
proliferation of PCIe 4.0/5.0, automotive Gigabit Ernet, and 10 Gbps+ data links is pressuring cable designers to master impedance control and dielectric loss mitigation. Low‑dielectric‑constant polymers paired with precision‑etched conductors now allow FFC solutions to support rising bandwidth demands of autonomous‑driving sensors and AI‑accelerated edge devices. From a business perspective, this transition elevates value proposition of premium‑grade cables, enabling suppliers to command higher margins while satisfying OEMs that cannot afford signal degradation in safety‑critical systems. Moreover, requirement for tighter tolerance testing has spurred collaborations between cable makers and test equipment firms, fostering an ecosystem of specialized validation services that furr differentiate market participants.
Automotive‑Grade Expansion
Electric‑vehicle battery‑management systems, domain controllers, and in‑vehicle displays are rapidly outpacing traditional consumer electronics in revenue impact. Unit prices for automotive‑qualified FFCs are three to five times those of mass‑market equivalents, reflecting rigorous reliability specifications and need for extended temperature ranges. This price premium is attracting manufacturers who have historically focused on consumer segments to re‑tool production lines for automotive certification. strategic implication for existing players is clear: firms that secure early access to automotive supply chains can leverage higher per‑unit earnings to offset modest volume decline in legacy consumer lines. Simultaneously, competitive pressure forces newcomers to accelerate compliance programs, lest y miss opportunity to become preferred suppliers in a market where vehicle integration cycles span several years.
COMPETITIVE LANDSCAPE
Key Industry Players
Flexible Flat Cable (FFC) Market – Competitive Overview
market is led by a handful of multinational manufacturers that command bulk of revenue in high‑volume consumer segments while simultaneously investing in automotive‑grade, high‑speed product lines. Sumitomo Electric, for example, leverages its deep expertise in copper processing and precision laminates to supply ultra‑thin, low‑impedance cables for foldable‑display smartphones and emerging AR/VR headsets. Its ability to scale production quickly gives it a pricing edge that smaller rivals struggle to match. Parallel to this, Johnson Electric’s Parlex division has carved out a niche in board‑to‑display interconnects, focusing on micro‑pitch offerings that meet tight spacing constraints of modern tablets. Both companies have broadened ir portfolios to include automotive‑grade variants, recognizing higher unit price and longer product cycles as a strategic hedge against volatility in consumer demand.Beyond giants, a diverse set of specialists addresses niche and high‑performance segments. Molex and Amphenol have introduced low‑dielectric, impedance‑controlled families that support PCIe 5.0 and automotive Gigabit Ernet, positioning mselves as preferred suppliers for OEMs requiring stringent signal integrity. Samtec and Würth Elektronik, while smaller in absolute volume, excel at custom‑length, high‑density solutions for industrial and aerospace applications where reliability overrides cost considerations. Asian players such as He Hui Electronics, Sumida‑flexcon, and Xinfuer Electronics dominate commodity tier, benefitting from established supply chains in China and offering rapid turn‑around for consumer‑grade orders. Meanwhile, niche innovators like Cvilux, Axon Cable, Nicomatic, JSB TECH, and Cicoil Flat Cables focus on ultra‑thin or high‑temperature variants, catering to premium wearables, medical displays, and emerging electric‑vehicle subsystems.
List of Key Flexible Flat Cable (FFC) Companies Profiled
- Sumitomo Electric
- Johnson Electric (Parlex)
- He Hui Electronics
- Molex
- Amphenol
- Samtec
- Würth Elektronik
- Sumida‑flexcon
- Cvilux
- Axon Cable
- Hitachi Metals / Proterial
- Cicoil Flat Cables
- Xinfuer Electronics
- Nicomatic
- JSB TECH
Segment Analysis:
| Segment Category | Sub-Segments | Key Insights |
| By Type |
|
Micro‑pitch Ultra‑thin FFC
|
| By Application |
|
Automotive High‑Speed FFC
|
| By End User |
|
Automotive End Users
|
| By Pitch |
|
Ultra‑fine Pitch FFC
|
| By Speed Capability |
|
High‑Speed FFC for Automotive & Telecom
|
Regional Analysis: Flexible Flat Cable (FFC) Market
surge in wearable health monitors and foldable smartphones fuels demand for ultra‑thin FFC solutions that can navigate cramped chassis. Manufacturers capitalize on se trends by prioritizing high‑frequency performance and low‑profile form factors, translating into a cascade of design‑for‑manufacturability initiatives across supply chain.
In automotive, transition to digital dashboards and advanced driver‑assistance systems compels integration of FFC assemblies that sustain high data rates under vibration. Parallelly, industrial robotics adopts flexible cables to maintain connectivity while executing complex, high‑speed motions.
Regional players have reengineered logistics by co‑locating foil‑copper lamination plants with downstream assembly hubs. This proximity curtails lead times and cushions market against raw‑material price volatility, especially for copper and high‑performance polymers.
Stricter RoHS compliance and emerging e‑waste directives push vendors toward greener adhesive chemistries. Companies that invest early in compliant formulations gain a reputational edge and smoor access to regulated export markets.
North America
North America remains a mature arena for Flexible Flat Cable (FFC) Market, where legacy defense contracts and a high concentration of aerospace OEMs sustain a steady demand for ruggedized interconnects. region’s emphasis on cybersecurity drives incorporation of shielding techniques within flat cable assemblies, enhancing data protection for critical defense platforms. Meanwhile, telecom operators accelerating 5G rollouts seek compact cabling solutions that can be densely packed into small‑cell infrastructure. This convergence of defense rigor and telecom expansion incentivizes local manufacturers to refine process controls and adopt advanced testing protocols, ensuring reliability standards meet both military and commercial expectations.
Europe
European firms differentiate mselves through a strong focus on sustainability and precision engineering within Flexible Flat Cable (FFC) Market. EU’s Green Deal incentivizes use of recyclable polymers and low‑VOC adhesives, prompting suppliers to redesign product portfolios around circular‑economy principles. In parallel, automotive sector’s shift toward electric vehicles introduces new rmal management challenges, compelling cable designers to embed heat‑dissipating layers without sacrificing flexibility. se dual pressures foster collaborative R&D consortia that merge material science expertise with automotive reliability testing, positioning Europe as a hub for high‑performance, eco‑compliant flat cable solutions.
South America
South America’s Flexible Flat Cable (FFC) Market is increasingly shaped by burgeoning consumer electronics assembly hubs in Brazil and Argentina. Local manufacturers leverage cost‑effective production techniques to serve domestic smartphone and tablet manufacturers, reducing reliance on imports. Concurrently, region’s expanding renewable‑energy projects create a niche for flat cables capable of withstanding outdoor exposure while maintaining signal integrity. This niche incentivizes manufacturers to develop UV‑stable and moisture‑resistant variants, aligning product offerings with specific climatic demands of continent.
Middle East & Africa
In Middle East & Africa, Flexible Flat Cable (FFC) Market is propelled by rapid infrastructure development and a rising appetite for smart‑city technologies. Oil‑rich economies are diversifying investments into data‑center construction, where high‑density cabling is essential for space‑constrained server farms. Additionally, telecommunications sector’s rollout of 5G across Gulf states mandates compact, high‑speed interconnects for base‑station equipment. Suppliers targeting this region prioritize robust rmal performance and resistance to dust ingress, ensuring that flat cable deployments remain reliable in harsh desert environments.
Report Scope
This market research report provides a comprehensive analysis of Flexible Flat Cable (FFC) Market , covering forecast period 2026–2034. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping industry.
Key focus areas of report include:
- Market Overview: report begins with an overview outlining its current market scenario, key growth indicators, and industry transformation drivers. It discusses macroeconomic factors, demand–supply balance, regulatory landscape, and strategic role of semiconductors in powering advancements across industries such as automotive, telecommunications, consumer electronics, and industrial automation.
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments.
- Segmentation Analysis: Detailed breakdown by product type, technology, application, and end-user industry to identify high-growth segments and investment opportunities.
- Regional Insights: Insights into market performance across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa, including country-level analysis where relevant.
- Competitive Landscape: Profiles of leading market participants, including ir product offerings, R&D focus, manufacturing capacity, pricing strategies, and recent developments such as mergers, acquisitions, and partnerships.
- Technology Trends & Innovation: Assessment of emerging technologies, integration of AI/IoT, semiconductor design trends, fabrication techniques, and evolving industry standards.
- Market Drivers & Restraints: Evaluation of factors driving market growth along with challenges, supply chain constraints, regulatory issues, and market-entry barriers.
- Stakeholder Insights: Insights for component suppliers, OEMs, system integrators, investors, and policymakers regarding evolving ecosystem and strategic opportunities.
Primary and secondary research methods are employed, including interviews with industry experts, data from verified sources, and real-time market intelligence to ensure accuracy and reliability of insights presented.
FREQUENTLY ASKED QUESTIONS:
What is current market size of Flexible Flat Cable (FFC) Market?
-> Flexible Flat Cable (FFC) Market was valued at USD 1295 million in 2025 and is expected to reach USD 2334 million by 2034.
What is projected compound annual growth rate (CAGR) for Flexible Flat Cable (FFC) Market?
-> market is projected to grow at a CAGR of 8.8% during forecast period 2025‑2034.
Which key companies operate in Flexible Flat Cable (FFC) Market?
-> Key players include Sumitomo Electric, Johnson Electric (Parlex), He Hui Electronics, Molex, Amphenol, Samtec, Würth Elektronik, Sumida‑flexcon, Cvilux, Axon Cable, Hitachi Metals / Proterial, Cicoil Flat Cables, Xinfuer Electronics, Nicomatic, and JSB TECH.
What are key growth drivers for Flexible Flat Cable (FFC) Market?
-> Key growth drivers include explosive demand from automotive applications (new‑energy vehicle BMS, ADAS, in‑vehicle displays), increasing adoption of micro‑pitch and ultra‑thin designs for foldable screens, AR/VR, wearables, and shift toward high‑speed, high‑frequency interconnects such as PCIe 4.0/5.0 and automotive Gigabit Ernet.
Which region dominates Flexible Flat Cable (FFC) market?
-> Asia dominates market, driven by strong manufacturing capacity in China and rapid adoption of automotive‑grade FFC across region.
What are emerging trends in Flexible Flat Cable (FFC) market?
-> Emerging trends include micro‑pitch (0.3‑0.5 mm) and ultra‑thin (0.10‑0.15 mm) FFCs, high‑speed/high‑frequency capabilities supporting 10 Gbps+ data rates, and growth of automotive‑grade, low‑dielectric, precise‑impedance solutions.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF