
Key Statistics
Key Takeaways
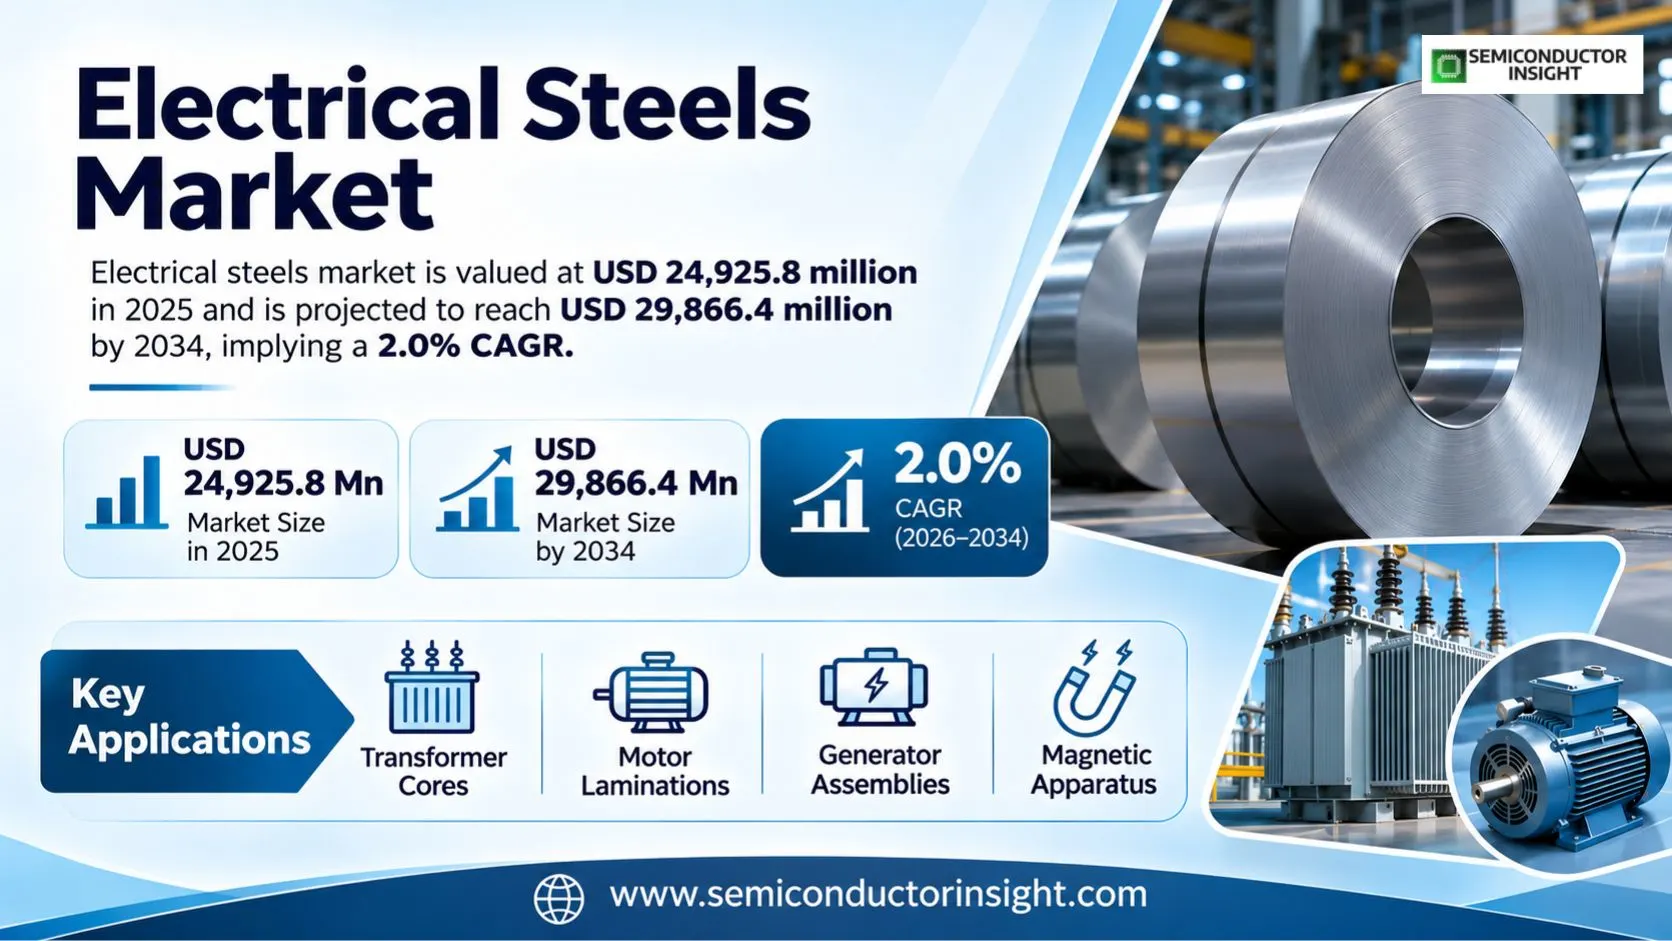
- Market trajectory: The market moves from USD 24,925.8 million in 2025 toward USD 29,866.4 million by 2034. A 2.0% CAGR connects those anchors across nine annual periods; shipments depend on qualification programs, OEM platform cycles and the reliability of technologies used in grain-oriented and non-oriented iron-silicon sheet for transformer and motor cores.
- Steel categories: Grain-Oriented Electrical Steel holds an estimated ~52% of 2025 type value, with Non-Grain-Oriented Electrical Steel representing ~48%. The former is engineered for a favorable magnetic direction in transformer cores; the latter accommodates changing magnetic fields in rotating motors. Process controls, insulation coatings and finished lamination geometry determine whether a premium steel grade actually yields lower equipment losses.
- Principal application: Transformers account for an estimated ~48% of electrical steel revenue, followed by Motors at ~31%, Generators at ~14% and other magnetic apparatus at ~7%. Transformer buyers focus on no-load loss and material availability, while motor makers compare magnetic performance over rotational speed and drive frequencies. Procurement therefore depends on the equipment architecture rather than a generic steel tonnage specification.
- Geographic balance: Asia-Pacific accounts for an estimated ~54%, reflecting electronics production, engineering facilities and supplier ecosystems. North America at an estimated ~16% and Europe at an estimated ~24% play important roles in specification, procurement and specialist equipment programs.
- Manufacturing challenge: Low-loss silicon steel requires controlled rolling texture, heat treatment and insulation coatings that can be damaged by poorly managed slitting or stamping. Very thin sheet may reduce losses in high-frequency machines, but processing cost and mechanical yield rise as gauges become demanding. Manufacturers must validate the completed core or stator stack before promising an equipment-efficiency benefit to customers.
Electrical Steels Market Overview
Electrical steels market is valued at USD 24,925.8 million in 2025 and is projected to reach USD 29,866.4 million by 2034, implying a 2.0% CAGR. The market covers specialty rolled silicon-steel sheet sold for transformer cores, motor laminations, generator assemblies and related magnetic apparatus; excludes finished machines, grid installations and ordinary structural steel; purchasing decisions combine component functionality, development resources and verified integration performance.
For 2026 purchasing, electrical steel is a specialized iron-silicon sheet engineered to carry magnetic flux with manageable energy loss in transformers, motors and generators. Its commercial value depends on magnetic performance after a coil has been slit, punched and assembled into a working core. Looking toward 2034, commodity structural steel cannot substitute merely because it has similar thickness or metallic composition. Magnetic loss characteristics, coating integrity and approved production quality therefore determine the applicable market boundary.
For 2026 purchasing, grain-oriented material provides a favorable direction for flux in stationary transformer cores, while non-oriented sheet responds to fields that rotate in electrical machinery. The manufacturing route changes the sheet texture and magnetic properties through controlled rolling and heat treatment. Looking toward 2034, equipment designers consider the operating frequency, lamination gauge and assembly stress when choosing a grade. The intended technical benefit must remain measurable once individual sheets have been stacked and connected within a finished product.
For 2026 purchasing, this report includes revenue from electrical steel sheet sold for magnetic cores, including relevant specialty grades used in power equipment, motors, generators and other electromagnetic apparatus. It excludes complete transformers, finished traction motors, grid construction contracts and unrelated structural metal purchases. Looking toward 2034, this distinction matters because the market for a complete electrical machine incorporates copper windings, insulation, enclosures and extensive assembly activity in addition to its sheet-steel inputs.
For 2026 purchasing, the longer-term opportunity is influenced by electrical efficiency standards, vehicle electrification and manufacturing investment, although replacement cycles differ sharply among industries. Advanced low-loss steel may reduce operating cost over time, but its availability and processing characteristics affect equipment economics. Looking toward 2034, purchasing teams balance mill capability, expected sheet loss after fabrication and stable supply before upgrading a proven machine design. The resulting market does not rise automatically in line with total electricity expenditure.
Segment Analysis: By Type
Electrical steel sheet is principally divided by crystallographic texture. Grain-Oriented Electrical Steel, with an estimated ~52% of 2025 value, favors magnetic conduction along its rolling direction and serves transformers. Non-Grain-Oriented Electrical Steel, at approximately ~48%, suits rotating machinery where flux direction varies. Differences in core loss, silicon content, sheet thickness and coating insulation determine how the material performs after it has been processed into a functional core.
| Type | Function | Market position |
|---|---|---|
| Grain-Oriented Electrical Steel (GOES) | Type position: an estimated ~52% of 2025 demand. For 2026 design programs, Grain-oriented steel is processed to give strong magnetic performance along the rolling direction, making it especially useful in power and distribution transformer cores. Manufacturers manage crystal texture, insulation coating and magnetic domain behavior to lower no-load losses. By 2034, core builders must also control cutting, joints and clamping, since these operations can prevent a premium sheet from delivering its expected benefit. | For 2026 purchasing, gOES economics reflect the value of magnetic loss reduction over a transformer’s service life and the limited manufacturing capability needed for advanced grades. Utilities may approve a higher sheet price when efficiency improvements justify it, but trade restrictions and availability can influence purchasing. Looking toward 2034, supplier qualification requires test results at specified induction and frequency, not just confirmation that a coil is labeled grain oriented. |
| Non-Grain-Oriented Electrical Steel (NGOES) | Type position: an estimated ~48% of 2025 demand. For 2026 design programs, Non-oriented sheet is produced to provide useful magnetic characteristics across directions, supporting motors, generators and other rotating equipment. Grade selection weighs thickness, permeability, saturation and loss under different excitation frequencies. By 2034, the material must also survive punching and stacking while preserving an electrically insulating coating between laminations, which helps prevent unintended circulating currents. | For 2026 purchasing, motor makers purchase NGOES in grades matched to efficiency targets, speed and mechanical production constraints. Automotive applications may accept thin low-loss steel at higher price, whereas conventional industrial drives can be more sensitive to stamping cost. Looking toward 2034, the supplier’s role includes consistency of magnetic properties and coil handling so the finished stator performs predictably rather than simply meeting a nominal chemical specification. |
Segment Analysis: By Application
Transformer cores constitute an estimated ~48% of 2025 electrical steel applications, while Motors contribute ~31%, Generators ~14% and Others ~7%. The first group favors oriented sheet and low continuous no-load losses; rotating machines typically rely on non-oriented magnetic steel that operates across varying flux directions. Material selection must consider both energy efficiency and the cost of manufacturing reliable laminated equipment.
| Application | Demand characteristics |
|---|---|
| Transformers | Application share: an estimated ~48% in 2025. For 2026 design programs, Power and distribution transformers use grain-oriented laminations to guide alternating magnetic flux through a low-loss path. The steel’s grade influences continuous core losses, but assembly joints, clamping and insulation also affect results. By 2034, utilities purchasing efficient equipment often evaluate operating costs over years, making consistent magnetic behavior and reliable sourcing commercially important. |
| Motors | Application share: an estimated ~31% in 2025. For 2026 design programs, Automotive traction and industrial motors rely on non-oriented steel stacked into stator and rotor structures. High-speed designs increase sensitivity to core loss at elevated frequencies, potentially favoring thin, carefully processed sheets. By 2034, cutting strain, coating durability and stacking factor can erode an apparent benefit, so designers compare actual motor performance after fabrication. |
| Generators | Application share: an estimated ~14% in 2025. For 2026 design programs, Generators convert mechanical input into electricity through laminated magnetic paths that must limit heating and maintain predictable flux behavior. Grade decisions consider machine rating, frequency and processing conditions. By 2034, large equipment buyers may value stable supplier quality and usable coil widths as much as a small loss improvement, because manufacturing disruptions can delay complete generator delivery. |
| Others | Application share: an estimated ~7% in 2025. For 2026 design programs, Reactors, measurement transformers and specialist electromagnetic components use electrical steel with tailored magnetic and geometric requirements. Their volumes can be smaller than the major transformer and motor industries, yet material qualification remains demanding. By 2034, designers assess actual flux direction and available processing methods before deciding whether oriented or non-oriented sheet is the better economic choice. |
Regional Analysis
Asia-Pacific leads global electrical steel demand at an estimated ~54% of the 2025 market, supported by transformer manufacturing, industrial motors and vehicle electrification. Europe contributes approximately ~24%, reflecting sophisticated magnetic steel and equipment supply, while North America accounts for around ~16%. These regional proportions reflect the sales location of electrical steel products; a transformer can use imported core sheet and then be assembled closer to its final grid installation.
Where do transformer and motor producers purchase the most electrical steel sheet?
Electrical steels are specified according to magnetic loss, permeability, thickness and the direction of magnetic flux in the finished machine. Grain-oriented sheet serves transformer cores, whereas non-grain-oriented sheet serves motors and generators requiring changing flux orientation. Regional purchase preferences depend on access to precision rolling and annealing equipment, acceptable core-loss grades and the economics of transformer or motor production. Broad electricity infrastructure spending must not be equated with sheet-steel purchases.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | An estimated ~54% | ~2.3% CAGR | electronics fabrication, substrate factories, smartphone assembly and automotive component exports | Factory release documentation and verified application engineering |
| North America | An estimated ~16% | ~1.8% CAGR | platform architecture, integrated-circuit engineering and cross-border manufacturing | Qualified supply assurance and verified application engineering |
| Europe | An estimated ~24% | ~1.8% CAGR | automotive certification, machine safety and industrial development | Reliability verification and verified application engineering |
| South America | An estimated ~4% | ~1.7% CAGR | localized electronics manufacturing and industrial equipment modernization | Import and service continuity and verified application engineering |
| Middle East & Africa | An estimated ~2% | ~1.5% CAGR | infrastructure equipment, telecom deployment and industrial digitalization | Long-life vendor support and verified application engineering |
Key Electrical Steels Manufacturers and Competitive Landscape
For 2026 purchasing, electrical steel competition includes integrated steel groups and specialist rolling operations with different grade capabilities. China Baowu, Nippon Steel, JFE Steel, POSCO, thyssenkrupp, voestalpine and Cleveland-Cliffs participate in relevant magnetic sheet supply. Looking toward 2034, differences in rolling texture, heat treatment, coating and available gauge matter more to a transformer or motor buyer than a producer’s overall output of general construction steel. Supplier evaluation should focus on current facilities and documented magnetic products.
For 2026 purchasing, joint development between a steel mill and an electrical equipment maker can improve the use of premium magnetic grades. Motor engineers assess how slitting, stamping and assembly alter loss behavior, while transformer manufacturers refine core joints and insulation. Looking toward 2034, these collaborations require measured performance under realistic processing conditions rather than a supplier claim based entirely on an unworked strip sample. Grade selection can have a lasting influence on finished-equipment efficiency and cost.
For 2026 purchasing, current ownership and operating status matter in a market where plant shutdowns or changes in trade protection affect access to specialty grades. Purchasers should verify which company currently sells a qualified steel and whether the relevant rolling line is active. Looking toward 2034, a distributor may provide traceable coils without producing the original magnetic sheet. Long-term supplier relationships depend on consistent steel quality, delivery discipline and support when an equipment customer changes core geometry.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Core suppliers | China Baowu Steel Group; Nippon Steel; JFE Steel; POSCO | Core suppliers produce grain-oriented and non-oriented magnetic sheet with defined losses, gauges and insulation coatings. Customers choose these mills for the ability to supply repeatable grades that work within a qualified transformer or motor production line. Contract terms may specify acceptance testing at defined frequencies and flux densities, along with notification when the steelmaking or annealing route is modified. |
| Specialist and adjacent suppliers | thyssenkrupp Electrical Steel; voestalpine; ArcelorMittal; Cleveland-Cliffs; Tata Steel; China Steel Corporation | Specialist firms may focus on advanced low-loss grades, regional coil conversion or downstream lamination manufacturing. Their relevance depends on the actual magnetic material and processing service delivered, not merely on proximity to vehicle or utility equipment customers. A company selling finished transformer cores should be distinguished from the upstream mill when estimating the value attributable to sheet steel. |
Key companies profiled
- China Baowu Steel Group
- Nippon Steel
- JFE Steel
- POSCO
- thyssenkrupp Electrical Steel
- voestalpine
- ArcelorMittal
- Cleveland-Cliffs
- Tata Steel
- China Steel Corporation
Electrical Steels Production Capacity Analysis
For 2026 purchasing, production capacity for electrical steels depends on steelmaking, silicon alloy control, specialized rolling lines, annealing furnaces and coating equipment capable of meeting magnetic specifications. General sheet-steel capacity is not a reliable substitute for this measure because grain-oriented products require demanding texture engineering. Looking toward 2034, the economically useful capacity is material that consistently passes designated core-loss and insulation tests at the required gauge, with acceptable yield through customer slitting or stamping.
(‘Magnetic steel production’, ‘For 2026 purchasing, steelmakers control chemical composition before hot and cold rolling, carefully selected heat treatment and application of insulating coatings. Grain-oriented products require a strong preferred magnetic texture, while non-oriented grades emphasize appropriate response across changing directions. Looking toward 2034, small process changes can affect losses even when the sheet appears visually identical. Mills therefore need rigorous inspection and certification of finished coils before offering them for regulated or high-efficiency machines.’)
(‘Mill capacity and sourcing reliability’, ‘For 2026 purchasing, producing the thinnest or most efficient steel grades may involve lower yields and longer processing times than ordinary industrial sheet. Capacity expansion requires trained operations, qualified annealing equipment and a dependable customer base. Looking toward 2034, equipment makers may need to approve a new rolling line or alternate mill before accepting its material. These qualification costs and trade conditions influence available supply across the forecast horizon, separate from nominal crude-steel production.’)
Electrical Steels Market Dynamics: Drivers, Restraints and Opportunities
For 2026 purchasing, electrical steel demand is supported by efficient power conversion, transformer replacement and increasing sophistication in electric motors. Expansion is tempered by the capital intensity of specialty rolling and heat treatment, international trade conditions and the cost of processing thin gauges. Looking toward 2034, low core loss creates value over a machine’s operating lifetime, but a steel mill can capture that value only when its sheet can be cut, stacked and supplied reproducibly to qualified manufacturers.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Customer miniaturization and integration | High | +0.96% | High | High | High |
| Platform capability upgrades | Medium-High | +0.64% | High | High | High |
| Industrial and automotive qualification | Medium | +0.52% | Medium | High | High |
| Materials and engineering improvements | Low-Medium | +0.28% | Medium | Medium | Medium |
| Others (application diversification) | Low | +0.20% | Medium | Medium | Medium |
Distribution transformer efficiency and replacement
For 2026 purchasing, utilities replacing aging transformer assets can prefer grades that lower continuous core loss, particularly where electricity is expensive or efficiency requirements tighten. Grain-oriented sheet contributes to the design, provided the transformer core is assembled with appropriate joints and clamping. Looking toward 2034, this demand mechanism is closely linked to equipment replacement schedules rather than the headline size of an entire grid modernization program.
Electrification and traction motor manufacturing
For 2026 purchasing, electric vehicle drives and industrial motor electrification create demand for non-oriented electrical steels with controlled loss at operational frequencies. Higher-speed motors may benefit from thinner laminations and improved magnetic characteristics, but production must remain economical. Looking toward 2034, steelmakers collaborating with motor builders can improve grade adoption by providing stamping guidance and predictable batch quality.
Industrial energy-efficiency investment
For 2026 purchasing, manufacturers investing in lower-loss pumps, compressors and generators may select efficient magnetic core material as part of a redesigned machine. Sheet grade improvements can lower running losses when matched to actual flux and thermal conditions. Looking toward 2034, the commercial decision still involves motor size, duty cycle and capital cost, so steel demand responds to concrete equipment projects rather than to generalized efficiency policy alone.
Advanced sheet grades and coating processes
For 2026 purchasing, improved texture control, insulation coating and annealing methods support lower losses and better performance in transformer or motor cores. Specialty producers can earn additional value by supplying demanding grades that process reliably into thin laminations. Looking toward 2034, practical gains depend on finished-equipment tests because cutting strain and mechanical assembly can raise losses above those observed in an unprocessed strip.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| High development and process qualification cost | High | -0.32% | High | Medium | Medium |
| Engineering complexity and specialist labor | Medium | -0.18% | Medium | Medium | Medium |
| Others (supplier and materials constraints) | Low | -0.10% | Medium | Medium | Low |
Energy-intensive rolling and production costs
For 2026 purchasing, electrical steels depend on demanding rolling, annealing and coating operations, with energy costs influencing the economics of advanced grades. Producing thinner sheet or tightly controlled texture can require additional process steps and reduce usable yield. Looking toward 2034, equipment buyers may delay switching to a premium grade when the added upfront expenditure cannot be recovered during the machine’s expected operating life.
Supply concentration and qualification delays
For 2026 purchasing, only a limited set of mills can produce the highest-performing transformer and motor grades at reliable scale. A customer changing suppliers may need new magnetic tests and adjustments to its slitting or core assembly line. Looking toward 2034, import restrictions, production interruptions or long lead times can therefore delay equipment orders even where the nominal amount of available steel appears adequate.
Others (processing and grade availability)
For 2026 purchasing, magnetic properties can deteriorate during stamping, welding, insulation damage or improper stacking of electrical steel laminations. Specialty grades may also have constraints on sheet width, minimum order quantities and delivery scheduling. Looking toward 2034, these practical issues discourage unnecessary redesigns and can leave some customers using a familiar grade despite opportunities for modest efficiency improvement.
MARKET OPPORTUNITIES
Advanced traction motor steels
For 2026 purchasing, automotive manufacturers exploring higher-speed or more compact motors can benefit from lower-loss non-oriented sheet and careful lamination design. Steel producers may participate in joint development with winding and motor specialists. Looking toward 2034, commercial adoption depends on proving that grade improvements survive stamping and production handling, and that the final motor achieves a meaningful benefit within the vehicle platform’s cost targets.
Grid transformer supply resilience
For 2026 purchasing, utilities and transformer manufacturers may seek greater continuity of grain-oriented steel through stable contracts or qualified regional sourcing. Suppliers that can demonstrate reliable core-loss performance and predictable delivery of demanding grades may secure repeat orders. Looking toward 2034, improved supply assurance adds value even when the material’s magnetic specification changes little, because grid projects are sensitive to equipment manufacturing delays.
Low-loss industrial machine redesigns
For 2026 purchasing, motor and generator manufacturers updating older equipment platforms can evaluate improved silicon steel alongside winding, control and cooling changes. A suitable grade can reduce heat and operating losses, especially in heavily utilized machinery. Looking toward 2034, suppliers offering measured magnetic behavior after realistic cutting and stacking can help customers judge the upgrade and avoid paying for properties that cannot be used effectively.
Electrical Steels Supply Chain Analysis
For 2026 purchasing, the electrical steel supply chain starts with iron and silicon-containing metal inputs, then moves through precise melting, rolling, annealing and insulation coating. Coil converters slit or stamp laminations, and transformer or motor factories stack those pieces into an electromagnetic core. Looking toward 2034, magnetic losses are affected by many of these operations, requiring quality data to follow the material from the steel mill into finished machinery. Purchasers cannot judge the entire chain from sheet thickness alone.
Steel chemistry and input quality. For 2026 purchasing, production begins with carefully controlled steel chemistry and silicon additions that influence magnetization and processing behavior. Impurity management, casting stability and appropriate hot rolling establish the conditions for later magnetic texture development. Looking toward 2034, mills use metallurgical tests and process records to ensure consistent results, because a change at this upstream stage may create a loss problem that only emerges after expensive cold rolling and annealing.
Rolling and lamination conversion. For 2026 purchasing, cold rolling, annealing and coating create the physical and magnetic properties of finished electrical sheet. Downstream manufacturers then slit coils and punch laminations for a particular transformer or motor design. Looking toward 2034, cutting stress and coating damage can raise electrical losses or reduce stacking quality. Coordination between a steel producer and core fabricator allows a low-loss grade to retain its technical benefit in real production.
Equipment procurement channels. For 2026 purchasing, transformer and motor companies purchase magnetic sheet against detailed standards covering thickness, induction, core loss and surface insulation. A mill certificate is important but may not capture additional damage caused during customer stamping and assembly. Looking toward 2034, buyers often demand traceable coil lots and review alternative supplier grades before placing large orders. An apparently equivalent steel designation can still require fresh testing for a specific machine platform.
Maintenance and replacement supply. For 2026 purchasing, utilities and industrial users operate electrical machines for many years, creating demand for dependable replacement components and qualified steel grades. When an established mill or coating system changes, equipment producers must decide whether an alternate sheet preserves the original core performance. Looking toward 2034, a coordinated change-control process and retained test records can reduce redesign cost while helping service organizations maintain machine efficiency and reliability.
Recent Developments in the Electrical Steels Market
- September 2026 EU TRANSFORMER STEEL SAFEGUARDS
thyssenkrupp reported preliminary European safeguard measures concerning grain-oriented electrical steel during September 2026. These trade changes highlight the importance of reliable GOES supply for transformer manufacturers and the tension between regional production economics and competitive imports. A safeguard announcement can influence sourcing plans but does not itself demonstrate a proportional increase in worldwide magnetic steel shipments. Source - June 2026 HIGH-SILICON MOTOR STEEL RESEARCH
POSCO described a research effort with Hyundai Motor and other partners in June 2026 involving electrical steel with 6.5% silicon for future vehicle motors. Higher silicon can affect magnetic performance while complicating sheet workability, making this a significant materials engineering objective. The program concerns development and qualification rather than proof that its proposed composition has already become a standard high-volume automotive grade. Source - June 2026 US TRANSFORMER SUPPLY ASSESSMENT
The US Department of Energy issued a June 2026 information request about distribution transformer energy standards and domestic materials supply. The initiative illustrates policy attention to transformer availability, equipment losses and core steel sourcing. It is a regulatory and supply-chain event, not a direct disclosure of electrical steel purchases, and the ultimate market response will depend on manufacturing investment and equipment procurement decisions. Source - March 2026 EU ELECTRICAL STEEL CAPACITY PRESSURE
Industry reporting in March 2026 described changes to thyssenkrupp grain-oriented steel operations at Isbergues against a backdrop of pricing and import pressures. Such events can change access to specialty grades for regional transformer builders even when global production continues. Equipment makers should verify current supply options and product approvals before substituting grades or relying on historical mill capacity statements. Source - April 2024 DISTRIBUTION TRANSFORMER EFFICIENCY RULES
The US Department of Energy finalized distribution transformer efficiency standards in April 2024, with compliance requirements intended for a later implementation period. The rules connect equipment performance with the properties of transformer core constructions, including grain-oriented steel. They do not determine global electrical steel revenue on their own, since equipment design, procurement timing and alternate manufacturing choices mediate the final steel demand. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Year | 2034 |
| Base Market Value | USD 24,925.8 million |
| Forecast Market Value | USD 29,866.4 million |
| Forecast CAGR | 2.0% |
| Revenue Coverage | specialty rolled silicon-steel sheet sold for transformer cores, motor laminations, generator assemblies and related magnetic apparatus; excludes finished machines, grid installations and ordinary structural steel |
| Largest Region | Asia-Pacific (~54%) |
| Currency | USD million |
| Geographic Scope | Global |
| By Type | Grain-Oriented Electrical Steel (GOES); Non-Grain-Oriented Electrical Steel (NGOES) |
| By Application | Transformers; Motors; Generators; Others |
| By End User | Power & Energy Sector; Automotive Industry; Industrial Machinery |
| By Grade | Conventional Grades; High Permeability Grades; Low Core Loss Grades |
| By Magnetic Property | High Permeability; Low Core Loss; High Saturation Induction |
| By Region | Five geographic markets assessed with named countries, purchasing conditions and relevant electronic applications. Asia-PacificChina, Japan, South Korea North AmericaUnited States, Canada, Mexico EuropeGermany, France, United Kingdom South AmericaBrazil, Argentina, Chile Middle East & AfricaSaudi Arabia, United Arab Emirates, South Africa |
| Key Companies Profiled | China Baowu Steel Group; Nippon Steel; JFE Steel; POSCO; thyssenkrupp Electrical Steel; voestalpine; ArcelorMittal; Cleveland-Cliffs; Tata Steel; China Steel Corporation |
| Customization Scope | Additional breakouts can examine grain-oriented and non-oriented iron-silicon sheet for transformer and motor cores, qualified platform revisions, packaging or security subfunctions, application reliability and procurement needs through 2034. |
Frequently Asked Questions
How large is the global electrical steels market?
For 2026 purchasing, the 2025 base value is USD 24,925.8 million and the 2034 forecast reaches USD 29,866.4 million, an endpoint-derived 2.0% annualized increase. The revenue object is rolled magnetic sheet used in transformer, motor and generator cores. Looking toward 2034, complete electrical machinery and grid installation contracts remain separate, even though their performance and manufacturing schedules influence demand for the steel input.
What is covered by the electrical steels market?
For 2026 purchasing, this market covers grain-oriented and non-oriented silicon steel sheet manufactured for magnetic cores in transformers, motors, generators and related electrical equipment. The products are sold as specialized steel materials with defined magnetic characteristics. Looking toward 2034, the value of complete machinery, transmission networks, copper windings and ordinary structural steel is excluded, even though these industries influence sheet purchases through equipment demand.
Which electrical steel type has the largest share?
For 2026 purchasing, grain-Oriented Electrical Steel accounts for an estimated ~52% of the 2025 market, reflecting its role in transformer cores. Non-Grain-Oriented Electrical Steel contributes approximately ~48%, largely through motors, generators and other rotating machinery. Looking toward 2034, their relative positions depend on grade requirements and equipment purchasing, and the two products should not be regarded as interchangeable when magnetic flux follows different paths.
Where does electrical steel demand concentrate?
For 2026 purchasing, asia-Pacific accounts for an estimated ~54% of 2025 sales, supported by manufacturing of electrical equipment and specialty magnetic sheet. Europe represents around ~24% and North America about ~16%. Looking toward 2034, material may be rolled in one country and assembled into a motor or transformer in another, so buyers should distinguish the location of steel sales from the site of final grid or vehicle use.
What encourages manufacturers to use lower-loss sheet?
For 2026 purchasing, transformer owners can benefit from reducing constant core losses over a long service period, while industrial and traction motor designers aim to limit losses under varying speed and frequency. A premium sheet grade is worthwhile when its energy-efficiency value exceeds the additional cost of manufacturing and qualification. Looking toward 2034, equipment tests are necessary because cutting and assembly stress can change the final magnetic performance.
What can slow advanced electrical steel adoption?
For 2026 purchasing, specialty rolling and annealing are capital intensive, and production of thin or demanding magnetic grades can have yield constraints. A customer switching mills may need to adapt core fabrication tools and repeat loss measurements. Looking toward 2034, supply concentration and international trade measures also create uncertainty, particularly for grain-oriented steel used in transformers with strict efficiency requirements.
Which industries are key electrical steel customers?
For 2026 purchasing, transformer manufacturers, industrial motor producers, automotive drive suppliers and generator builders form the principal equipment customer groups. Each has a distinct magnetic duty: stationary cores favor oriented sheet, while rotating machinery generally needs non-oriented grades. Looking toward 2034, specifications differ in thickness, loss, mechanical processing and insulation, so steel purchasing must follow the intended machine design and operating environment.
Which producers supply electrical steel grades?
For 2026 purchasing, important magnetic steel manufacturers and groups include China Baowu, Nippon Steel, JFE Steel, POSCO, thyssenkrupp, voestalpine and Cleveland-Cliffs, among other regionally relevant mills. Product ranges and current operating sites vary across these firms. Looking toward 2034, buyers should verify the active producer of a qualified grade and avoid counting historical brands as separate independent suppliers where ownership has changed.
Why does the processing of electrical steel affect its magnetic performance?
For 2026 purchasing, rolling texture, annealing and insulation coatings give electrical steel the properties required by particular magnetic cores. Cutting, punching or joining the sheet can introduce stress and disturb those properties, sometimes increasing losses above the supplier’s strip-test value. Looking toward 2034, machine makers therefore validate the finished lamination stack and the actual device operating frequency rather than selecting a grade on published data alone.
How should buyers interpret the electrical steels forecast?
For 2026 purchasing, the forecast describes value of magnetic sheet sales from the 2025 base through 2034, rather than all spending on electricity generation, grid equipment or motorized vehicles. Growth will depend on efficient transformer and motor designs as well as steel supply and manufacturing economics. Looking toward 2034, procurement teams still need to monitor current grade availability, validated processing results and the costs of switching mills.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF