SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

DRAM for Data Centers Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
EMBEDDED SYSTEMS Semiconductor Market Research

DRAM for Data Centers Market

Size, Share & Industry Analysis, By Type (UDIMM, SODIMM, RDIMM, MRDIMM, LRDIMM, Others), By Application (Internet Data Centers, Enterprise Data Centers, Edge Data Centers, AI/HPC Clusters), By Memory Generation (DDR4, DDR5, DDR5 MRDIMM/Higher-Speed), By End User (Cloud Service Providers, Hyperscalers, Enterprises, Telecom Operators), and Regional Forecast, 2026-2034

◷
UPDATED 06 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE d41bb5340f7a
▯
FORMATS PDF

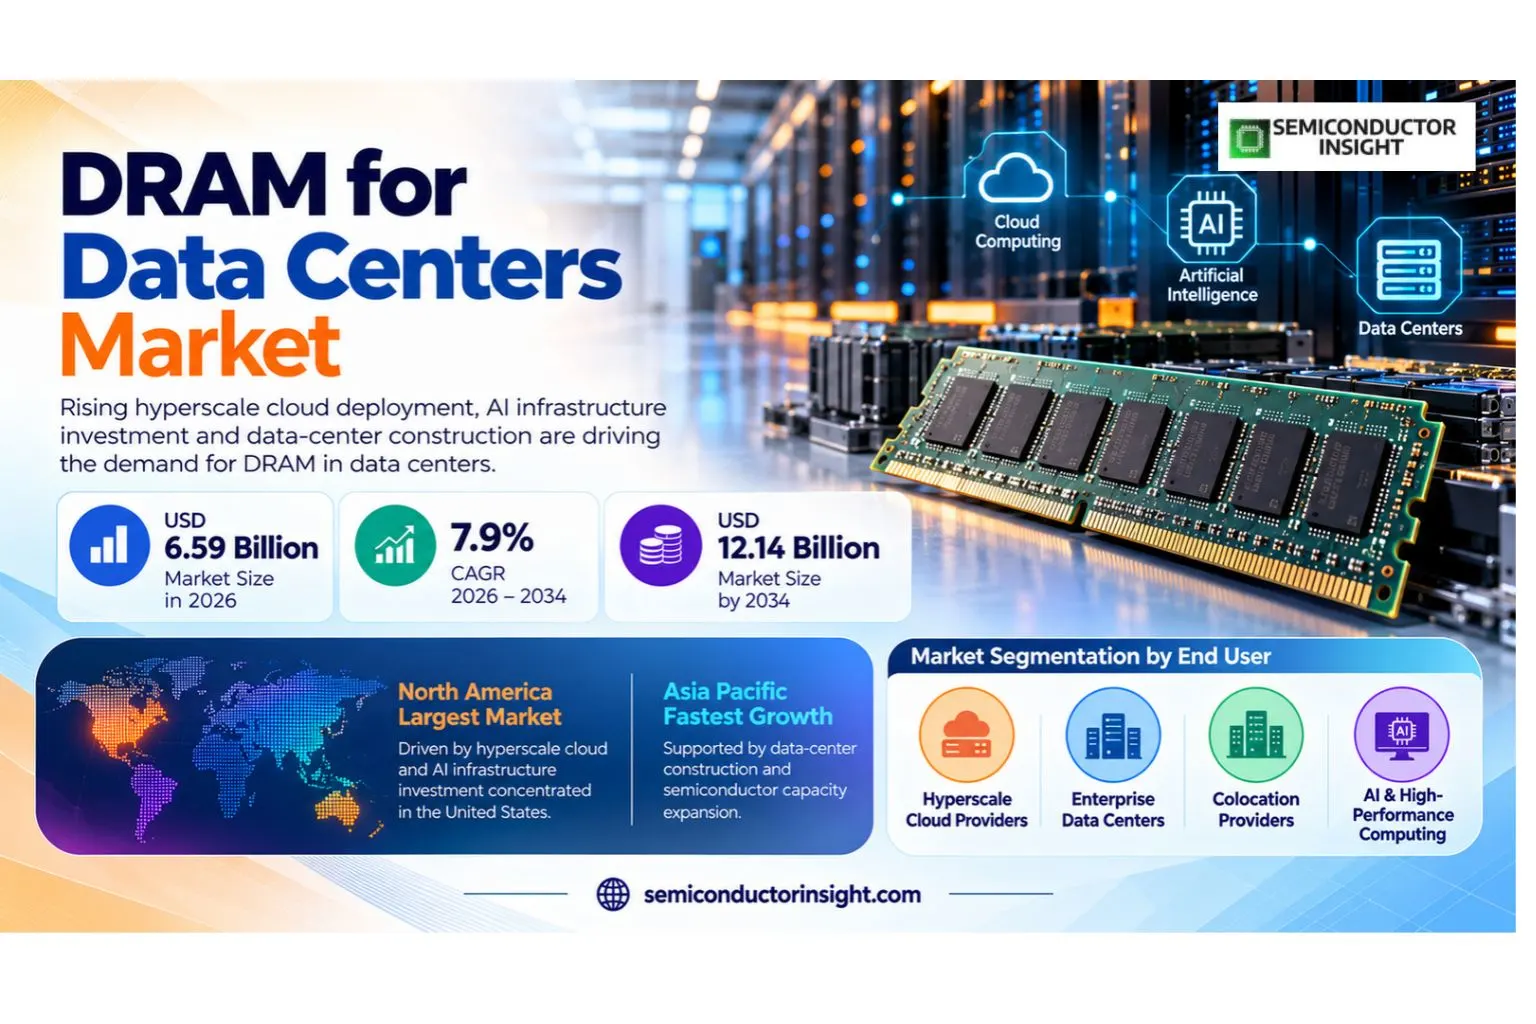
DRAM for data centers market is valued at USD 6.11 billion in 2025 and is projected to reach USD 12.14 billion by 2034, expanding at a 7.9% CAGR during 2026–2034. The 2026 market level is USD 6.59 billion. North America is used as the largest current market because hyperscale cloud and AI infrastructure investment is concentrated in the United States. Asia Pacific is the fastest-growth region through data-center construction and semiconductor capacity.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 6.11 billion
2034 Projected Market Size
USD 12.14 billion
CAGR (2026–2034)
7.9%
Largest Market in 2025
North America

Key Takeaways

  • Market size: The market is valued at USD 6.11 billion in 2025 and is projected to reach USD 12.14 billion by 2034, representing a 7.9% CAGR during 2026–2034.
  • UDIMM is a leading segment, reflecting broad use across the largest volume applications.
  • North America leads the market, while Asia Pacific provides the strongest growth profile.
  • Internet Data Centers is a major application, supported by rising performance and reliability requirements.
  • DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server is becoming a central competitive differentiator as customers seek higher performance and lower system-level cost.

DRAM for Data Centers Market Overview

DRAM for data centers market is valued at USD 6.11 billion in 2025 and is projected to reach USD 12.14 billion by 2034, expanding at a 7.9% CAGR during 2026–2034. The 2026 market level is USD 6.59 billion. North America is used as the largest current market because hyperscale cloud and AI infrastructure investment is concentrated in the United States. Asia Pacific is the fastest-growth region through data-center construction and semiconductor capacity.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values stated in U.S. dollars

DRAM for Data Centers products provide a critical functional layer inside modern electronic and industrial systems. Their commercial value depends on performance, reliability, manufacturability, qualification and compatibility with the broader hardware architecture. Customers increasingly assess total system impact rather than component price alone, which favors suppliers that combine proven technology with consistent global support.

Technology development is focused on ddr5 bandwidth scaling, mrdimm adoption and higher memory capacity per ai server, tighter integration and more automated manufacturing. These trends raise the value of precision process control and application engineering because smaller geometries, higher data rates or greater power density leave less margin for variation. Qualification therefore becomes a major barrier to entry in premium applications.

Commercial competition combines scale with specialization. Large suppliers benefit from purchasing power, engineering resources and global manufacturing, while specialist vendors can win through process expertise or application-specific performance. Design wins are often durable because changing suppliers can require requalification of electrical, thermal, mechanical or reliability performance. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Segment Analysis: By Type

By type, the market is segmented into UDIMM, SODIMM, RDIMM, MRDIMM, LRDIMM, Others. Product selection depends on performance, cost, manufacturing complexity and the target system architecture. Higher-value variants generally offer tighter tolerances, greater integration or improved reliability, while mainstream categories retain volume leadership because of lower cost and broad compatibility.

Type Commercial role
UDIMM UDIMM serves a distinct portion of the DRAM for Data Centers market based on performance, cost and integration requirements.
SODIMM SODIMM serves a distinct portion of the DRAM for Data Centers market based on performance, cost and integration requirements.
RDIMM RDIMM serves a distinct portion of the DRAM for Data Centers market based on performance, cost and integration requirements.
MRDIMM MRDIMM serves a distinct portion of the DRAM for Data Centers market based on performance, cost and integration requirements.
LRDIMM LRDIMM serves a distinct portion of the DRAM for Data Centers market based on performance, cost and integration requirements.
Others Others serves a distinct portion of the DRAM for Data Centers market based on performance, cost and integration requirements.

Additional Segmentation: By Memory Generation

Memory Generation segmentation highlights important technical or commercial differences inside the DRAM for Data Centers market. These categories affect pricing, qualification, process requirements and customer fit, making them useful for evaluating where value growth differs from simple unit growth. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Memory Generation Demand characteristics
DDR4 Large installed base across mature server platforms.
DDR5 Mainstream growth platform for modern x86 and Arm servers.
DDR5 MRDIMM / Higher-Speed Bandwidth-focused modules for AI and high-performance computing.

Segment Analysis: By Application

By application, the market covers Internet Data Centers, Enterprise Data Centers, Edge Data Centers, AI / HPC Clusters. Demand varies by reliability, performance and product lifecycle. Premium applications usually require stricter qualification and long-term supply support, while higher-volume applications place more emphasis on cost, manufacturing scale and rapid technology migration. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Application Demand characteristics
Internet Data Centers Internet Data Centers is a material demand segment where reliability, cost and system performance influence purchasing decisions.
Enterprise Data Centers Enterprise Data Centers is a material demand segment where reliability, cost and system performance influence purchasing decisions.
Edge Data Centers Edge Data Centers is a material demand segment where reliability, cost and system performance influence purchasing decisions.
AI / HPC Clusters AI / HPC Clusters is a material demand segment where reliability, cost and system performance influence purchasing decisions.

Additional Segmentation: By End User

End User provides a second analytical view of the DRAM for Data Centers market. It captures how product architecture and end-use requirements change supplier economics, qualification effort and technology roadmaps across the forecast period. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

End User Commercial relevance
Cloud Service Providers Large-scale compute and storage fleets with frequent platform refresh cycles.
Hyperscalers AI and cloud infrastructure requiring very high memory capacity and bandwidth.
Enterprises Private data centers, virtualization and database workloads.
Telecom Operators Edge-cloud and network-function virtualization infrastructure.

Regional Analysis

North America is the largest regional market, while Asia Pacific is the fastest-growth region. Regional positioning reflects manufacturing concentration, downstream electronics demand, capital investment and the availability of qualified suppliers. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Why does regional demand differ across the DRAM for Data Centers market?

Regional demand varies with electronics manufacturing, technology adoption and local investment. North America combines the largest hyperscale operators with rapid AI-server deployment, while Asia Pacific adds new cloud, colocation and sovereign-compute capacity across China, Japan, South Korea, Singapore and India. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Region Position Demand profile Supplier-selection factor
Asia Pacific Fastest growth Technology and end-market demand Qualification, cost and local support
North America Largest / strategic Technology and end-market demand Qualification, cost and local support
Europe Strategic Technology and end-market demand Qualification, cost and local support
South America Strategic Technology and end-market demand Qualification, cost and local support
Middle East & Africa Strategic Technology and end-market demand Qualification, cost and local support
Asia Pacific FAST GROWTH

How does Asia Pacific participate in the DRAM for Data Centers market?

Asia Pacific is a major DRAM for Data Centers market because China, Japan, South Korea, Taiwan and Southeast Asia combine electronics manufacturing, semiconductor production and fast infrastructure investment. North America combines the largest hyperscale operators with rapid AI-server deployment, while Asia Pacific adds new cloud, colocation and sovereign-compute capacity across China, Japan, South Korea, Singapore and India.

Country / cluster Commercial logic
China / Taiwan Manufacturing scale and electronics demand.
Japan / South Korea / Southeast Asia High-value technology and supply-chain depth.

Market instances

  • Regional manufacturing capacity supports the DRAM for Data Centers supply chain.
  • Electronics and semiconductor investment drives local demand.
  • Supplier proximity improves qualification and logistics.
North America LARGEST

How does North America participate in the DRAM for Data Centers market?

North America is a high-value DRAM for Data Centers market supported by U.S. technology companies, data centers, aerospace, automotive and advanced manufacturing. North America combines the largest hyperscale operators with rapid AI-server deployment, while Asia Pacific adds new cloud, colocation and sovereign-compute capacity across China, Japan, South Korea, Singapore and India.

Country / cluster Commercial logic
United States Technology development, premium applications and design leadership.
Canada / Mexico Manufacturing and regional integration.

Market instances

  • U.S. technology investment supports DRAM for Data Centers adoption.
  • Customers emphasize qualification and lifecycle support.
  • Regional supply diversification remains important.
Europe STRATEGIC

How does Europe participate in the DRAM for Data Centers market?

Europe is strategically important in the DRAM for Data Centers market through automotive, industrial, telecom and aerospace applications. Buyers emphasize reliability, environmental compliance and long product lifecycles. North America combines the largest hyperscale operators with rapid AI-server deployment, while Asia Pacific adds new cloud, colocation and sovereign-compute capacity across China, Japan, South Korea, Singapore and India.

Country / cluster Commercial logic
Germany / France Industrial, automotive and technology demand.
UK / Nordics / Italy Specialty electronics and infrastructure.

Market instances

  • European customers favor high-reliability DRAM for Data Centers solutions.
  • Industrial and automotive demand supports premium products.
  • Standards and sustainability influence supplier selection.
South America STRATEGIC

How does South America participate in the DRAM for Data Centers market?

South America is an emerging DRAM for Data Centers market led by Brazil. Demand is concentrated in industrial, automotive, telecom and imported electronics platforms, with local manufacturing more limited than the core regions. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Country / cluster Commercial logic
Brazil Largest regional electronics and industrial market.
Argentina / Chile / Colombia Smaller application-specific demand.

Market instances

  • Most advanced DRAM for Data Centers products are imported.
  • Price sensitivity shapes product mix.
  • Growth follows industrial and electronics investment.
Middle East & Africa STRATEGIC

How does Middle East & Africa participate in the DRAM for Data Centers market?

The Middle East and Africa remain emerging markets for DRAM for Data Centers. Gulf investment in digital infrastructure and advanced manufacturing creates selective opportunities, while African demand is more concentrated in telecom, industrial and imported electronics. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Country / cluster Commercial logic
UAE / Saudi Arabia Smart infrastructure and technology investment.
South Africa / Israel Industrial, telecom and advanced electronics.

Market instances

  • Greenfield projects can adopt modern DRAM for Data Centers technologies.
  • Most supply is imported.
  • Local integration and service influence deployment.

Competitive Landscape

Samsung Electronics, SK hynix, Micron Technology and server-memory module ecosystem suppliers form the core competitive landscape. Suppliers differentiate through process capability, product breadth, qualification history, manufacturing scale and technical support. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

The competitive frontier is shifting toward ddr5 bandwidth scaling, mrdimm adoption and higher memory capacity per ai server, which raises the value of engineering integration and reduces the importance of price alone in premium segments. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Customer relationships are durable because qualified products become embedded inside longer-lived systems. This creates switching costs but also requires suppliers to maintain lifecycle support and predictable quality. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Competitive tier Representative companies Primary differentiation
Global leaders Samsung Electronics, SK hynix, Micron Technology and server-memory module ecosystem suppliers Scale, technology and customer qualification.
Specialists Regional and application-focused vendors Process expertise and niche performance.
Emerging suppliers New regional entrants Cost, local capacity and diversification.

Key companies profiled

Samsung Electronics, SK hynix, Micron Technology and server-memory module ecosystem suppliers are included in the competitive scope. Their positions differ by product mix, technology capability, geographic manufacturing footprint and customer qualification. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Production Capacity Analysis

Capacity depends on specialized materials, precision manufacturing, automated inspection and qualified final test. Effective output is determined by saleable yield and customer-approved capacity rather than nominal equipment throughput alone. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Supply expansion increasingly requires duplicated qualification across several factories. This is strategically important because customers want resilience without sacrificing consistency, particularly in automotive, data-center, industrial and high-reliability applications. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Market Dynamics

The market is driven by electronics content growth, system performance requirements and supply-chain modernization. Growth is restrained by capital intensity, qualification cycles and pricing pressure. DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server creates the strongest opportunity for premium value growth. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Market Drivers

Driver Impact Commercial mechanism
Technology migration High DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server increases product value and complexity.
Electronics demand High More electronic content increases component consumption.
Supply diversification Medium-High Customers want qualified capacity across several regions.
Automation Medium Higher automation improves yield and throughput.

Technology migration

Customers are adopting more advanced architectures to improve performance, density or efficiency. This raises qualification and process-control requirements and supports premium pricing for technically differentiated suppliers. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Electronics demand

Growth in automotive, data centers, industrial automation and connected devices expands the installed base requiring DRAM for Data Centers products. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Supply diversification

Geopolitical and logistics risk encourage multi-site sourcing, creating opportunities for suppliers that can replicate quality across factories. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Automation

Automated process control, inspection and material handling can reduce variation and support larger production volumes. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Market Restraints

Restraint Impact Commercial consequence
Capital intensity High Advanced manufacturing requires specialized equipment.
Qualification cycles Medium-High Customer approval can take many months.
Price pressure Medium High-volume segments face continuing cost reduction.
Supply-chain risk Medium Specialized materials or equipment can be concentrated.

Capital intensity

New DRAM for Data Centers capacity can require significant equipment and qualification investment before revenue scales. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Qualification cycles

Reliability validation and system integration slow supplier switching and delay new-factory ramps. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Price pressure

Suppliers must offset lower average selling prices with yield, automation and differentiated technology. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Supply-chain risk

Dependence on limited upstream suppliers can affect lead times and create the need for strategic inventory or second sourcing. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Market Opportunities

DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server

DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server can expand value per unit and improve system performance. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Regional manufacturing

New qualified capacity can support customers seeking geographic diversification. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Automation and inspection

Better process control can raise yield and reduce lifecycle cost. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Application-specific products

Tailored designs can capture premium niches with stronger qualification barriers. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Supply Chain Analysis

Specialized materials & equipment
Precision manufacturing
Qualification & system integration
End-market deployment

Upstream. Specialized materials, wafers, laminates, metals or process equipment provide the technical foundation. Quality at this stage influences downstream yield and reliability. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Manufacturing. Suppliers use precision process control and automated inspection to produce DRAM for Data Centers products within tight tolerances. Yield improvement is a major economic lever. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Integration. Products are qualified inside customer systems where electrical, thermal or mechanical behavior is validated. Design changes can trigger additional testing. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Deployment. Finished products enter electronics, industrial, automotive, data-center or aerospace systems. Lifecycle support and supply continuity determine long-term customer value. Commercial decisions in the DRAM for Data Centers market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.

Recent Developments in the DRAM for Data Centers Market

Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.

  • 2026 AI Infrastructure
    Micron continues expanding DDR5 and high-capacity server memory offerings for AI and cloud data centers, emphasizing higher bandwidth and improved power efficiency. Source
  • 2026 Server Memory
    Samsung continues advancing server DRAM and DDR5 module solutions for data centers and AI infrastructure. Source
  • 2026 Memory Roadmap
    SK hynix continues scaling DDR5 and high-bandwidth memory technologies across enterprise and AI server platforms. Source

Report Scope & Segmentation

Attribute Scope
Base year 2025
Estimated year 2026
Forecast period 2026–2034
2025 market size USD 6.11 billion
2026 estimated size USD 6.59 billion
2034 projected size USD 12.14 billion
CAGR (2026–2034) 7.9%
Largest market in 2025 North America
By Type UDIMM; SODIMM; RDIMM; MRDIMM; LRDIMM; Others
By Application Internet Data Centers; Enterprise Data Centers; Edge Data Centers; AI / HPC Clusters
By Memory Generation DDR4; DDR5; DDR5 MRDIMM / Higher-Speed
By End User Cloud Service Providers; Hyperscalers; Enterprises; Telecom Operators
Companies profiled Samsung Electronics, SK hynix, Micron Technology and server-memory module ecosystem suppliers

Frequently Asked Questions

What is the DRAM for Data Centers market size in 2025?

The global market is valued at USD 6.11 billion in 2025.

What is the market forecast for 2034?

The market is projected to reach USD 12.14 billion by 2034, representing a 7.9% CAGR during 2026–2034. The 2026 market level is USD 6.59 billion.

Which region leads the market?

North America is the largest market, while Asia Pacific has the strongest growth profile.

Which type is most important?

UDIMM is a leading category within the current market structure.

Which applications matter most?

Internet Data Centers and other listed applications are the principal demand segments.

What technology trend matters most?

DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server is a major technology and competitive trend.

Who are the major suppliers?

Major participants include Samsung Electronics, SK hynix, Micron Technology and server-memory module ecosystem suppliers.

What drives market growth?

Electronics content, technology upgrades, automation and supply-chain modernization are the main growth drivers.

What limits growth?

Capital intensity, qualification cycles, price pressure and supply-chain concentration are the main restraints.

What will shape the market through 2034?

DDR5 bandwidth scaling, MRDIMM adoption and higher memory capacity per AI server, regional manufacturing diversification and more automated production will shape the market through 2034.

Research Sources & Evidence Base

View research sources used in this market overview
  1. Samsung Semiconductor — Server DRAM Modules. Current server-memory module portfolio context.
  2. Micron Technology — DRAM Products. Current DDR5 and data-center DRAM product context.
  3. SK hynix — DRAM Portfolio. Current server and high-performance DRAM product context.
DRAM for Data Centers Market Size, Share & Industry Analysis, By Type (UDIMM, SODIMM, RDIMM, MRDIMM, LRDIMM, Others), By Application (Internet Data Centers, Enterprise Data Centers, Edge Data Centers, AI/HPC Clusters), By Memory Generation (DDR4, DDR5, DDR5 MRDIMM/Higher-Speed), By End User (Cloud Service Providers, Hyperscalers, Enterprises, Telecom Operators), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...
Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 DRAM for Data Centers Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global DRAM for Data Centers Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global DRAM for Data Centers Overall Market Size
2.1 Global DRAM for Data Centers Market Size: 2024 VS 2032
2.2 Global DRAM for Data Centers Market Size, Prospects & Forecasts: 2026-2034
2.3 Global DRAM for Data Centers Sales: 2026-2034
3 Company Landscape
3.1 Top DRAM for Data Centers Players in Global Market
3.2 Top Global DRAM for Data Centers Companies Ranked by Revenue
3.3 Global DRAM for Data Centers Revenue by Companies
3.4 Global DRAM for Data Centers Sales by Companies
3.5 Global DRAM for Data Centers Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 DRAM for Data Centers Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers DRAM for Data Centers Product Type
3.8 Tier 1, Tier 2, and Tier 3 DRAM for Data Centers Players in Global Market
3.8.1 List of Global Tier 1 DRAM for Data Centers Companies
3.8.2 List of Global Tier 2 and Tier 3 DRAM for Data Centers Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global DRAM for Data Centers Market Size Markets, 2024 & 2032
4.1.2 UDIMM
4.1.3 SODIMM
4.1.4 RDIMM
4.1.5 MRDIMM
4.1.6 LRDIMM
4.1.7 Others
4.2 Segment by Type – Global DRAM for Data Centers Revenue & Forecasts
4.2.1 Segment by Type – Global DRAM for Data Centers Revenue, 2020-2025
4.2.2 Segment by Type – Global DRAM for Data Centers Revenue, 2026-2032
4.2.3 Segment by Type – Global DRAM for Data Centers Revenue Market Share, 2026-2034
4.3 Segment by Type – Global DRAM for Data Centers Sales & Forecasts
4.3.1 Segment by Type – Global DRAM for Data Centers Sales, 2020-2025
4.3.2 Segment by Type – Global DRAM for Data Centers Sales, 2026-2032
4.3.3 Segment by Type – Global DRAM for Data Centers Sales Market Share, 2026-2034
4.4 Segment by Type – Global DRAM for Data Centers Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global DRAM for Data Centers Market Size, 2024 & 2032
5.1.2 IDC (Internet Data Center)
5.1.3 EDC (Enterprise Data Center)
5.1.4 Others
5.2 Segment by Application – Global DRAM for Data Centers Revenue & Forecasts
5.2.1 Segment by Application – Global DRAM for Data Centers Revenue, 2020-2025
5.2.2 Segment by Application – Global DRAM for Data Centers Revenue, 2026-2032
5.2.3 Segment by Application – Global DRAM for Data Centers Revenue Market Share, 2026-2034
5.3 Segment by Application – Global DRAM for Data Centers Sales & Forecasts
5.3.1 Segment by Application – Global DRAM for Data Centers Sales, 2020-2025
5.3.2 Segment by Application – Global DRAM for Data Centers Sales, 2026-2032
5.3.3 Segment by Application – Global DRAM for Data Centers Sales Market Share, 2026-2034
5.4 Segment by Application – Global DRAM for Data Centers Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global DRAM for Data Centers Market Size, 2024 & 2032
6.2 By Region – Global DRAM for Data Centers Revenue & Forecasts
6.2.1 By Region – Global DRAM for Data Centers Revenue, 2020-2025
6.2.2 By Region – Global DRAM for Data Centers Revenue, 2026-2032
6.2.3 By Region – Global DRAM for Data Centers Revenue Market Share, 2026-2034
6.3 By Region – Global DRAM for Data Centers Sales & Forecasts
6.3.1 By Region – Global DRAM for Data Centers Sales, 2020-2025
6.3.2 By Region – Global DRAM for Data Centers Sales, 2026-2032
6.3.3 By Region – Global DRAM for Data Centers Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America DRAM for Data Centers Revenue, 2026-2034
6.4.2 By Country – North America DRAM for Data Centers Sales, 2026-2034
6.4.3 United States DRAM for Data Centers Market Size, 2026-2034
6.4.4 Canada DRAM for Data Centers Market Size, 2026-2034
6.4.5 Mexico DRAM for Data Centers Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe DRAM for Data Centers Revenue, 2026-2034
6.5.2 By Country – Europe DRAM for Data Centers Sales, 2026-2034
6.5.3 Germany DRAM for Data Centers Market Size, 2026-2034
6.5.4 France DRAM for Data Centers Market Size, 2026-2034
6.5.5 U.K. DRAM for Data Centers Market Size, 2026-2034
6.5.6 Italy DRAM for Data Centers Market Size, 2026-2034
6.5.7 Russia DRAM for Data Centers Market Size, 2026-2034
6.5.8 Nordic Countries DRAM for Data Centers Market Size, 2026-2034
6.5.9 Benelux DRAM for Data Centers Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia DRAM for Data Centers Revenue, 2026-2034
6.6.2 By Region – Asia DRAM for Data Centers Sales, 2026-2034
6.6.3 China DRAM for Data Centers Market Size, 2026-2034
6.6.4 Japan DRAM for Data Centers Market Size, 2026-2034
6.6.5 South Korea DRAM for Data Centers Market Size, 2026-2034
6.6.6 Southeast Asia DRAM for Data Centers Market Size, 2026-2034
6.6.7 India DRAM for Data Centers Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America DRAM for Data Centers Revenue, 2026-2034
6.7.2 By Country – South America DRAM for Data Centers Sales, 2026-2034
6.7.3 Brazil DRAM for Data Centers Market Size, 2026-2034
6.7.4 Argentina DRAM for Data Centers Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa DRAM for Data Centers Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa DRAM for Data Centers Sales, 2026-2034
6.8.3 Turkey DRAM for Data Centers Market Size, 2026-2034
6.8.4 Israel DRAM for Data Centers Market Size, 2026-2034
6.8.5 Saudi Arabia DRAM for Data Centers Market Size, 2026-2034
6.8.6 UAE DRAM for Data Centers Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Samsung
7.1.1 Samsung Company Summary
7.1.2 Samsung Business Overview
7.1.3 Samsung DRAM for Data Centers Major Product Offerings
7.1.4 Samsung DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.1.5 Samsung Key News & Latest Developments
7.2 SK Hynix
7.2.1 SK Hynix Company Summary
7.2.2 SK Hynix Business Overview
7.2.3 SK Hynix DRAM for Data Centers Major Product Offerings
7.2.4 SK Hynix DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.2.5 SK Hynix Key News & Latest Developments
7.3 Micron Technology
7.3.1 Micron Technology Company Summary
7.3.2 Micron Technology Business Overview
7.3.3 Micron Technology DRAM for Data Centers Major Product Offerings
7.3.4 Micron Technology DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.3.5 Micron Technology Key News & Latest Developments
7.4 Changxin Memory Technologies (CXMT)
7.4.1 Changxin Memory Technologies (CXMT) Company Summary
7.4.2 Changxin Memory Technologies (CXMT) Business Overview
7.4.3 Changxin Memory Technologies (CXMT) DRAM for Data Centers Major Product Offerings
7.4.4 Changxin Memory Technologies (CXMT) DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.4.5 Changxin Memory Technologies (CXMT) Key News & Latest Developments
7.5 Kingston Technology Company, Inc.
7.5.1 Kingston Technology Company, Inc. Company Summary
7.5.2 Kingston Technology Company, Inc. Business Overview
7.5.3 Kingston Technology Company, Inc. DRAM for Data Centers Major Product Offerings
7.5.4 Kingston Technology Company, Inc. DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.5.5 Kingston Technology Company, Inc. Key News & Latest Developments
7.6 SMART Modular Technologies
7.6.1 SMART Modular Technologies Company Summary
7.6.2 SMART Modular Technologies Business Overview
7.6.3 SMART Modular Technologies DRAM for Data Centers Major Product Offerings
7.6.4 SMART Modular Technologies DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.6.5 SMART Modular Technologies Key News & Latest Developments
7.7 ADATA Technology
7.7.1 ADATA Technology Company Summary
7.7.2 ADATA Technology Business Overview
7.7.3 ADATA Technology DRAM for Data Centers Major Product Offerings
7.7.4 ADATA Technology DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.7.5 ADATA Technology Key News & Latest Developments
7.8 Rambus
7.8.1 Rambus Company Summary
7.8.2 Rambus Business Overview
7.8.3 Rambus DRAM for Data Centers Major Product Offerings
7.8.4 Rambus DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.8.5 Rambus Key News & Latest Developments
7.9 Kimtigo
7.9.1 Kimtigo Company Summary
7.9.2 Kimtigo Business Overview
7.9.3 Kimtigo DRAM for Data Centers Major Product Offerings
7.9.4 Kimtigo DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.9.5 Kimtigo Key News & Latest Developments
7.10 Transcend
7.10.1 Transcend Company Summary
7.10.2 Transcend Business Overview
7.10.3 Transcend DRAM for Data Centers Major Product Offerings
7.10.4 Transcend DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.10.5 Transcend Key News & Latest Developments
7.11 Innodisk
7.11.1 Innodisk Company Summary
7.11.2 Innodisk Business Overview
7.11.3 Innodisk DRAM for Data Centers Major Product Offerings
7.11.4 Innodisk DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.11.5 Innodisk Key News & Latest Developments
7.12 TeamGroup
7.12.1 TeamGroup Company Summary
7.12.2 TeamGroup Business Overview
7.12.3 TeamGroup DRAM for Data Centers Major Product Offerings
7.12.4 TeamGroup DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.12.5 TeamGroup Key News & Latest Developments
7.13 Apacer Technology
7.13.1 Apacer Technology Company Summary
7.13.2 Apacer Technology Business Overview
7.13.3 Apacer Technology DRAM for Data Centers Major Product Offerings
7.13.4 Apacer Technology DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.13.5 Apacer Technology Key News & Latest Developments
7.14 G.SKILL
7.14.1 G.SKILL Company Summary
7.14.2 G.SKILL Business Overview
7.14.3 G.SKILL DRAM for Data Centers Major Product Offerings
7.14.4 G.SKILL DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.14.5 G.SKILL Key News & Latest Developments
7.15 Shenzhen Longsys
7.15.1 Shenzhen Longsys Company Summary
7.15.2 Shenzhen Longsys Business Overview
7.15.3 Shenzhen Longsys DRAM for Data Centers Major Product Offerings
7.15.4 Shenzhen Longsys DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.15.5 Shenzhen Longsys Key News & Latest Developments
7.16 Ramaxel
7.16.1 Ramaxel Company Summary
7.16.2 Ramaxel Business Overview
7.16.3 Ramaxel DRAM for Data Centers Major Product Offerings
7.16.4 Ramaxel DRAM for Data Centers Sales and Revenue in Global (2020-2025)
7.16.5 Ramaxel Key News & Latest Developments
8 Global DRAM for Data Centers Production Capacity, Analysis
8.1 Global DRAM for Data Centers Production Capacity, 2026-2034
8.2 DRAM for Data Centers Production Capacity of Key Manufacturers in Global Market
8.3 Global DRAM for Data Centers Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 DRAM for Data Centers Supply Chain Analysis
10.1 DRAM for Data Centers Industry Value Chain
10.2 DRAM for Data Centers Upstream Market
10.3 DRAM for Data Centers Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 DRAM for Data Centers Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of DRAM for Data Centers in Global Market
Table 2. Top DRAM for Data Centers Players in Global Market, Ranking by Revenue (2024)
Table 3. Global DRAM for Data Centers Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global DRAM for Data Centers Revenue Share by Companies, 2020-2025
Table 5. Global DRAM for Data Centers Sales by Companies, (Million Units), 2020-2025
Table 6. Global DRAM for Data Centers Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers DRAM for Data Centers Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers DRAM for Data Centers Product Type
Table 9. List of Global Tier 1 DRAM for Data Centers Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 DRAM for Data Centers Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global DRAM for Data Centers Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global DRAM for Data Centers Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global DRAM for Data Centers Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global DRAM for Data Centers Sales (Million Units), 2020-2025
Table 15. Segment by Type – Global DRAM for Data Centers Sales (Million Units), 2026-2032
Table 16. Segment by Application – Global DRAM for Data Centers Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 20. Segment by Application – Global DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 21. By Region – Global DRAM for Data Centers Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 25. By Region – Global DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 26. By Country – North America DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 29. By Country – North America DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 30. By Country – Europe DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 33. By Country – Europe DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 34. By Region – Asia DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 37. By Region – Asia DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 38. By Country – South America DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 41. By Country – South America DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 42. By Country – Middle East & Africa DRAM for Data Centers Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa DRAM for Data Centers Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa DRAM for Data Centers Sales, (Million Units), 2020-2025
Table 45. By Country – Middle East & Africa DRAM for Data Centers Sales, (Million Units), 2026-2032
Table 46. Samsung Company Summary
Table 47. Samsung DRAM for Data Centers Product Offerings
Table 48. Samsung DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. Samsung Key News & Latest Developments
Table 50. SK Hynix Company Summary
Table 51. SK Hynix DRAM for Data Centers Product Offerings
Table 52. SK Hynix DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. SK Hynix Key News & Latest Developments
Table 54. Micron Technology Company Summary
Table 55. Micron Technology DRAM for Data Centers Product Offerings
Table 56. Micron Technology DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. Micron Technology Key News & Latest Developments
Table 58. Changxin Memory Technologies (CXMT) Company Summary
Table 59. Changxin Memory Technologies (CXMT) DRAM for Data Centers Product Offerings
Table 60. Changxin Memory Technologies (CXMT) DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. Changxin Memory Technologies (CXMT) Key News & Latest Developments
Table 62. Kingston Technology Company, Inc. Company Summary
Table 63. Kingston Technology Company, Inc. DRAM for Data Centers Product Offerings
Table 64. Kingston Technology Company, Inc. DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. Kingston Technology Company, Inc. Key News & Latest Developments
Table 66. SMART Modular Technologies Company Summary
Table 67. SMART Modular Technologies DRAM for Data Centers Product Offerings
Table 68. SMART Modular Technologies DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 69. SMART Modular Technologies Key News & Latest Developments
Table 70. ADATA Technology Company Summary
Table 71. ADATA Technology DRAM for Data Centers Product Offerings
Table 72. ADATA Technology DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 73. ADATA Technology Key News & Latest Developments
Table 74. Rambus Company Summary
Table 75. Rambus DRAM for Data Centers Product Offerings
Table 76. Rambus DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 77. Rambus Key News & Latest Developments
Table 78. Kimtigo Company Summary
Table 79. Kimtigo DRAM for Data Centers Product Offerings
Table 80. Kimtigo DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 81. Kimtigo Key News & Latest Developments
Table 82. Transcend Company Summary
Table 83. Transcend DRAM for Data Centers Product Offerings
Table 84. Transcend DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 85. Transcend Key News & Latest Developments
Table 86. Innodisk Company Summary
Table 87. Innodisk DRAM for Data Centers Product Offerings
Table 88. Innodisk DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 89. Innodisk Key News & Latest Developments
Table 90. TeamGroup Company Summary
Table 91. TeamGroup DRAM for Data Centers Product Offerings
Table 92. TeamGroup DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 93. TeamGroup Key News & Latest Developments
Table 94. Apacer Technology Company Summary
Table 95. Apacer Technology DRAM for Data Centers Product Offerings
Table 96. Apacer Technology DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 97. Apacer Technology Key News & Latest Developments
Table 98. G.SKILL Company Summary
Table 99. G.SKILL DRAM for Data Centers Product Offerings
Table 100. G.SKILL DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 101. G.SKILL Key News & Latest Developments
Table 102. Shenzhen Longsys Company Summary
Table 103. Shenzhen Longsys DRAM for Data Centers Product Offerings
Table 104. Shenzhen Longsys DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 105. Shenzhen Longsys Key News & Latest Developments
Table 106. Ramaxel Company Summary
Table 107. Ramaxel DRAM for Data Centers Product Offerings
Table 108. Ramaxel DRAM for Data Centers Sales (Million Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 109. Ramaxel Key News & Latest Developments
Table 110. DRAM for Data Centers Capacity of Key Manufacturers in Global Market, 2023-2025 (Million Units)
Table 111. Global DRAM for Data Centers Capacity Market Share of Key Manufacturers, 2023-2025
Table 112. Global DRAM for Data Centers Production by Region, 2020-2025 (Million Units)
Table 113. Global DRAM for Data Centers Production by Region, 2026-2032 (Million Units)
Table 114. DRAM for Data Centers Market Opportunities & Trends in Global Market
Table 115. DRAM for Data Centers Market Drivers in Global Market
Table 116. DRAM for Data Centers Market Restraints in Global Market
Table 117. DRAM for Data Centers Raw Materials
Table 118. DRAM for Data Centers Raw Materials Suppliers in Global Market
Table 119. Typical DRAM for Data Centers Downstream
Table 120. DRAM for Data Centers Downstream Clients in Global Market
Table 121. DRAM for Data Centers Distributors and Sales Agents in Global Market

List of Figures
Figure 1. DRAM for Data Centers Product Picture
Figure 2. DRAM for Data Centers Segment by Type in 2024
Figure 3. DRAM for Data Centers Segment by Application in 2024
Figure 4. Global DRAM for Data Centers Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global DRAM for Data Centers Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global DRAM for Data Centers Revenue: 2026-2034 (US$, Mn)
Figure 8. DRAM for Data Centers Sales in Global Market: 2026-2034 (Million Units)
Figure 9. The Top 3 and 5 Players Market Share by DRAM for Data Centers Revenue in 2024
Figure 10. Segment by Type – Global DRAM for Data Centers Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global DRAM for Data Centers Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global DRAM for Data Centers Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global DRAM for Data Centers Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global DRAM for Data Centers Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global DRAM for Data Centers Price (US$/Unit), 2026-2034
Figure 18. By Region – Global DRAM for Data Centers Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global DRAM for Data Centers Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 21. By Region – Global DRAM for Data Centers Sales Market Share, 2026-2034
Figure 22. By Country – North America DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 23. By Country – North America DRAM for Data Centers Sales Market Share, 2026-2034
Figure 24. United States DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 25. Canada DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 28. By Country – Europe DRAM for Data Centers Sales Market Share, 2026-2034
Figure 29. Germany DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 30. France DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 32. Italy DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 33. Russia DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 37. By Region – Asia DRAM for Data Centers Sales Market Share, 2026-2034
Figure 38. China DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 39. Japan DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 42. India DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America DRAM for Data Centers Revenue Market Share, 2026-2034
Figure 44. By Country – South America DRAM for Data Centers Sales, Market Share, 2026-2034
Figure 45. Brazil DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa DRAM for Data Centers Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa DRAM for Data Centers Sales, Market Share, 2026-2034
Figure 49. Turkey DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 50. Israel DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 52. UAE DRAM for Data Centers Revenue, (US$, Mn), 2026-2034
Figure 53. Global DRAM for Data Centers Production Capacity (Million Units), 2026-2034
Figure 54. The Percentage of Production DRAM for Data Centers by Region, 2024 VS 2032
Figure 55. DRAM for Data Centers Industry Value Chain
Figure 56. Marketing Channels