
Key Statistics
Key Takeaways
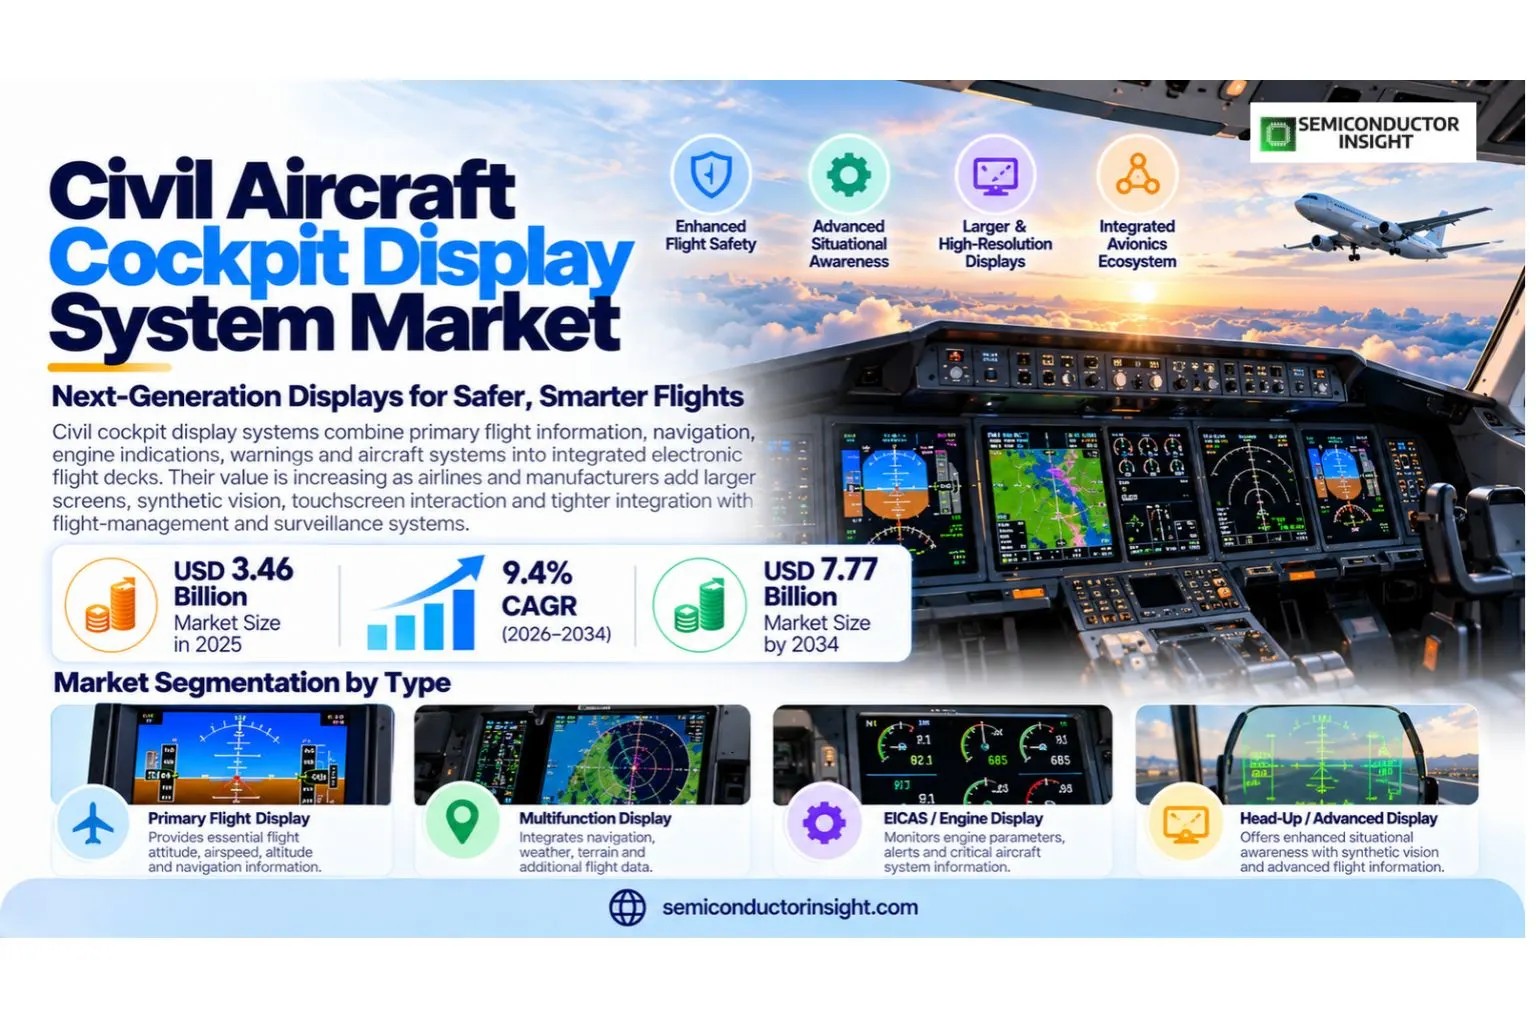
- Market size: The market is valued at USD 3.46 billion in 2025 and is projected to reach USD 7.77 billion by 2034, representing a 9.4% CAGR during 2026–2034.
- Primary Flight Display remains commercially important because of its established use in core applications.
- North America leads current market value, while Asia Pacific offers a strong growth profile.
- Commercial Airliners is a major demand segment, with purchasing shaped by reliability, performance and system integration.
- larger integrated displays, synthetic vision and software-defined cockpit functionality is a central competitive theme through 2034.
Civil Aircraft Cockpit Display System Market Overview
Civil aircraft cockpit display system market is valued at USD 3.46 billion in 2025 and is projected to reach USD 7.77 billion by 2034, expanding at a 9.4% CAGR during 2026–2034. The 2026 market level is USD 3.79 billion. Civil cockpit display systems combine primary flight information, navigation, engine indications, warnings and aircraft systems into integrated electronic flight decks. Their value is increasing as airlines and manufacturers add larger screens, synthetic vision, touchscreen interaction and tighter integration with flight-management and surveillance systems.
The client evidence values the market at USD 3.163 billion in 2024 and projects USD 6.074 billion by 2032. Growth is linked to aircraft production, cockpit modernization and the shift from federated instruments toward integrated avionics architectures with configurable displays. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Certification is a major competitive barrier because displays must satisfy stringent environmental, reliability and software assurance requirements. Suppliers benefit from long platform lifecycles once selected, but product development requires sustained support through qualification, aircraft certification and decades of service. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Segment Analysis: By Type
By type, the market is segmented into Primary Flight Display, Multifunction Display, EICAS / Engine Display, Head-Up / Advanced Display. Each category serves a distinct performance, cost or integration requirement, so competitive positioning depends on more than shipment volume. Higher-value variants usually command premium pricing when they reduce system complexity, improve efficiency or satisfy stricter qualification requirements.
| Type | Commercial role |
|---|---|
| Primary Flight Display | Consolidates attitude, airspeed, altitude, navigation and flight-director information. |
| Multifunction Display | Supports navigation, systems, weather, traffic and mission information on configurable screens. |
| EICAS / Engine Display | Presents engine parameters, alerts and aircraft-system status. |
| Head-Up / Advanced Display | Extends flight-critical information into head-up or next-generation cockpit visualization. |
Additional Segmentation: By Display Technology
Display technology affects luminance, viewing angle, power, lifetime, sunlight readability and cockpit thermal design. LCD remains the installed-base standard, while OLED and emerging emissive technologies are evaluated for contrast, form factor and advanced interface design. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Display Technology | Demand characteristics |
|---|---|
| LCD | Current mainstream in certified civil cockpits because of maturity and reliability. |
| OLED | Higher contrast and potential weight or packaging benefits for selected new platforms. |
| MicroLED / Emerging | Longer-term option for very high brightness, efficiency and ruggedized displays. |
Segment Analysis: By Application
By application, demand spans Commercial Airliners, Regional Aircraft, Business Jets, General Aviation. The mix changes according to performance needs, system value, reliability requirements, regulatory exposure and product lifecycle. This makes application-level analysis more useful than mechanically repeating one market statistic across every segment. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Commercial Airliners | Largest value pool because of multi-display cockpits, long certification cycles and high aircraft production value. |
| Regional Aircraft | Uses integrated glass-cockpit systems optimized for shorter-haul fleets. |
| Business Jets | Premium avionics demand supports advanced displays, synthetic vision and integrated flight decks. |
| General Aviation | Smaller displays and retrofit systems support fleet modernization and safety upgrades. |
Additional Segmentation: By Aircraft Fit
Line-fit demand tracks aircraft production, while retrofit demand follows fleet age, regulatory changes and operator modernization programs. Retrofit systems must fit existing panel geometry and avionics interfaces, making certification and installation economics especially important. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Aircraft Fit | Commercial role |
|---|---|
| Line-Fit | Factory-installed systems on new aircraft programs. |
| Retrofit | Replacement and modernization of installed cockpit displays in existing fleets. |
Regional Analysis
North America is used as the largest current market because Boeing, Gulfstream, Textron, Collins Aerospace, Honeywell and Garmin anchor a large civil-avionics ecosystem. Asia Pacific is the fastest-growth region as airline fleets and aircraft deliveries expand from a lower installed base. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Regional demand is driven by aircraft production, airline fleet growth, business-jet activity and retrofit cycles. North America has a dense avionics and OEM ecosystem, Europe is anchored by Airbus and major Tier-1 suppliers, and Asia Pacific has the strongest traffic and fleet-expansion trajectory. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Asia Pacific
Asia Pacific demand is supported by high-volume electronics manufacturing, semiconductor fabrication, automotive production and digital-infrastructure investment. China, Japan, South Korea, Taiwan, India and Southeast Asia contribute different mixes of production, consumption and technical capability, making the region central to both scale and supply-chain development. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
North America
North America remains a high-value market because of strong semiconductor design, aerospace, cloud, enterprise and advanced-manufacturing activity. The United States is the principal contributor, supported by leading technology companies, research institutions and early adoption of premium systems with demanding performance requirements. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Europe
Europe combines advanced automotive, aerospace, industrial, energy and research demand. Germany, France, the United Kingdom, Italy and the Nordic markets emphasize reliability, energy efficiency, safety and regulatory compliance, supporting demand for technically differentiated products with strong lifecycle support. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
South America
South America is a smaller but developing market led by Brazil and selected industrial economies. Demand is concentrated in telecom, infrastructure, industrial modernization, healthcare and consumer electronics, while import dependence makes distributor support, local certification and pricing important commercial factors. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Middle East & Africa
Middle East & Africa remains an emerging market where demand is concentrated in infrastructure, telecom, aviation, defense, energy and data-center projects. Gulf countries account for much of the premium investment, while wider adoption depends on local technical capability, procurement cycles and access to qualified suppliers. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competitive Landscape
The competitive landscape includes Collins Aerospace, Honeywell, Garmin, Thales, Safran, L3Harris and major integrated avionics suppliers. Supplier position is shaped by technical performance, qualification depth, customer relationships, manufacturing scale, software or application support and the ability to sustain product roadmaps across long customer lifecycles. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competitive advantage comes from certification pedigree, system integration, display readability, redundancy, long-term software support and the ability to qualify one platform across multiple aircraft variants. New entrants face a substantial barrier because airlines and airframers prioritize proven reliability and lifecycle support. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive dimension | What matters |
|---|---|
| Technology | Performance, integration, roadmap credibility and IP differentiation. |
| Qualification | Customer validation, compliance and field history. |
| Supply | Capacity, lead time, quality consistency and resilience. |
| Support | Application engineering, service and lifecycle management. |
Production Capacity Analysis
Production capacity is less about high-volume panel fabrication and more about certified avionics assembly, display-module integration, environmental test and software configuration. Suppliers typically maintain dedicated aerospace manufacturing and repair networks to support decades-long fleet lifecycles. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Long aircraft lead times create relatively visible demand for line-fit systems, while retrofit demand is less predictable and depends on maintenance schedules and airline capital spending. Component obsolescence management is therefore a core capacity-planning requirement. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The market is shaped by aircraft delivery cycles, avionics modernization, software-defined cockpit functions and the need to reduce pilot workload. Larger integrated displays can replace multiple dedicated instruments, but every interface change must be validated for human factors and flight safety. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Display hardware is becoming more capable, yet certification and lifecycle economics slow technology turnover compared with consumer electronics. Suppliers therefore focus on incremental upgrades, common avionics platforms and software-enabled functionality that can be introduced without destabilizing certified architectures. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
Growth is driven by commercial aircraft deliveries, business-jet demand, fleet retrofits, synthetic vision and greater use of integrated glass cockpits. Airlines also value systems that improve situational awareness and reduce maintenance through consolidated avionics architectures. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Driver | Directional impact on CAGR |
|---|---|
| Technology upgrade cycle | +1.8 percentage points |
| End-market expansion | +1.3 percentage points |
| Higher content per system | +0.9 percentage points |
Market Restraints
Lengthy certification, high development cost and long aircraft lifecycles restrain rapid technology replacement. Display failures are safety-critical, so suppliers must demonstrate environmental robustness, software assurance and parts support over decades. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Restraint | Directional impact on CAGR |
|---|---|
| Qualification / integration burden | -0.8 percentage points |
| Price pressure | -0.6 percentage points |
| Supply complexity | -0.5 percentage points |
Market Opportunities
Opportunities include larger-area displays, touch-enabled flight decks, synthetic and combined vision, lighter OLED-based modules and retrofit packages for aging fleets. Common cockpit architectures across aircraft families can improve scale and reduce certification cost. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Opportunity | Commercial significance |
|---|---|
| larger integrated displays, synthetic vision and software-defined cockpit functionality | Supports premium product mix and new design wins. |
| Regional capacity | Improves lead time and supply resilience. |
| Application engineering | Deepens customer integration and raises switching costs. |
Supply Chain Analysis
The supply chain combines display panels, graphics processors, avionics computers, certified software, optical coatings, ruggedized electronics and specialized aerospace assembly. Airframers and Tier-1 avionics suppliers coordinate integration before systems enter flight test and certification. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Stage | Role |
|---|---|
| Display & electronics | High-brightness panels, backlights, processors and ruggedized power electronics. |
| Avionics integration | Flight computers, graphics generation, I/O and redundancy architecture. |
| Certification | Environmental qualification, software assurance, human factors and airworthiness approval. |
| Lifecycle support | Spares, repair, software updates and retrofit engineering. |
Unlike consumer displays, cockpit systems derive much of their value from certification, redundancy and long-term support rather than panel cost alone. This creates durable supplier relationships once a system is selected for a major aircraft platform. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Recent Developments in the Civil Aircraft Cockpit Display System Market
Report Scope & Segmentation
This analysis covers the Civil Aircraft Cockpit Display System market from a 2025 base year through the 2026–2034 forecast period. It evaluates demand by product type, application and two additional segmentation axes, with regional coverage spanning Asia Pacific, North America, Europe, South America, and the Middle East & Africa. Commercial decisions in the Civil Aircraft Cockpit Display System market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Scope item | Coverage |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | Primary Flight Display, Multifunction Display, EICAS / Engine Display, Head-Up / Advanced Display |
| By Application | Commercial Airliners, Regional Aircraft, Business Jets, General Aviation |
| By Display Technology | LCD, OLED, MicroLED / Emerging |
| By Aircraft Fit | Line-Fit, Retrofit |
| Key participants | Collins Aerospace, Honeywell, Garmin, Thales, Safran, L3Harris and major integrated avionics suppliers |
Frequently Asked Questions
What is the Civil Aircraft Cockpit Display System market size in 2025?
The market is valued at USD 3.46 billion in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 7.77 billion by 2034, with a 9.4% CAGR during 2026–2034.
Which region leads the market?
North America leads current market value, while Asia Pacific has a strong growth profile.
Which type is most important?
Primary Flight Display is a leading category, although mix varies by application.
Which applications matter most?
Commercial Airliners is a major demand segment, alongside Regional Aircraft, Business Jets.
What technology trend matters most?
larger integrated displays, synthetic vision and software-defined cockpit functionality is a central technology and commercialization trend.
Who are the major suppliers?
Major participants include Collins Aerospace, Honeywell, Garmin, Thales, Safran, L3Harris and major integrated avionics suppliers.
What drives market growth?
Growth is driven by commercial aircraft deliveries, business-jet demand, fleet retrofits, synthetic vision and greater use of integrated glass cockpits. Airlines also value systems that improve situational awareness and
What limits growth?
Lengthy certification, high development cost and long aircraft lifecycles restrain rapid technology replacement. Display failures are safety-critical, so suppliers must demonstrate environmental robustness, software assu
What will shape the market through 2034?
Technology roadmaps, qualification, supply continuity and larger integrated displays, synthetic vision and software-defined cockpit functionality will shape competitive outcomes.
Research Sources & Evidence Base
View selected external research sources
- Collins Aerospace — Flight Deck: Current civil-avionics and cockpit display context. Open source
- Honeywell Aerospace — Cockpit Systems: Current integrated cockpit and avionics context. Open source
- Garmin — Flight Decks & Displays: Current glass-cockpit and retrofit display context. Open source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF



