SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

AR and VR Optical Components Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
DISPLAY AND VISUALIZATION Semiconductor Market Research

AR and VR Optical Components Market

◷
UPDATED 22 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE dfc156371573
▯
FORMATS PDF

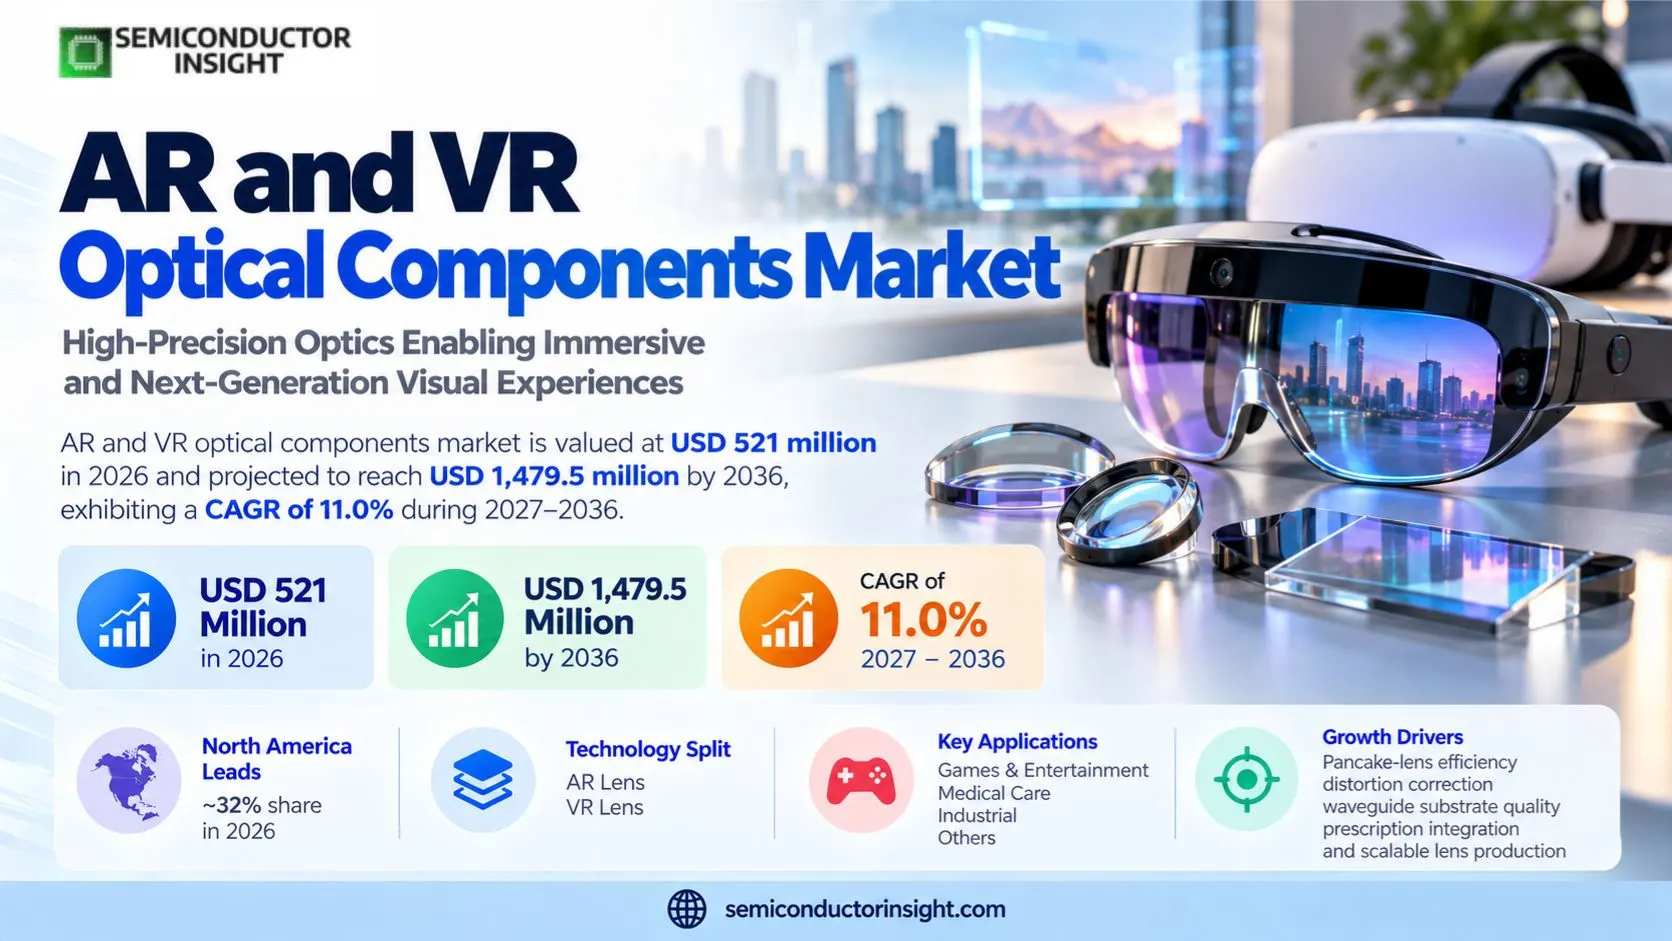
AR and VR Optical components market is valued at USD 521 million in 2026 and projected to reach USD 1,479.5 million by 2036, exhibiting a CAGR of 11.0% during 2027–2036. North America holds the largest estimated revenue share at ~32%, while customer qualification increasingly centers on pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2026 Market Size
USD 521 million
2036 Projected Size
USD 1,479.5 million
CAGR (2027–2036)
11.0%
Largest Market in 2026
North America (~32%)

Key Takeaways

  • Market valuation: AR and VR Optical Components records USD 521 million in 2026 and is projected to reach USD 1,479.5 million by 2036, expanding at 11.0% over 2027–2036. For decisions involving market leadership comparisons, these values follow the specifically defined component-revenue boundary and reflect orders linked to optical performance, qualified manufacturing processes and downstream device integration.
  • Leading product type: VR Lens accounts for an estimated ~56% of 2026 market value, while AR Lens has the highest projected type growth at ~13.7% CAGR. In assessing market leadership comparisons, device program architectures and manufacturability determine the speed of adoption more directly than promotional prototypes.
  • Application composition: Games and Entertainment represents ~54% of base-year demand, and Games and Entertainment grows fastest at ~11.8% CAGR. When selecting suppliers for market leadership comparisons, customers buy qualified optical elements or chips against practical design targets rather than the full price of the downstream device.
  • Geographic leadership: North America has an estimated ~32% 2026 share; North America shows the strongest projected regional growth at ~12.5% CAGR. Design, product adoption and component fabrication can reside in different countries.
  • Primary constraint: The central bottleneck is the combination of pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. For product planning in market leadership comparisons, qualification delays and yield losses can offset shipment growth, while sourcing concentration and high inspection requirements keep small competitors from scaling rapidly.

AR and VR Optical Components Market Overview

AR and VR Optical components market is valued at USD 521 million in 2026 and projected to reach USD 1,479.5 million by 2036, exhibiting a CAGR of 11.0% during 2027–2036. North America holds the largest estimated revenue share at ~32%, while customer qualification increasingly centers on pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production.

Base year: 2026 · Estimated year: 2027 · Forecast period: 2027–2036 · Historical data: 2021–2025 · Values in USD million

AR and VR Optical Components encompasses high-precision near-eye lenses and optical components that shape, magnify, relay or combine images in augmented- and virtual-reality devices. In procurement terms, the category covers AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. Within the technology outlook, this revenue definition matters because equipment sellers, systems integrators and upstream optical suppliers often participate in the same device programs, so applying full device sales values to individual components would overstate the addressable market.

The technology splits into AR Lens and VR Lens. Transparent AR lenses combine transmitted real-world light with projected imagery; waveguide or combiner surfaces constrain thickness, transmission and outdoor readability. Optics can be procured as a component without the microdisplay and frame. Immersive VR lenses redirect image light from internal displays to achieve a wide visual field; Fresnel, aspheric and folded pancake configurations differ in bulk, brightness loss and distortion. Their bill of materials excludes the finished computing headset. For engineers evaluating the technology outlook, optical engineering must be understood with reference to delivered units, reliability and manufacturing tolerances, not only the specifications of individual prototype samples.

Customers primarily use the products in Games and Entertainment, Medical Care, Industrial, Others. Full-immersion VR demands magnification, distortion and low-profile lens packages, whereas transparent AR optics must preserve the real-world scene; buyers specify different test methods. In the commercial context of the technology outlook, a purchase decision can therefore include optical transmission or signal quality, field replacement, electrical interfaces, supply stability and compatibility with the customer’s software or electronics stack.

Apple launched Vision Pro in 2024, updated enterprise spatial-use cases in 2025, and Google extended Android XR support for different display glasses formats. For decisions involving the technology outlook, these examples indicate that suppliers and device architects are making observable technical investments. In assessing the technology outlook, their products occupy different points in the value chain, however, so evidence from product demonstrations should be interpreted as an adoption signal rather than automatically converted into merchant chip or lens revenue.

When selecting suppliers for the technology outlook, the production question is moving from whether individual optical designs are feasible to whether the same specifications can be met across repeated lots. Pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production now shape production cost, design-in risk and the pace at which new customers commit to commercial deliveries. For product planning in the technology outlook, price pressure can persist even when shipments rise, so future revenue depends on both volume and realized value per component.

Segment Analysis: By Type

The market is divided into AR Lens, VR Lens. VR Lens represents ~56% of 2026 revenue, whereas AR Lens advances at an estimated ~13.7% CAGR. Within industry procurement, differences in operating performance, production yield and buyer qualification standards determine how expenditure moves between product types. For engineers evaluating industry procurement, purchasing teams translate type into test metrics, pricing tiers and factory process controls. In the commercial context of industry procurement, suppliers that cannot demonstrate production repeatability face longer qualification cycles even when individual demonstration units perform well.

Type Function Market position
AR Lens For decisions involving AR Lens product qualification, transparent AR lenses combine transmitted real-world light with projected imagery; waveguide or combiner surfaces constrain thickness, transmission and outdoor readability. In the ar and vr optical components commercial chain, the product is evaluated for performance against the target application rather than appearance in a marketing demonstration. In assessing AR Lens product qualification, suppliers also need measurable reliability thresholds and a stable assembly or wafer-processing process to secure recurring contracts. Other 2026 type share (~44%), estimated ~13.7% CAGR. AR Lens occupies a specific engineering and purchase role in this category. For ar and vr optical components, the commercial boundary is AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. When selecting suppliers for AR Lens product qualification, this distinction prevents the same hardware value from being attributed to both an upstream specialist and the downstream device seller. For product planning in AR Lens product qualification, the segment can grow as an alternative technology gains acceptance, but relative market position also reflects the existing qualified customer base and installed production tooling.
VR Lens Within VR Lens product qualification, immersive VR lenses redirect image light from internal displays to achieve a wide visual field; Fresnel, aspheric and folded pancake configurations differ in bulk, brightness loss and distortion. Their bill of materials excludes the finished computing headset. For engineers evaluating VR Lens product qualification, in the ar and vr optical components commercial chain, the product is evaluated for performance against the target application rather than appearance in a marketing demonstration. In the commercial context of VR Lens product qualification, suppliers also need measurable reliability thresholds and a stable assembly or wafer-processing process to secure recurring contracts. Largest 2026 type share (~56%), estimated ~8.3% CAGR. VR Lens occupies a specific engineering and purchase role in this category. Purchasing teams translate vr lens into test metrics, pricing tiers and factory process controls. For decisions involving VR Lens product qualification, suppliers that cannot demonstrate production repeatability face longer qualification cycles even when individual demonstration units perform well. In assessing VR Lens product qualification, the segment can grow as an alternative technology gains acceptance, but relative market position also reflects the existing qualified customer base and installed production tooling.

Segment Analysis: By Application

Application revenue is divided among Games and Entertainment, Medical Care, Industrial, Others. The largest group is Games and Entertainment with ~54% of estimated 2026 component value. Games and Entertainment grows most quickly at ~11.8% CAGR, while different use cases require distinct specifications and payment channels. When selecting suppliers for end-use demand, purchasing teams translate app into test metrics, pricing tiers and factory process controls. For product planning in end-use demand, suppliers that cannot demonstrate production repeatability face longer qualification cycles even when individual demonstration units perform well.

Application Demand characteristics
Games and Entertainment Estimated ~54% of 2026 revenue, ~11.8% CAGR. Entertainment purchases depend on VR headset sales, game libraries, visual comfort and the cost of wide-field, low-distortion lenses suitable for repeated use. Within Games and Entertainment applications, buyers generally request documented quality and application-level testing because the component is incorporated into a larger device or operational workflow. For engineers evaluating Games and Entertainment applications, channel relationships, replacement terms and the expected service life can therefore influence actual spending even when there is clear end-user interest in the application.
Medical Care Estimated ~16% of 2026 revenue, ~11.1% CAGR. Medical visualization requires optics compatible with training workflows, sterilization protocols when applicable, and predictable focus and optical registration. In the commercial context of Medical Care applications, buyers generally request documented quality and application-level testing because the component is incorporated into a larger device or operational workflow. For decisions involving Medical Care applications, channel relationships, replacement terms and the expected service life can therefore influence actual spending even when there is clear end-user interest in the application.
Industrial Estimated ~22% of 2026 revenue, ~9.8% CAGR. Industrial design reviews and remote training prioritize comfort across long sessions, support services and repeatability across fleets of headsets. In assessing Industrial applications, buyers generally request documented quality and application-level testing because the component is incorporated into a larger device or operational workflow. When selecting suppliers for Industrial applications, channel relationships, replacement terms and the expected service life can therefore influence actual spending even when there is clear end-user interest in the application.
Others Estimated ~8% of 2026 revenue, ~7.3% CAGR. Educational and cultural experiences procure devices through institutions, making refurbishment, warranties and distributor support influential demand filters. For product planning in Others applications, buyers generally request documented quality and application-level testing because the component is incorporated into a larger device or operational workflow. Within Others applications, channel relationships, replacement terms and the expected service life can therefore influence actual spending even when there is clear end-user interest in the application.

For engineers evaluating end-use demand, component suppliers typically reach customers via branded hardware manufacturers, manufacturing contractors, optical integrators or equipment distributors. In the commercial context of end-use demand, full-immersion VR demands magnification, distortion and low-profile lens packages, whereas transparent AR optics must preserve the real-world scene; buyers specify different test methods. For decisions involving end-use demand, a systems integrator may validate a complete device, but the upstream specialist still competes on repeatable component specifications. In assessing end-use demand, the resulting purchase orders can be distributed across several countries even for a single end-product program.
Regional Analysis

North America is the largest regional market at an estimated ~32% of 2026 revenue, followed by Asia-Pacific (~31%) and Europe (~25%). North America has the highest modeled growth at ~12.5% CAGR. When selecting suppliers for regional market structure, purchasing teams translate regional into test metrics, pricing tiers and factory process controls. For qualified component buyers, component pricing remains tied to qualified manufacturing output and the responsibility for integration into the final device.

How do the commercial requirements for ar and vr optical components differ by region?

Component demand differs from final device demand. Within regional market structure, in Asia-Pacific, manufacturing programs affect supply pricing and acceptance yield; North American buyers have strong platform and application design influence; European institutions and suppliers contribute optical materials and quality control; South America and the Middle East and Africa commonly purchase through equipment channels. The market model attributes ~31% to Asia-Pacific, ~32% to North America, ~25% to Europe, ~6% to South America and ~6% to Middle East and Africa.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific ~31% share ~11.5% CAGR supplier-side concentration, consumer-device design wins and proximity to precision electronics assembly. During 2026 the estimated market allocation is ~31%, with the forecast window running from 2027 to 2036 across 10 annual intervals. For engineers evaluating Asia-Pacific component purchasing, revenue from 2026 component shipments cannot be extrapolated directly from retail hardware totals. The modeled growth rate of ~11.5% reflects buyer programs and accepted products. China and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. In the commercial context of Asia-Pacific component purchasing, buyers require controlled defect density, production line qualification, competitive landed cost and evidence that quality persists beyond engineering prototypes.. For decisions involving Asia-Pacific component purchasing, this regional purchasing logic affects the price and reliability thresholds applied to 2026 equipment programs and 2027 customer qualifications. The regional allocation of ~31% in the base year, the modelled ~11.5% CAGR, the 2036 horizon and the 10-year growth interval are assumptions for market planning, not values derived from installed-device counts. In assessing Asia-Pacific component purchasing, for ar and vr optical components, the commercial boundary is AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. When selecting suppliers for Asia-Pacific component purchasing, A clear component sales boundary helps customers compare upstream optical specialist contracts against wider systems integration charges for ar and vr optical components qualification in regional sourcing.
North America ~32% share ~12.5% CAGR AR software platforms, cloud computing procurement and high-value customer qualification. During 2026 the estimated market allocation is ~32%, with the forecast window running from 2027 to 2036 across 10 annual intervals. For product planning in North America component purchasing, revenue from 2026 component shipments cannot be extrapolated directly from retail hardware totals. The modeled growth rate of ~12.5% reflects buyer programs and accepted products. U.S. platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. Within North America component purchasing, technology owners prioritize protection of design IP, electrical or optical test traceability, service channels and cross-vendor interchangeability.. For engineers evaluating North America component purchasing, this regional purchasing logic affects the price and reliability thresholds applied to 2026 equipment programs and 2027 customer qualifications. The regional allocation of ~32% in the base year, the modelled ~12.5% CAGR, the 2036 horizon and the 10-year growth interval are assumptions for market planning, not values derived from installed-device counts. In the commercial context of North America component purchasing, purchasing teams translate north america into test metrics, pricing tiers and factory process controls. For decisions involving North America component purchasing, suppliers that cannot demonstrate production repeatability face longer qualification cycles even when individual demonstration units perform well.
Europe ~25% share ~8.9% CAGR specialist optics R&D, materials science, automotive engineering and industrial enterprise demand. During 2026 the estimated market allocation is ~25%, with the forecast window running from 2027 to 2036 across 10 annual intervals. In assessing Europe component purchasing, revenue from 2026 component shipments cannot be extrapolated directly from retail hardware totals. The modeled growth rate of ~8.9% reflects buyer programs and accepted products. European manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. When selecting suppliers for Europe component purchasing, certification programs emphasize optical metrology, sustainability, batch records and reliability in long-running industrial deployments.. The regional allocation of ~25% in the base year, the modelled ~8.9% CAGR, the 2036 horizon and the 10-year growth interval are assumptions for market planning, not values derived from installed-device counts. Within Europe component purchasing, as forecast device architectures change, the important indicator is a qualified optical or semiconductor purchase order, not an announced total device addressable market. Customer programs can require redesigns before reaching stable shipments.
South America ~6% share ~10.1% CAGR imported equipment, specialist industrial installations and relatively small developer ecosystems. During 2026 the estimated market allocation is ~6%, with the forecast window running from 2027 to 2036 across 10 annual intervals. For engineers evaluating South America component purchasing, revenue from 2026 component shipments cannot be extrapolated directly from retail hardware totals. The modeled growth rate of ~10.1% reflects buyer programs and accepted products. Optical demand in Brazil and Chile is driven mainly by imported finished headsets for training, education and specialized deployments, with limited local lens manufacturing. In the commercial context of South America component purchasing, distributors must solve landed-price variability, local calibration, repair logistics and dependable procurement of compatible replacement parts.. For decisions involving South America component purchasing, this regional purchasing logic affects the price and reliability thresholds applied to 2026 equipment programs and 2027 customer qualifications. The regional allocation of ~6% in the base year, the modelled ~10.1% CAGR, the 2036 horizon and the 10-year growth interval are assumptions for market planning, not values derived from installed-device counts. The most meaningful comparison uses pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production together with practical inspection yield and service obligations. These variables affect the revenue recognized at the optical component boundary.
Middle East & Africa ~6% share ~8.9% CAGR project-led digital investment, telecommunications modernization and site-specific industrial use. In assessing Middle East & Africa component purchasing, during 2026 the estimated market allocation is ~6%, with the forecast window running from 2027 to 2036 across 10 annual intervals. When selecting suppliers for Middle East & Africa component purchasing, revenue from 2026 component shipments cannot be extrapolated directly from retail hardware totals. AR/VR projects in Saudi Arabia, the UAE and South Africa depend on system integrators able to support industrial and instructional deployments with locally accessible equipment. For product planning in Middle East & Africa component purchasing, system integrators compete on field support, training, heat tolerance, procurement timing and reliable after-sales maintenance.. Within Middle East & Africa component purchasing, this regional purchasing logic affects the price and reliability thresholds applied to 2026 equipment programs and 2027 customer qualifications. The regional allocation of ~6% in the base year, the modelled ~8.9% CAGR, the 2036 horizon and the 10-year growth interval are assumptions for market planning, not values derived from installed-device counts. For engineers evaluating Middle East & Africa component purchasing, for ar and vr optical components, the commercial boundary is AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. In the commercial context of Middle East & Africa component purchasing, A clear component sales boundary helps customers compare upstream optical specialist contracts against wider systems integration charges for ar and vr optical components qualification in regional sourcing.

Asia-Pacific ~31% SHARE

What determines Asia-Pacific demand for ar and vr optical components?

Asia-Pacific represents an estimated ~31% of global ar and vr optical components revenue in 2026, with modeled expansion of ~11.5% CAGR through 2036. For decisions involving Asia-Pacific component sales, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. In assessing Asia-Pacific component sales, the resulting business model is shaped by supplier-side concentration, consumer-device design wins and proximity to precision electronics assembly. When selecting suppliers for Asia-Pacific component sales, the supply chain differs from that of other regions because platform ownership and physical component manufacturing do not always occupy the same geography.

Market position~31% share
Growth outlook~11.5% CAGR
Demand profilesupplier-side concentration, consumer-device desig
Market access gateBuyers require controlled defect density, production
Country Position in region What drives demand
China Large equipment and OEM accounts For product planning in China optical procurement, china is associated with supplier-side concentration, consumer-device design wins and proximity to precision electronics assembly. Within China optical procurement, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. For engineers evaluating China optical procurement, for procurement in China, relevant evaluation criteria include Buyers require controlled defect density, production line qualification, competitive landed cost and evidence that quality persists beyond engineering prototypes. In the commercial context of China optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For decisions involving China optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
Japan Specialist optical engineering customers In assessing Japan optical procurement, japan is associated with supplier-side concentration, consumer-device design wins and proximity to precision electronics assembly. When selecting suppliers for Japan optical procurement, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. For product planning in Japan optical procurement, for procurement in Japan, relevant evaluation criteria include Buyers require controlled defect density, production line qualification, competitive landed cost and evidence that quality persists beyond engineering prototypes. Within Japan optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For engineers evaluating Japan optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
South Korea Growing regional procurement channel In the commercial context of South Korea optical procurement, south Korea is associated with supplier-side concentration, consumer-device design wins and proximity to precision electronics assembly. For decisions involving South Korea optical procurement, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. In assessing South Korea optical procurement, for procurement in South Korea, relevant evaluation criteria include Buyers require controlled defect density, production line qualification, competitive landed cost and evidence that quality persists beyond engineering prototypes. When selecting suppliers for South Korea optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For product planning in South Korea optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
India Selective project-based opportunities Within India optical procurement, india is associated with supplier-side concentration, consumer-device design wins and proximity to precision electronics assembly. For engineers evaluating India optical procurement, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. In the commercial context of India optical procurement, for procurement in India, relevant evaluation criteria include Buyers require controlled defect density, production line qualification, competitive landed cost and evidence that quality persists beyond engineering prototypes. For decisions involving India optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. In assessing India optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.

Market instances

  • Product and supply context in Asia-Pacific When selecting suppliers for Asia-Pacific supplier selection, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. For product planning in Asia-Pacific supplier selection, this development illustrates why capacity, hardware design and paid component shipments are not interchangeable. Within Asia-Pacific supplier selection, the key commercial effect is on the number and quality of potential component qualifications, rather than an automatically verifiable increase in all regional suppliers’ revenue.
  • Specification and margin pressure in Asia-Pacific Purchasers in Asia-Pacific face an engineering tradeoff involving pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. For engineers evaluating Asia-Pacific supplier selection, each design target changes component acceptance thresholds, and a customer can switch from a complex high-specification part to a simpler part if the total device economics deteriorate. In the commercial context of Asia-Pacific supplier selection, that creates a market in which specifications and yields matter alongside nominal demand.
  • Distribution of commercial value in Asia-Pacific For decisions involving Asia-Pacific supplier selection, the regional value chain links R&D, factory production, product integration and field support, but these steps are frequently in different countries. In assessing Asia-Pacific supplier selection, buyers require controlled defect density, production line qualification, competitive landed cost and evidence that quality persists beyond engineering prototypes. For ar and vr optical components, the revenue assigned to a region should follow the buyer’s recognized component purchase rather than double counting the design location and manufacturing country.
In the full report: country-level units, revenue, supplier relationships and specification-by-application splits across China, Japan, South Korea, India with dedicated estimates for ar and vr optical components procurement.

North America LARGEST · ~32% SHARE · FASTEST-GROWING

What determines North America demand for ar and vr optical components?

North America represents an estimated ~32% of global ar and vr optical components revenue in 2026, with modeled expansion of ~12.5% CAGR through 2036. U.S. When selecting suppliers for North America component sales, platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. For product planning in North America component sales, the resulting business model is shaped by AR software platforms, cloud computing procurement and high-value customer qualification. Within North America component sales, the supply chain differs from that of other regions because platform ownership and physical component manufacturing do not always occupy the same geography.

Market position~32% share
Growth outlook~12.5% CAGR
Demand profileAR software platforms, cloud computing procurement
Market access gateTechnology owners prioritize protection of design IP
Country Position in region What drives demand
United States Large equipment and OEM accounts For engineers evaluating United States optical procurement, united States is associated with AR software platforms, cloud computing procurement and high-value customer qualification. U.S. In the commercial context of United States optical procurement, platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. For decisions involving United States optical procurement, for procurement in United States, relevant evaluation criteria include Technology owners prioritize protection of design IP, electrical or optical test traceability, service channels and cross-vendor interchangeability. In assessing United States optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. When selecting suppliers for United States optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
Canada Specialist optical engineering customers For product planning in Canada optical procurement, canada is associated with AR software platforms, cloud computing procurement and high-value customer qualification. U.S. Within Canada optical procurement, platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. For engineers evaluating Canada optical procurement, for procurement in Canada, relevant evaluation criteria include Technology owners prioritize protection of design IP, electrical or optical test traceability, service channels and cross-vendor interchangeability. In the commercial context of Canada optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For decisions involving Canada optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
Mexico Growing regional procurement channel In assessing Mexico optical procurement, mexico is associated with AR software platforms, cloud computing procurement and high-value customer qualification. U.S. When selecting suppliers for Mexico optical procurement, platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. For product planning in Mexico optical procurement, for procurement in Mexico, relevant evaluation criteria include Technology owners prioritize protection of design IP, electrical or optical test traceability, service channels and cross-vendor interchangeability.

Market instances

  • Product and supply context in North America U.S. In the commercial context of North America supplier selection, platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. North america programs evaluating ar and vr optical components products balance technical conformance, shipment timing and expected maintenance commitments against unit prices.
  • Specification and margin pressure in North America Purchasers in North America face an engineering tradeoff involving pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. Under typical North America programs contract terms, the accepted optical or semiconductor part must meet agreed performance thresholds over multiple manufacturing lots. Before broad deliveries, North America programs assess technical compatibility and test coverage to limit redesign costs and operational disruption.
  • Distribution of commercial value in North America For engineers evaluating North America supplier selection, technology owners prioritize protection of design IP, electrical or optical test traceability, service channels and cross-vendor interchangeability. In the commercial context of North America supplier selection, for ar and vr optical components, the revenue assigned to a region should follow the buyer’s recognized component purchase rather than double counting the design location and manufacturing country.
In the full report: country-level units, revenue, supplier relationships and specification-by-application splits across United States, Canada, Mexico with dedicated estimates for ar and vr optical components procurement.

Europe ~25% SHARE

What determines Europe demand for ar and vr optical components?

Europe represents an estimated ~25% of global ar and vr optical components revenue in 2026, with modeled expansion of ~8.9% CAGR through 2036. For decisions involving Europe component sales, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. In assessing Europe component sales, the resulting business model is shaped by specialist optics R&D, materials science, automotive engineering and industrial enterprise demand. When selecting suppliers for Europe component sales, the supply chain differs from that of other regions because platform ownership and physical component manufacturing do not always occupy the same geography.

Market position~25% share
Growth outlook~8.9% CAGR
Demand profilespecialist optics R&D, materials science, automoti
Market access gateCertification programs emphasize optical metrology,
Country Position in region What drives demand
Germany Large equipment and OEM accounts For product planning in Germany optical procurement, germany is associated with specialist optics R&D, materials science, automotive engineering and industrial enterprise demand. Within Germany optical procurement, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. For engineers evaluating Germany optical procurement, for procurement in Germany, relevant evaluation criteria include Certification programs emphasize optical metrology, sustainability, batch records and reliability in long-running industrial deployments. In the commercial context of Germany optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For decisions involving Germany optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
France Specialist optical engineering customers In assessing France optical procurement, france is associated with specialist optics R&D, materials science, automotive engineering and industrial enterprise demand. When selecting suppliers for France optical procurement, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. For product planning in France optical procurement, for procurement in France, relevant evaluation criteria include Certification programs emphasize optical metrology, sustainability, batch records and reliability in long-running industrial deployments. Within France optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For engineers evaluating France optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
United Kingdom Growing regional procurement channel In the commercial context of United Kingdom optical procurement, united Kingdom is associated with specialist optics R&D, materials science, automotive engineering and industrial enterprise demand. For decisions involving United Kingdom optical procurement, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. In assessing United Kingdom optical procurement, for procurement in United Kingdom, relevant evaluation criteria include Certification programs emphasize optical metrology, sustainability, batch records and reliability in long-running industrial deployments. When selecting suppliers for United Kingdom optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. For product planning in United Kingdom optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
Finland Selective project-based opportunities Within Finland optical procurement, finland is associated with specialist optics R&D, materials science, automotive engineering and industrial enterprise demand. For engineers evaluating Finland optical procurement, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. In the commercial context of Finland optical procurement, for procurement in Finland, relevant evaluation criteria include Certification programs emphasize optical metrology, sustainability, batch records and reliability in long-running industrial deployments. For decisions involving Finland optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. In assessing Finland optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.

Market instances

  • Product and supply context in Europe When selecting suppliers for Europe supplier selection, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. For product planning in Europe supplier selection, this development illustrates why capacity, hardware design and paid component shipments are not interchangeable. Within Europe supplier selection, the key commercial effect is on the number and quality of potential component qualifications, rather than an automatically verifiable increase in all regional suppliers’ revenue.
  • Specification and margin pressure in Europe Purchasers in Europe face an engineering tradeoff involving pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. For engineers evaluating Europe supplier selection, each design target changes component acceptance thresholds, and a customer can switch from a complex high-specification part to a simpler part if the total device economics deteriorate. In the commercial context of Europe supplier selection, that creates a market in which specifications and yields matter alongside nominal demand.
  • Distribution of commercial value in Europe For decisions involving Europe supplier selection, the regional value chain links R&D, factory production, product integration and field support, but these steps are frequently in different countries. In assessing Europe supplier selection, certification programs emphasize optical metrology, sustainability, batch records and reliability in long-running industrial deployments. When selecting suppliers for Europe supplier selection, for ar and vr optical components, the revenue assigned to a region should follow the buyer’s recognized component purchase rather than double counting the design location and manufacturing country.
In the full report: country-level units, revenue, supplier relationships and specification-by-application splits across Germany, France, United Kingdom, Finland with dedicated estimates for ar and vr optical components procurement.

South America ~6% SHARE

What determines South America demand for ar and vr optical components?

South America represents an estimated ~6% of global ar and vr optical components revenue in 2026, with modeled expansion of ~10.1% CAGR through 2036. For product planning in South America component sales, optical demand in Brazil and Chile is driven mainly by imported finished headsets for training, education and specialized deployments, with limited local lens manufacturing. Within South America component sales, the resulting business model is shaped by imported equipment, specialist industrial installations and relatively small developer ecosystems. For engineers evaluating South America component sales, the supply chain differs from that of other regions because platform ownership and physical component manufacturing do not always occupy the same geography.

Market position~6% share
Growth outlook~10.1% CAGR
Demand profileimported equipment, specialist industrial installa
Market access gateDistributors must solve landed-price variability, lo
Country Position in region What drives demand
Brazil Large equipment and OEM accounts In the commercial context of Brazil optical procurement, brazil is associated with imported equipment, specialist industrial installations and relatively small developer ecosystems. For decisions involving Brazil optical procurement, optical demand in Brazil and Chile is driven mainly by imported finished headsets for training, education and specialized deployments, with limited local lens manufacturing. In assessing Brazil optical procurement, for procurement in Brazil, relevant evaluation criteria include Distributors must solve landed-price variability, local calibration, repair logistics and dependable procurement of compatible replacement parts.
Argentina Specialist optical engineering customers Within Argentina optical procurement, argentina is associated with imported equipment, specialist industrial installations and relatively small developer ecosystems. For engineers evaluating Argentina optical procurement, optical demand in Brazil and Chile is driven mainly by imported finished headsets for training, education and specialized deployments, with limited local lens manufacturing. In the commercial context of Argentina optical procurement, for procurement in Argentina, relevant evaluation criteria include Distributors must solve landed-price variability, local calibration, repair logistics and dependable procurement of compatible replacement parts. For decisions involving Argentina optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. In assessing Argentina optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
Chile Growing regional procurement channel When selecting suppliers for Chile optical procurement, chile is associated with imported equipment, specialist industrial installations and relatively small developer ecosystems. For product planning in Chile optical procurement, optical demand in Brazil and Chile is driven mainly by imported finished headsets for training, education and specialized deployments, with limited local lens manufacturing. Within Chile optical procurement, for procurement in Chile, relevant evaluation criteria include Distributors must solve landed-price variability, local calibration, repair logistics and dependable procurement of compatible replacement parts. For engineers evaluating Chile optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. In the commercial context of Chile optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.

Market instances

  • Product and supply context in South America For decisions involving South America supplier selection, optical demand in Brazil and Chile is driven mainly by imported finished headsets for training, education and specialized deployments, with limited local lens manufacturing. In assessing South America supplier selection, this development illustrates why capacity, hardware design and paid component shipments are not interchangeable. When selecting suppliers for South America supplier selection, the key commercial effect is on the number and quality of potential component qualifications, rather than an automatically verifiable increase in all regional suppliers’ revenue.
  • Specification and margin pressure in South America Purchasers in South America face an engineering tradeoff involving pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. For product planning in South America supplier selection, each design target changes component acceptance thresholds, and a customer can switch from a complex high-specification part to a simpler part if the total device economics deteriorate. Within South America supplier selection, that creates a market in which specifications and yields matter alongside nominal demand.
  • Distribution of commercial value in South America For engineers evaluating South America supplier selection, the regional value chain links R&D, factory production, product integration and field support, but these steps are frequently in different countries. In the commercial context of South America supplier selection, distributors must solve landed-price variability, local calibration, repair logistics and dependable procurement of compatible replacement parts. For decisions involving South America supplier selection, for ar and vr optical components, the revenue assigned to a region should follow the buyer’s recognized component purchase rather than double counting the design location and manufacturing country.
In the full report: country-level units, revenue, supplier relationships and specification-by-application splits across Brazil, Argentina, Chile with dedicated estimates for ar and vr optical components procurement.

Middle East & Africa ~6% SHARE

What determines Middle East & Africa demand for ar and vr optical components?

Middle East & Africa represents an estimated ~6% of global ar and vr optical components revenue in 2026, with modeled expansion of ~8.9% CAGR through 2036. In assessing Middle East & Africa component sales, aR/VR projects in Saudi Arabia, the UAE and South Africa depend on system integrators able to support industrial and instructional deployments with locally accessible equipment. When selecting suppliers for Middle East & Africa component sales, the resulting business model is shaped by project-led digital investment, telecommunications modernization and site-specific industrial use. For product planning in Middle East & Africa component sales, the supply chain differs from that of other regions because platform ownership and physical component manufacturing do not always occupy the same geography.

Market position~6% share
Growth outlook~8.9% CAGR
Demand profileproject-led digital investment, telecommunications
Market access gateSystem integrators compete on field support, trainin
Country Position in region What drives demand
United Arab Emirates Large equipment and OEM accounts Within United Arab Emirates optical procurement, united Arab Emirates is associated with project-led digital investment, telecommunications modernization and site-specific industrial use. For engineers evaluating United Arab Emirates optical procurement, aR/VR projects in Saudi Arabia, the UAE and South Africa depend on system integrators able to support industrial and instructional deployments with locally accessible equipment. In the commercial context of United Arab Emirates optical procurement, for procurement in United Arab Emirates, relevant evaluation criteria include System integrators compete on field support, training, heat tolerance, procurement timing and reliable after-sales maintenance. For decisions involving United Arab Emirates optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. In assessing United Arab Emirates optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
Saudi Arabia Specialist optical engineering customers When selecting suppliers for Saudi Arabia optical procurement, saudi Arabia is associated with project-led digital investment, telecommunications modernization and site-specific industrial use. For product planning in Saudi Arabia optical procurement, aR/VR projects in Saudi Arabia, the UAE and South Africa depend on system integrators able to support industrial and instructional deployments with locally accessible equipment. Within Saudi Arabia optical procurement, for procurement in Saudi Arabia, relevant evaluation criteria include System integrators compete on field support, training, heat tolerance, procurement timing and reliable after-sales maintenance. For engineers evaluating Saudi Arabia optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. In the commercial context of Saudi Arabia optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.
South Africa Growing regional procurement channel For decisions involving South Africa optical procurement, south Africa is associated with project-led digital investment, telecommunications modernization and site-specific industrial use. In assessing South Africa optical procurement, aR/VR projects in Saudi Arabia, the UAE and South Africa depend on system integrators able to support industrial and instructional deployments with locally accessible equipment. When selecting suppliers for South Africa optical procurement, for procurement in South Africa, relevant evaluation criteria include System integrators compete on field support, training, heat tolerance, procurement timing and reliable after-sales maintenance. For product planning in South Africa optical procurement, a local channel may purchase devices rather than merchant components, so quantities cannot be inferred directly from system deployments. Within South Africa optical procurement, the component opportunity is strongest when a supplier can document accepted specifications, supply terms and replacement obligations.

Market instances

  • Product and supply context in Middle East & Africa For engineers evaluating Middle East & Africa supplier selection, aR/VR projects in Saudi Arabia, the UAE and South Africa depend on system integrators able to support industrial and instructional deployments with locally accessible equipment. In the commercial context of Middle East & Africa supplier selection, this development illustrates why capacity, hardware design and paid component shipments are not interchangeable. For decisions involving Middle East & Africa supplier selection, the key commercial effect is on the number and quality of potential component qualifications, rather than an automatically verifiable increase in all regional suppliers’ revenue.
  • Specification and margin pressure in Middle East & Africa Purchasers in Middle East & Africa face an engineering tradeoff involving pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. In assessing Middle East & Africa supplier selection, each design target changes component acceptance thresholds, and a customer can switch from a complex high-specification part to a simpler part if the total device economics deteriorate. When selecting suppliers for Middle East & Africa supplier selection, that creates a market in which specifications and yields matter alongside nominal demand.
  • Distribution of commercial value in Middle East & Africa For product planning in Middle East & Africa supplier selection, the regional value chain links R&D, factory production, product integration and field support, but these steps are frequently in different countries. Within Middle East & Africa supplier selection, system integrators compete on field support, training, heat tolerance, procurement timing and reliable after-sales maintenance. For engineers evaluating Middle East & Africa supplier selection, for ar and vr optical components, the revenue assigned to a region should follow the buyer’s recognized component purchase rather than double counting the design location and manufacturing country.
In the full report: country-level units, revenue, supplier relationships and specification-by-application splits across United Arab Emirates, Saudi Arabia, South Africa with dedicated estimates for ar and vr optical components procurement.

Competitive Landscape

The market includes direct makers of ar and vr optical components products plus upstream and downstream firms serving the same technology ecosystem. In the commercial context of competitive positioning, apple launched Vision Pro in 2024, updated enterprise spatial-use cases in 2025, and Google extended Android XR support for different display glasses formats. For decisions involving competitive positioning, current strategy is organized around manufacturable differentiation, long qualification cycles, materials supply, pricing discipline and access to customers that can commit to recurring production.

Commercial competition spans companies named in the product ecosystem, including Radiant Vision Systems; Carl Zeiss AG; Avantier; Corning; Nalux. In assessing competitive positioning, apple launched Vision Pro in 2024, updated enterprise spatial-use cases in 2025, and Google extended Android XR support for different display glasses formats. When selecting suppliers for competitive positioning, such developments demonstrate visible technical activity but do not by themselves confirm market shares across the entire vendor universe. For product planning in competitive positioning, supplier comparisons must distinguish finished device vendors, component makers, specialized foundries and optical test suppliers.

The central differentiator is pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. Within competitive positioning, customers run qualification programs to determine whether each device meets the intended link, near-eye display or sensing application. For engineers evaluating competitive positioning, successful qualification may lead to repeated production orders, but minimum order quantities, warranty commitments and engineering changes can reshape supplier positioning during the forecast period.

In the commercial context of competitive positioning, supply-chain partnerships can allow a small design company to commercialize a technology without owning every manufacturing stage. For decisions involving competitive positioning, the commercial benefit depends on transfer of process know-how, quality control and intellectual property, not just a press release announcing collaboration. In assessing competitive positioning, as forecast device architectures change, the important indicator is a qualified optical or semiconductor purchase order, not an announced total device addressable market. Customer programs can require redesigns before reaching stable shipments.

Pricing competition should be evaluated against performance and recognized product boundary. In ar and vr optical components, headline downstream hardware revenue includes costs for displays, electronics, mechanical housings and software that do not accrue to each optical specialist. When selecting suppliers for competitive positioning, a practical competitive review isolates component shipments, gross margin sensitivity, dependence on key design wins and exposure to alternative architectures.

Tier structure

Tier Companies Basis of competition
Tier 1 Radiant Vision Systems; Carl Zeiss AG; Avantier; Corning; Nalux For the ar and vr optical components category, pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production define meaningful competitive capability. For product planning in supplier-tier comparison, some named firms may supply testing services, finished systems or materials rather than merchant optical components, so the buyer must establish the exact sold-product boundary.
Tier 2 Sunny Optical Technology; Fujian Fran Optics; Ningbo Jinhui Optical Technology; Yejia Optical Technology; Dongguan Yutong Optical Technology; Goertek Optical Technology Technology specialists compete through specific designs and customer qualification programs. Those suppliers can win niche contracts even without broad device portfolios, because pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production can create difficult performance thresholds. Within supplier-tier comparison, revenue concentration is shaped by actual qualified production orders and renewal cycles, not by a simple count of patents or demonstration units.
Ecosystem Suzhou Lylap Optical Technology; SYPO; IDTE; Zhongshan Zhongying Optical; Dongguan Lianlong Photoelectric Technology For engineers evaluating supplier-tier comparison, the broader ecosystem includes component fabricators, materials specialists, test-equipment developers and downstream equipment integrators. In the commercial context of supplier-tier comparison, their participation demonstrates a relevant technical role but does not establish direct merchant-market share. For decisions involving supplier-tier comparison, integrators and legacy brand names should be identified separately from active production suppliers to prevent double counting and overstated consolidation. In assessing supplier-tier comparison, commercial orders therefore depend on a customer qualification sequence that confirms performance at the specified operating conditions, acceptable manufacturing yield, traceable component sourcing, and continuity of supply through the complete product lifecycle. When selecting suppliers for supplier-tier comparison, this separates near-term prototypes from repeatable annual revenue and makes customer acceptance economically decisive.

Key companies profiled

  • Radiant Vision Systems
  • Carl Zeiss AG
  • Avantier
  • Corning
  • Nalux
  • Sunny Optical Technology
  • Fujian Fran Optics
  • Ningbo Jinhui Optical Technology
  • Yejia Optical Technology
  • Dongguan Yutong Optical Technology
  • Goertek Optical Technology
  • Suzhou Lylap Optical Technology
  • SYPO
  • IDTE
  • Zhongshan Zhongying Optical
  • Dongguan Lianlong Photoelectric Technology

Production Capacity Analysis

Production readiness for ar and vr optical components is measured by output of qualified component lots, not merely announced equipment capacity. For product planning in manufacturing capacity planning, the practical supply chain ranges from specialized raw inputs and optical fabrication through testing, final assembly and supply to device or networking OEMs. Accepted yield and stable specifications determine monetizable capacity.

Physical production involves different facilities depending on the selected design. For ar and vr optical components, relevant fabrication and assembly steps include pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. Within manufacturing capacity planning, capacity figures based on semiconductor wafers, glass substrates or finished devices are not interchangeable. For engineers evaluating manufacturing capacity planning, the effective annual output is the quantity that passes customer-specific testing with an acceptable yield.

In the commercial context of manufacturing capacity planning, international supply is structured around specialized material makers, process-tool suppliers, component manufacturers and end-product assemblers. For decisions involving manufacturing capacity planning, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. In assessing manufacturing capacity planning, european manufacturers including Carl Zeiss, SCHOTT and Finnish waveguide developers maintain competencies in metrology, high-index materials and engineered optical interfaces. When selecting suppliers for manufacturing capacity planning, manufacturers use international partners to source proprietary input materials while keeping design and final quality assurance closer to their key customers.

Upstream bottlenecks can shift even where visible production equipment is available. For product planning in manufacturing capacity planning, shortages of properly specified material, testing time, qualified packaging or customer approval can limit output. Pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production are therefore central considerations in assessing whether announced new capacity will produce saleable parts. Within manufacturing capacity planning, a supplier’s expansion plan is commercially meaningful only when yield and quality are verified.

Market Dynamics

For engineers evaluating market demand and production planning, they illustrate why the market can grow while individual suppliers experience cost inflation, delays, price erosion or shifts toward alternative component designs. In the commercial context of market demand and production planning, purchasing teams translate dyn into test metrics, pricing tiers and factory process controls. For decisions involving market demand and production planning, suppliers that cannot demonstrate production repeatability face longer qualification cycles even when individual demonstration units perform well.

MARKET DRIVERS

Drivers Impact Analysis*

Driver (~) % impact on CAGR forecast Geographic relevance Impact timeline
Downstream product launches and developer support +2.4% Global OEMs 2026–2030
Increased performance requirements +1.7% North America and Asia-Pacific 2027–2034
Supplier investment in scalable processing +1.2% Asian and European fabs 2026–2032
Enterprise deployment and device qualification +0.9% North America and Europe 2028–2036
Channel and service expansion +0.6% Global 2027–2035

Downstream product launches and developer support

Downstream product launches and developer support. In assessing market demand and production planning, apple launched Vision Pro in 2024, updated enterprise spatial-use cases in 2025, and Google extended Android XR support for different display glasses formats. When selecting suppliers for market demand and production planning, customer demand can expand once the equipment ecosystem aligns product capability with software and support. For product planning in market demand and production planning, this is a stronger route to component orders than a prototype demonstration without a committed production timeline.

Increased performance requirements

Increased performance requirements. Within market demand and production planning, end-product designers require higher optical quality while limiting power, weight, thermal load or link loss. Pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production consequently determine which suppliers can satisfy next-generation technical specifications. For engineers evaluating market demand and production planning, improved component capability can raise value per accepted unit even if a system producer reduces other bill-of-material expenses.

Supplier investment in scalable processing

Supplier investment in scalable processing. In the commercial context of market demand and production planning, new equipment and manufacturing agreements can increase the pool of qualified product sources. For decisions involving market demand and production planning, the main challenge is moving from a viable laboratory device to repeated batches with consistent performance. In assessing market demand and production planning, customers consider inspection records, process-transfer controls, wafer or substrate quality and realistic capacity commitments before broad deployment. When selecting suppliers for market demand and production planning, commercial orders therefore depend on a customer qualification sequence that confirms performance at the specified operating conditions, acceptable manufacturing yield, traceable component sourcing, and continuity of supply through the complete product lifecycle. For product planning in market demand and production planning, this separates near-term prototypes from repeatable annual revenue and makes customer acceptance economically decisive.

Enterprise deployment and device qualification

Enterprise deployment and device qualification. Within market demand and production planning, full-immersion VR demands magnification, distortion and low-profile lens packages, whereas transparent AR optics must preserve the real-world scene; buyers specify different test methods. For engineers evaluating market demand and production planning, mature customer accounts increasingly seek supplier documentation, training, replacement parts and compatibility across successive device models. In the commercial context of market demand and production planning, these requirements favor participants that can sustain a product roadmap while supporting field-installed equipment.

MARKET RESTRAINTS

Restraints Impact Analysis*

Restraint (~) % impact on CAGR forecast Geographic relevance Impact timeline
Yield variation and inspection cost −1.6% Global production 2026–2032
Price pressure on component suppliers −1.2% Global procurement 2026–2036
Platform redesign and qualification delays −0.9% North American OEMs 2027–2033
Materials and geography concentration −0.6% Global upstream supply 2026–2034

Yield variation and inspection cost

Yield variation and inspection cost. Production yield is sensitive to pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. For decisions involving market demand and production planning, slight dimensional or electrical deviations can turn otherwise fabricated units into unshippable inventory. In assessing market demand and production planning, supplier economics deteriorate if upstream wafer or substrate investment is committed before the customer has frozen the specification and agreed on acceptance testing.

Price pressure on component suppliers

Price pressure on component suppliers. AR and VR Optical Components buying teams considering procurement specialists require repeatable measurement and traceable production records before transferring a design into recurring orders. A supplier selling only the ar and vr optical components component does not collect downstream electronics, frame, headset or systems revenue, so comparing its gross sales with final consumer-device pricing can hide serious margin pressure.

Platform redesign and qualification delays

Platform redesign and qualification delays. When selecting suppliers for market demand and production planning, large buyers frequently adjust architecture, industrial design and software functions before market launch. For product planning in market demand and production planning, each meaningful change may trigger another optical or chip qualification cycle and can invalidate tooling choices. Within market demand and production planning, the supplier bears engineering and inventory risk during this interval while headline shipment forecasts remain uncertain.

Materials and geography concentration

Materials and geography concentration. Input materials and specialized manufacturing know-how can be geographically concentrated. For decisions involving market demand and production planning, china and Japan supply precision optics and device integration, with Goertek presenting its full-color glasses design in January 2026; lens finishing and headset assembly remain separate revenue layers. In assessing market demand and production planning, trade restrictions, international logistics, single-source tooling and long test cycles create separate risks that buyers try to reduce through second-source development and design flexibility.

MARKET OPPORTUNITIES

Specialized high-performance product niches

Specialized high-performance product niches. High-specification niches offer opportunities where customers will pay for verified advantages in pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production. When selecting suppliers for market demand and production planning, those programs can be attractive even at moderate unit volumes if the supplier offers documentation, calibration and long-term availability that lower device-lifecycle risk.

Supplier-specific repeatable production programs

Supplier-specific repeatable production programs. For product planning in market demand and production planning, partners able to transfer optical design into repeatable processes can secure longer-running manufacturing contracts. Within market demand and production planning, the decisive commercial milestone is a locked specification with measurable yield and quality, not the first visible prototype. For engineers evaluating market demand and production planning, as production volume increases, procurement tends to reward consistent suppliers with fewer returns. In the commercial context of market demand and production planning, commercial orders therefore depend on a customer qualification sequence that confirms performance at the specified operating conditions, acceptable manufacturing yield, traceable component sourcing, and continuity of supply through the complete product lifecycle. For decisions involving market demand and production planning, this separates near-term prototypes from repeatable annual revenue and makes customer acceptance economically decisive.

Growth in industrial and professional workflows

Growth in industrial and professional workflows. In assessing market demand and production planning, full-immersion VR demands magnification, distortion and low-profile lens packages, whereas transparent AR optics must preserve the real-world scene; buyers specify different test methods. When selecting suppliers for market demand and production planning, specialized organizations can justify higher component costs when they receive demonstrable operational benefits. For product planning in market demand and production planning, producers can tailor optics or chip performance for these needs and build defensible relationships through support, training and application engineering rather than competing only on catalog unit price.

More integrated platform architectures

More integrated platform architectures. Within market demand and production planning, closer integration of optics, sensing, electrical control and software may change which firms capture value. For engineers evaluating market demand and production planning, component specialists should establish whether a new design moves functions into an integrated module or separates them into merchant parts. In the commercial context of market demand and production planning, either choice can create a new route to market while reducing demand for an older standalone product.

Supply Chain Analysis

The ar and vr optical components value chain begins with specialized inputs, moves through component fabrication and qualification, and ends when an integrator incorporates the device into a functioning product. Distinguishing each transfer point avoids double counting sales. For decisions involving supply-chain selection, supplier profitability depends on yield and technical acceptance before a commercial lot reaches its buyer.

Upstream materialsIn assessing supply-chain selection, the component chain starts with semiconductor materials, optical glass or polymer inputs selected according to the architecture. Quality thresholds, contamination control and traceability matter before fabrication begins. Pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production also determine whether input batches can be substituted without customer requalification. When selecting suppliers for supply-chain selection, commercial orders therefore depend on a customer qualification sequence that confirms performance at the specified operating conditions, acceptable manufacturing yield, traceable component sourcing, and continuity of supply through the complete product lifecycle. For product planning in supply-chain selection, this separates near-term prototypes from repeatable annual revenue and makes customer acceptance economically decisive.
Manufacturing and packagingFabrication and packaging translate material performance into usable parts. For component supply-chain teams, component pricing remains tied to qualified manufacturing output and the responsibility for integration into the final device. Component supply-chain teams evaluating ar and vr optical components products balance technical conformance, shipment timing and expected maintenance commitments against unit prices.
OEM and systems channelsIn assessing supply-chain selection, displays, network hardware and consumer equipment are commonly sold through integrators or device-brand supply chains. When selecting suppliers for supply-chain selection, the merchant component producer may face multiple customer qualification stages before its part is named in a recurring supply contract. Under typical component supply-chain teams contract terms, the accepted optical or semiconductor part must meet agreed performance thresholds over multiple manufacturing lots.
End applicationsEnd use is represented by Games and Entertainment, Medical Care, Industrial, Others. For engineers evaluating supply-chain selection, the delivered customer benefit depends on performance at the complete equipment level, making repairs, interoperability, training and application-specific reliability significant procurement variables. Distributors influence regional availability where direct local fabrication is limited. Before broad deliveries, component supply-chain teams assess technical compatibility and test coverage to limit redesign costs and operational disruption.

Upstream materials. Quality thresholds, contamination control and traceability matter before fabrication begins. When selecting suppliers for supply-chain selection, pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production also determine whether input batches can be substituted without customer requalification. For product planning in supply-chain selection, for ar and vr optical components, the commercial boundary is AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. Within supply-chain selection, A clear component sales boundary helps customers compare upstream optical specialist contracts against wider systems integration charges for ar and vr optical components qualification in supply sourcing.

Manufacturing and packaging. Fabrication and packaging translate material performance into usable parts. For engineers evaluating supply-chain selection, process records and final inspection must demonstrate reliability across repeated batches rather than only meeting one prototype specification. In the commercial context of supply-chain selection, unstable yield and expensive testing can constrain shipment volume regardless of end-customer interest. For decisions involving supply-chain selection, purchasing teams translate manufacturing and packaging into test metrics, pricing tiers and factory process controls. In assessing supply-chain selection, suppliers that cannot demonstrate production repeatability face longer qualification cycles even when individual demonstration units perform well.

OEM and systems channels. When selecting suppliers for supply-chain selection, displays, network hardware and consumer equipment are commonly sold through integrators or device-brand supply chains. For product planning in supply-chain selection, the merchant component producer may face multiple customer qualification stages before its part is named in a recurring supply contract. Within supply-chain selection, as forecast device architectures change, the important indicator is a qualified optical or semiconductor purchase order, not an announced total device addressable market. Customer programs can require redesigns before reaching stable shipments.

End applications. AR and VR Optical Components buying teams considering component supply-chain teams require repeatable measurement and traceable production records before transferring a design into recurring orders. Distributors influence regional availability where direct local fabrication is limited. In the commercial context of supply-chain selection, the most meaningful comparison uses pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production together with practical inspection yield and service obligations. These variables affect the revenue recognized at the optical component boundary.

Recent Developments

  • 1 September 2026 Announced
    For decisions involving dated technology developments, lumus and Quanta announced an expanded licensing agreement addressing thinner and less costly reflective waveguides for AR eyewear. In assessing dated technology developments, the agreement is commercially relevant to scalable supply and production transfer, though licensing announcements do not establish current device shipments or the market share of every optical supplier. Source
  • 19 May 2026 Published
    Within dated technology developments, google outlined Android XR developer preview work to standardize software support across headsets, tethered display glasses and other eyewear form factors. For engineers evaluating dated technology developments, optical hardware suppliers benefit from coherent device platforms when customers can connect components to real application demand; the update does not itself announce a waveguide purchase quantity. Source
  • 9 January 2026 Announced
    In assessing dated technology developments, goertek presented its binocular full-color display glasses reference design at CES 2026, combining an etched optical waveguide and small light engine. The architecture demonstrates component-level integration requirements and supports customer testing. When selecting suppliers for dated technology developments, it should be separated from committed commercial volumes of any individual optical component or lens category. For product planning in dated technology developments, commercial orders therefore depend on a customer qualification sequence that confirms performance at the specified operating conditions, acceptable manufacturing yield, traceable component sourcing, and continuity of supply through the complete product lifecycle. Within dated technology developments, this separates near-term prototypes from repeatable annual revenue and makes customer acceptance economically decisive. Source
  • 8 December 2025 Published
    For engineers evaluating dated technology developments, google described continuing Android XR device and developer ecosystem expansion after the initial platform launch. In the commercial context of dated technology developments, a larger supply of compatible applications can improve the business case for near-eye optics, but manufacturing remains gated by device comfort, display power and certified image performance rather than software features alone. Source
  • 29 September 2025 Announced
    When selecting suppliers for dated technology developments, sCHOTT said it had achieved serial production of geometric reflective waveguides using an integrated glass, coating and processing supply chain. For product planning in dated technology developments, the specific manufacturing step matters because it moves an optical design beyond purely experimental fabrication toward repeatable output, although supplier revenue still depends on orders and accepted shipments. Source
  • 26 August 2025 Published
    In the commercial context of dated technology developments, dispelix and Eulitha described a lithography and etching method for tall, precisely patterned optical structures. For decisions involving dated technology developments, their development addresses a real factory issue for advanced diffractive displays, namely transfer of nanoscale structures while retaining optical fidelity. In assessing dated technology developments, its effect is on potential process yield and design freedom, not an independently verified global market figure. Source
  • 22 April 2025 Announced
    When selecting suppliers for dated technology developments, dispelix and Mitsui Chemicals presented a polymer waveguide demonstration with a light single eyepiece. For product planning in dated technology developments, polymer substrates can reduce product weight and affect handling safety but need the same optical qualification and reliability checks as glass. This is relevant to material substitution in optical component supply chains. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study period 2021–2036
Historical period 2021–2025
Base year 2026
Estimated year 2027
Forecast period 2027–2036
2026 market size USD 521 million
2027 estimated size USD 578.4 million
2036 market size USD 1,479.5 million
CAGR 2027–2036 11.0%
Unit Component market revenue in USD million
By Type AR Lens · VR Lens
By Application Games and Entertainment · Medical Care · Industrial · Others
By Region Country coverage and five mutually exclusive region groups:
Asia-PacificChina, Japan, South Korea, India
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, United Kingdom, Finland
South AmericaBrazil, Argentina, Chile
Middle East & AfricaUnited Arab Emirates, Saudi Arabia, South Africa
Key Companies Profiled Radiant Vision Systems; Carl Zeiss AG; Avantier; Corning; Nalux; Sunny Optical Technology; Fujian Fran Optics; Ningbo Jinhui Optical Technology; Yejia Optical Technology; Dongguan Yutong Optical Technology; Goertek Optical Technology; Suzhou Lylap Optical Technology; SYPO; IDTE; Zhongshan Zhongying Optical; Dongguan Lianlong Photoelectric Technology
Customization Scope Country-level component revenue and supplier comparison for ar and vr optical components, including volume, customer qualification, technology splits and value-chain boundaries.

Frequently Asked Questions

How large is the ar and vr optical components market and how fast will it grow?

The global ar and vr optical components market measures USD 521 million in 2026 and is projected to reach USD 1,479.5 million by 2036, corresponding to 11.0% across 2027–2036. It includes AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. In the commercial context of customer inquiry and scope clarification, the series follows the defined merchant component value rather than total hardware or system sales, which would substantially broaden the revenue measure.

Which ar and vr optical components product type holds the highest share?

VR Lens has an estimated ~56% base-year share, while AR Lens shows the fastest expected expansion at ~13.7% CAGR. For decisions involving customer inquiry and scope clarification, immersive VR lenses redirect image light from internal displays to achieve a wide visual field; Fresnel, aspheric and folded pancake configurations differ in bulk, brightness loss and distortion. Their bill of materials excludes the finished computing headset. In assessing customer inquiry and scope clarification, product types have distinct qualification requirements, so a high-performance prototype does not automatically displace currently shipping products.

Which application is the largest demand category?

Games and Entertainment accounts for an estimated ~54% of 2026 revenue; Games and Entertainment is fastest-growing at ~11.8% CAGR. VR optics orders reflect active headset programs, user visual comfort, optical clarity and total lens costs, not simply announcements of new entertainment software for ar and vr optical components qualification in faq sourcing. When selecting suppliers for customer inquiry and scope clarification, buyers typically qualify a component against their system requirements before placing repeat orders, which shapes the timing and quality of recognized component demand.

Which region leads the ar and vr optical components market?

North America represents the largest regional share at an estimated ~32% in 2026, while North America has an estimated ~12.5% CAGR. U.S. For product planning in customer inquiry and scope clarification, platform buyers such as Meta, Google and Apple drive subsystem qualification, product ergonomics and developer functionality even when many lenses are fabricated offshore. Within customer inquiry and scope clarification, these figures describe estimated component-market revenue by purchasing region, not final-device sales, production-factory counts or the number of patents issued in each country.

What manufacturing factors most affect ar and vr optical components margins?

Pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production determine output quality, yield and the cost of customer acceptance. For engineers evaluating customer inquiry and scope clarification, a facility may be technically capable of fabrication yet lack a qualified process for a demanding device specification. In the commercial context of customer inquiry and scope clarification, suppliers therefore manage materials qualification, inspection throughput, rejects, lot traceability and long-term agreements when deciding whether to expand capacity.

How are the components sold to downstream manufacturers?

For decisions involving customer inquiry and scope clarification, full-immersion VR demands magnification, distortion and low-profile lens packages, whereas transparent AR optics must preserve the real-world scene; buyers specify different test methods. In assessing customer inquiry and scope clarification, in many cases components are delivered through original equipment manufacturers, subsystem integrators or contract manufacturers rather than to the final customer. This separation matters when comparing procurement values with hardware retail sales. When selecting suppliers for customer inquiry and scope clarification, a component seller needs a clear acceptance protocol, delivery schedule and warranty terms before revenue becomes recurring.

How does product design affect market forecasting?

For product planning in customer inquiry and scope clarification, changes in hardware dimensions, display resolution, link bandwidth or power can alter the required optical design. For ar and vr optical components, the customer may revisit pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production as a result. Within customer inquiry and scope clarification, technical development is therefore most useful for understanding potential adoption paths; it cannot replace evidence of production orders and accepted manufacturing output.

What are the main regional differences in adoption?

For engineers evaluating customer inquiry and scope clarification, asia-Pacific combines component supply chains with sizable device manufacturing, while North America has substantial platform ownership and hyperscale or consumer-device procurement. Europe adds optical research, materials capability and industrial qualification. For qualified component buyers, component pricing remains tied to qualified manufacturing output and the responsibility for integration into the final device for the current device qualification cycle. Relative shares are estimated at ~31%, ~32%, ~25%, ~6% and ~6%, respectively.

What are the leading commercial risks for ar and vr optical components producers?

In the commercial context of customer inquiry and scope clarification, manufacturers face process-yield variability, customer specification changes, pressure on unit prices and concentrated input supply. Pancake-lens efficiency, distortion correction, waveguide substrate quality, prescription integration and scalable lens production create additional process-specific barriers. For decisions involving customer inquiry and scope clarification, even when total device shipments rise, upstream suppliers may experience delays if product qualification is prolonged or if buyers redesign integrated modules to source fewer merchant parts.

What scope and segmentation does the market report cover?

The scope includes AR lenses and VR lenses shipped as optical components or assembled optical submodules, without counting the retail value of complete headsets or software subscriptions. It divides the market by AR Lens, VR Lens and by application across Games and Entertainment, Medical Care, Industrial, Others; additional axes are retained where specified. Five regional groupings support international comparisons. In assessing customer inquiry and scope clarification, the analysis uses 2026 as base year, 2027 as the estimated year and 2036 as the forecast year.

Research Sources & Evidence Base
View research sources used for this overview
  1. Lumus. Geometric waveguide roadmap and products, manufacturer background, 2025
  2. Lumus. Reflective-waveguide production volumes, 8 May 2025
  3. Lumus. Lumus and Quanta extended licensing, 1 September 2026; company-issued
  4. Lumus. Automated manufacturing partnership, 15 July 2025; company-issued
  5. SCHOTT. Serial geometric waveguide production, 29 September 2025
  6. Optinvent. Molded polymer optical waveguide architecture, company technical reference
  7. Dispelix. High-fidelity lithography development, 26 August 2025
  8. Dispelix. Polymer waveguide demonstration, 22 April 2025
  9. Dispelix. Photonic waveguide company development archive, official announcements 2024–2025
  10. Dispelix. Diffractive waveguide display engineering, company product reference
  11. Goertek. Full-color display glasses reference design, 9 January 2026
  12. Meta. Orion AR prototype optics and integration, optical-grade SiC architecture
  13. Meta. Silicon-carbide optical material program, manufacturer development reference
  14. Google. Android XR reference-device ecosystem, May 2025
  15. Google. Display-glasses demonstrations, 23 May 2025
  16. Google. Android XR device and software expansion, 8 December 2025
  17. Android Developers. Display-glasses developer support, 19 May 2026
  18. Apple. Spatial enterprise use cases, 9 June 2025
  19. Apple. Enterprise spatial computing deployments, 9 April 2024
  20. Apple. Immersive headset product update, 15 October 2025
  21. Ericsson. 5G infrastructure and XR connectivity context, June 2026
AR and VR Optical Components Market

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

Table of Contents
1 Research Methodology and Statistical Scope
1.1 Market Definition and Statistical Scope of AR and VR Optical Components
1.2 Key Market Segments
1.2.1 AR and VR Optical Components Segment by Type
1.2.2 AR and VR Optical Components Segment by Application
1.3 Methodology & Sources of Information
1.3.1 Research Methodology
1.3.2 Research Process
1.3.3 Market Breakdown and Data Triangulation
1.3.4 Base Year
1.3.5 Report Assumptions & Caveats
2 AR and VR Optical Components Market Overview
2.1 Global Market Overview
2.1.1 Global AR and VR Optical Components Market Size (M USD) Estimates and Forecasts (2026-2034)
2.1.2 Global AR and VR Optical Components Sales Estimates and Forecasts (2026-2034)
2.2 Market Segment Executive Summary
2.3 Global Market Size by Region
3 AR and VR Optical Components Market Competitive Landscape
3.1 Global AR and VR Optical Components Sales by Manufacturers (2019-2025)
3.2 Global AR and VR Optical Components Revenue Market Share by Manufacturers (2019-2025)
3.3 AR and VR Optical Components Market Share by Company Type (Tier 1, Tier 2, and Tier 3)
3.4 Global AR and VR Optical Components Average Price by Manufacturers (2019-2025)
3.5 Manufacturers AR and VR Optical Components Sales Sites, Area Served, Product Type
3.6 AR and VR Optical Components Market Competitive Situation and Trends
3.6.1 AR and VR Optical Components Market Concentration Rate
3.6.2 Global 5 and 10 Largest AR and VR Optical Components Players Market Share by Revenue
3.6.3 Mergers & Acquisitions, Expansion
4 AR and VR Optical Components Industry Chain Analysis
4.1 AR and VR Optical Components Industry Chain Analysis
4.2 Market Overview of Key Raw Materials
4.3 Midstream Market Analysis
4.4 Downstream Customer Analysis
5 The Development and Dynamics of AR and VR Optical Components Market
5.1 Key Development Trends
5.2 Driving Factors
5.3 Market Challenges
5.4 Market Restraints
5.5 Industry News
5.5.1 New Product Developments
5.5.2 Mergers & Acquisitions
5.5.3 Expansions
5.5.4 Collaboration/Supply Contracts
5.6 Industry Policies
6 AR and VR Optical Components Market Segmentation by Type
6.1 Evaluation Matrix of Segment Market Development Potential (Type)
6.2 Global AR and VR Optical Components Sales Market Share by Type (2019-2025)
6.3 Global AR and VR Optical Components Market Size Market Share by Type (2019-2025)
6.4 Global AR and VR Optical Components Price by Type (2019-2025)
7 AR and VR Optical Components Market Segmentation by Application
7.1 Evaluation Matrix of Segment Market Development Potential (Application)
7.2 Global AR and VR Optical Components Market Sales by Application (2019-2025)
7.3 Global AR and VR Optical Components Market Size (M USD) by Application (2019-2025)
7.4 Global AR and VR Optical Components Sales Growth Rate by Application (2019-2025)
8 AR and VR Optical Components Market Segmentation by Region
8.1 Global AR and VR Optical Components Sales by Region
8.1.1 Global AR and VR Optical Components Sales by Region
8.1.2 Global AR and VR Optical Components Sales Market Share by Region
8.2 North America
8.2.1 North America AR and VR Optical Components Sales by Country
8.2.2 U.S.
8.2.3 Canada
8.2.4 Mexico
8.3 Europe
8.3.1 Europe AR and VR Optical Components Sales by Country
8.3.2 Germany
8.3.3 France
8.3.4 U.K.
8.3.5 Italy
8.3.6 Russia
8.4 Asia Pacific
8.4.1 Asia Pacific AR and VR Optical Components Sales by Region
8.4.2 China
8.4.3 Japan
8.4.4 South Korea
8.4.5 India
8.4.6 Southeast Asia
8.5 South America
8.5.1 South America AR and VR Optical Components Sales by Country
8.5.2 Brazil
8.5.3 Argentina
8.5.4 Columbia
8.6 Middle East and Africa
8.6.1 Middle East and Africa AR and VR Optical Components Sales by Region
8.6.2 Saudi Arabia
8.6.3 UAE
8.6.4 Egypt
8.6.5 Nigeria
8.6.6 South Africa
9 Key Companies Profile
9.1 Radiant Vision Systems
9.1.1 Radiant Vision Systems AR and VR Optical Components Basic Information
9.1.2 Radiant Vision Systems AR and VR Optical Components Product Overview
9.1.3 Radiant Vision Systems AR and VR Optical Components Product Market Performance
9.1.4 Radiant Vision Systems Business Overview
9.1.5 Radiant Vision Systems AR and VR Optical Components SWOT Analysis
9.1.6 Radiant Vision Systems Recent Developments
9.2 Carl Zeiss AG
9.2.1 Carl Zeiss AG AR and VR Optical Components Basic Information
9.2.2 Carl Zeiss AG AR and VR Optical Components Product Overview
9.2.3 Carl Zeiss AG AR and VR Optical Components Product Market Performance
9.2.4 Carl Zeiss AG Business Overview
9.2.5 Carl Zeiss AG AR and VR Optical Components SWOT Analysis
9.2.6 Carl Zeiss AG Recent Developments
9.3 Avantier
9.3.1 Avantier AR and VR Optical Components Basic Information
9.3.2 Avantier AR and VR Optical Components Product Overview
9.3.3 Avantier AR and VR Optical Components Product Market Performance
9.3.4 Avantier AR and VR Optical Components SWOT Analysis
9.3.5 Avantier Business Overview
9.3.6 Avantier Recent Developments
9.4 Corning
9.4.1 Corning AR and VR Optical Components Basic Information
9.4.2 Corning AR and VR Optical Components Product Overview
9.4.3 Corning AR and VR Optical Components Product Market Performance
9.4.4 Corning Business Overview
9.4.5 Corning Recent Developments
9.5 Nalux
9.5.1 Nalux AR and VR Optical Components Basic Information
9.5.2 Nalux AR and VR Optical Components Product Overview
9.5.3 Nalux AR and VR Optical Components Product Market Performance
9.5.4 Nalux Business Overview
9.5.5 Nalux Recent Developments
9.6 Sunny Optical Technology
9.6.1 Sunny Optical Technology AR and VR Optical Components Basic Information
9.6.2 Sunny Optical Technology AR and VR Optical Components Product Overview
9.6.3 Sunny Optical Technology AR and VR Optical Components Product Market Performance
9.6.4 Sunny Optical Technology Business Overview
9.6.5 Sunny Optical Technology Recent Developments
9.7 Fujian Fran Optics
9.7.1 Fujian Fran Optics AR and VR Optical Components Basic Information
9.7.2 Fujian Fran Optics AR and VR Optical Components Product Overview
9.7.3 Fujian Fran Optics AR and VR Optical Components Product Market Performance
9.7.4 Fujian Fran Optics Business Overview
9.7.5 Fujian Fran Optics Recent Developments
9.8 Ningbo Jinhui Optical Technology
9.8.1 Ningbo Jinhui Optical Technology AR and VR Optical Components Basic Information
9.8.2 Ningbo Jinhui Optical Technology AR and VR Optical Components Product Overview
9.8.3 Ningbo Jinhui Optical Technology AR and VR Optical Components Product Market Performance
9.8.4 Ningbo Jinhui Optical Technology Business Overview
9.8.5 Ningbo Jinhui Optical Technology Recent Developments
9.9 Yejia Optical Technology
9.9.1 Yejia Optical Technology AR and VR Optical Components Basic Information
9.9.2 Yejia Optical Technology AR and VR Optical Components Product Overview
9.9.3 Yejia Optical Technology AR and VR Optical Components Product Market Performance
9.9.4 Yejia Optical Technology Business Overview
9.9.5 Yejia Optical Technology Recent Developments
9.10 Dongguan Yutong Optical Technology
9.10.1 Dongguan Yutong Optical Technology AR and VR Optical Components Basic Information
9.10.2 Dongguan Yutong Optical Technology AR and VR Optical Components Product Overview
9.10.3 Dongguan Yutong Optical Technology AR and VR Optical Components Product Market Performance
9.10.4 Dongguan Yutong Optical Technology Business Overview
9.10.5 Dongguan Yutong Optical Technology Recent Developments
9.11 Goertek Optical Technology
9.11.1 Goertek Optical Technology AR and VR Optical Components Basic Information
9.11.2 Goertek Optical Technology AR and VR Optical Components Product Overview
9.11.3 Goertek Optical Technology AR and VR Optical Components Product Market Performance
9.11.4 Goertek Optical Technology Business Overview
9.11.5 Goertek Optical Technology Recent Developments
9.12 Suzhou Lylap Optical Technology
9.12.1 Suzhou Lylap Optical Technology AR and VR Optical Components Basic Information
9.12.2 Suzhou Lylap Optical Technology AR and VR Optical Components Product Overview
9.12.3 Suzhou Lylap Optical Technology AR and VR Optical Components Product Market Performance
9.12.4 Suzhou Lylap Optical Technology Business Overview
9.12.5 Suzhou Lylap Optical Technology Recent Developments
9.13 SYPO
9.13.1 SYPO AR and VR Optical Components Basic Information
9.13.2 SYPO AR and VR Optical Components Product Overview
9.13.3 SYPO AR and VR Optical Components Product Market Performance
9.13.4 SYPO Business Overview
9.13.5 SYPO Recent Developments
9.14 IDTE
9.14.1 IDTE AR and VR Optical Components Basic Information
9.14.2 IDTE AR and VR Optical Components Product Overview
9.14.3 IDTE AR and VR Optical Components Product Market Performance
9.14.4 IDTE Business Overview
9.14.5 IDTE Recent Developments
9.15 Zhongshan Zhongying Optical
9.15.1 Zhongshan Zhongying Optical AR and VR Optical Components Basic Information
9.15.2 Zhongshan Zhongying Optical AR and VR Optical Components Product Overview
9.15.3 Zhongshan Zhongying Optical AR and VR Optical Components Product Market Performance
9.15.4 Zhongshan Zhongying Optical Business Overview
9.15.5 Zhongshan Zhongying Optical Recent Developments
9.16 Dongguan Lianlong Photoelectric Technology
9.16.1 Dongguan Lianlong Photoelectric Technology AR and VR Optical Components Basic Information
9.16.2 Dongguan Lianlong Photoelectric Technology AR and VR Optical Components Product Overview
9.16.3 Dongguan Lianlong Photoelectric Technology AR and VR Optical Components Product Market Performance
9.16.4 Dongguan Lianlong Photoelectric Technology Business Overview
9.16.5 Dongguan Lianlong Photoelectric Technology Recent Developments
10 AR and VR Optical Components Market Forecast by Region
10.1 Global AR and VR Optical Components Market Size Forecast
10.2 Global AR and VR Optical Components Market Forecast by Region
10.2.1 North America Market Size Forecast by Country
10.2.2 Europe AR and VR Optical Components Market Size Forecast by Country
10.2.3 Asia Pacific AR and VR Optical Components Market Size Forecast by Region
10.2.4 South America AR and VR Optical Components Market Size Forecast by Country
10.2.5 Middle East and Africa Forecasted Consumption of AR and VR Optical Components by Country
11 Forecast Market by Type and by Application (2025-2030)
11.1 Global AR and VR Optical Components Market Forecast by Type (2025-2030)
11.1.1 Global Forecasted Sales of AR and VR Optical Components by Type (2025-2030)
11.1.2 Global AR and VR Optical Components Market Size Forecast by Type (2025-2030)
11.1.3 Global Forecasted Price of AR and VR Optical Components by Type (2025-2030)
11.2 Global AR and VR Optical Components Market Forecast by Application (2025-2030)
11.2.1 Global AR and VR Optical Components Sales (K Units) Forecast by Application
11.2.2 Global AR and VR Optical Components Market Size (M USD) Forecast by Application (2025-2030)
12 Conclusion and Key FindingsList of Tables
Table 1. Introduction of the Type
Table 2. Introduction of the Application
Table 3. Market Size (M USD) Segment Executive Summary
Table 4. AR and VR Optical Components Market Size Comparison by Region (M USD)
Table 5. Global AR and VR Optical Components Sales (K Units) by Manufacturers (2019-2025)
Table 6. Global AR and VR Optical Components Sales Market Share by Manufacturers (2019-2025)
Table 7. Global AR and VR Optical Components Revenue (M USD) by Manufacturers (2019-2025)
Table 8. Global AR and VR Optical Components Revenue Share by Manufacturers (2019-2025)
Table 9. Company Type (Tier 1, Tier 2, and Tier 3) & (based on the Revenue in AR and VR Optical Components as of 2022)
Table 10. Global Market AR and VR Optical Components Average Price (USD/Unit) of Key Manufacturers (2019-2025)
Table 11. Manufacturers AR and VR Optical Components Sales Sites and Area Served
Table 12. Manufacturers AR and VR Optical Components Product Type
Table 13. Global AR and VR Optical Components Manufacturers Market Concentration Ratio (CR5 and HHI)
Table 14. Mergers & Acquisitions, Expansion Plans
Table 15. Industry Chain Map of AR and VR Optical Components
Table 16. Market Overview of Key Raw Materials
Table 17. Midstream Market Analysis
Table 18. Downstream Customer Analysis
Table 19. Key Development Trends
Table 20. Driving Factors
Table 21. AR and VR Optical Components Market Challenges
Table 22. Global AR and VR Optical Components Sales by Type (K Units)
Table 23. Global AR and VR Optical Components Market Size by Type (M USD)
Table 24. Global AR and VR Optical Components Sales (K Units) by Type (2019-2025)
Table 25. Global AR and VR Optical Components Sales Market Share by Type (2019-2025)
Table 26. Global AR and VR Optical Components Market Size (M USD) by Type (2019-2025)
Table 27. Global AR and VR Optical Components Market Size Share by Type (2019-2025)
Table 28. Global AR and VR Optical Components Price (USD/Unit) by Type (2019-2025)
Table 29. Global AR and VR Optical Components Sales (K Units) by Application
Table 30. Global AR and VR Optical Components Market Size by Application
Table 31. Global AR and VR Optical Components Sales by Application (2019-2025) & (K Units)
Table 32. Global AR and VR Optical Components Sales Market Share by Application (2019-2025)
Table 33. Global AR and VR Optical Components Sales by Application (2019-2025) & (M USD)
Table 34. Global AR and VR Optical Components Market Share by Application (2019-2025)
Table 35. Global AR and VR Optical Components Sales Growth Rate by Application (2019-2025)
Table 36. Global AR and VR Optical Components Sales by Region (2019-2025) & (K Units)
Table 37. Global AR and VR Optical Components Sales Market Share by Region (2019-2025)
Table 38. North America AR and VR Optical Components Sales by Country (2019-2025) & (K Units)
Table 39. Europe AR and VR Optical Components Sales by Country (2019-2025) & (K Units)
Table 40. Asia Pacific AR and VR Optical Components Sales by Region (2019-2025) & (K Units)
Table 41. South America AR and VR Optical Components Sales by Country (2019-2025) & (K Units)
Table 42. Middle East and Africa AR and VR Optical Components Sales by Region (2019-2025) & (K Units)
Table 43. Radiant Vision Systems AR and VR Optical Components Basic Information
Table 44. Radiant Vision Systems AR and VR Optical Components Product Overview
Table 45. Radiant Vision Systems AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 46. Radiant Vision Systems Business Overview
Table 47. Radiant Vision Systems AR and VR Optical Components SWOT Analysis
Table 48. Radiant Vision Systems Recent Developments
Table 49. Carl Zeiss AG AR and VR Optical Components Basic Information
Table 50. Carl Zeiss AG AR and VR Optical Components Product Overview
Table 51. Carl Zeiss AG AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 52. Carl Zeiss AG Business Overview
Table 53. Carl Zeiss AG AR and VR Optical Components SWOT Analysis
Table 54. Carl Zeiss AG Recent Developments
Table 55. Avantier AR and VR Optical Components Basic Information
Table 56. Avantier AR and VR Optical Components Product Overview
Table 57. Avantier AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 58. Avantier AR and VR Optical Components SWOT Analysis
Table 59. Avantier Business Overview
Table 60. Avantier Recent Developments
Table 61. Corning AR and VR Optical Components Basic Information
Table 62. Corning AR and VR Optical Components Product Overview
Table 63. Corning AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 64. Corning Business Overview
Table 65. Corning Recent Developments
Table 66. Nalux AR and VR Optical Components Basic Information
Table 67. Nalux AR and VR Optical Components Product Overview
Table 68. Nalux AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 69. Nalux Business Overview
Table 70. Nalux Recent Developments
Table 71. Sunny Optical Technology AR and VR Optical Components Basic Information
Table 72. Sunny Optical Technology AR and VR Optical Components Product Overview
Table 73. Sunny Optical Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 74. Sunny Optical Technology Business Overview
Table 75. Sunny Optical Technology Recent Developments
Table 76. Fujian Fran Optics AR and VR Optical Components Basic Information
Table 77. Fujian Fran Optics AR and VR Optical Components Product Overview
Table 78. Fujian Fran Optics AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 79. Fujian Fran Optics Business Overview
Table 80. Fujian Fran Optics Recent Developments
Table 81. Ningbo Jinhui Optical Technology AR and VR Optical Components Basic Information
Table 82. Ningbo Jinhui Optical Technology AR and VR Optical Components Product Overview
Table 83. Ningbo Jinhui Optical Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 84. Ningbo Jinhui Optical Technology Business Overview
Table 85. Ningbo Jinhui Optical Technology Recent Developments
Table 86. Yejia Optical Technology AR and VR Optical Components Basic Information
Table 87. Yejia Optical Technology AR and VR Optical Components Product Overview
Table 88. Yejia Optical Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 89. Yejia Optical Technology Business Overview
Table 90. Yejia Optical Technology Recent Developments
Table 91. Dongguan Yutong Optical Technology AR and VR Optical Components Basic Information
Table 92. Dongguan Yutong Optical Technology AR and VR Optical Components Product Overview
Table 93. Dongguan Yutong Optical Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 94. Dongguan Yutong Optical Technology Business Overview
Table 95. Dongguan Yutong Optical Technology Recent Developments
Table 96. Goertek Optical Technology AR and VR Optical Components Basic Information
Table 97. Goertek Optical Technology AR and VR Optical Components Product Overview
Table 98. Goertek Optical Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 99. Goertek Optical Technology Business Overview
Table 100. Goertek Optical Technology Recent Developments
Table 101. Suzhou Lylap Optical Technology AR and VR Optical Components Basic Information
Table 102. Suzhou Lylap Optical Technology AR and VR Optical Components Product Overview
Table 103. Suzhou Lylap Optical Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 104. Suzhou Lylap Optical Technology Business Overview
Table 105. Suzhou Lylap Optical Technology Recent Developments
Table 106. SYPO AR and VR Optical Components Basic Information
Table 107. SYPO AR and VR Optical Components Product Overview
Table 108. SYPO AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 109. SYPO Business Overview
Table 110. SYPO Recent Developments
Table 111. IDTE AR and VR Optical Components Basic Information
Table 112. IDTE AR and VR Optical Components Product Overview
Table 113. IDTE AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 114. IDTE Business Overview
Table 115. IDTE Recent Developments
Table 116. Zhongshan Zhongying Optical AR and VR Optical Components Basic Information
Table 117. Zhongshan Zhongying Optical AR and VR Optical Components Product Overview
Table 118. Zhongshan Zhongying Optical AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 119. Zhongshan Zhongying Optical Business Overview
Table 120. Zhongshan Zhongying Optical Recent Developments
Table 121. Dongguan Lianlong Photoelectric Technology AR and VR Optical Components Basic Information
Table 122. Dongguan Lianlong Photoelectric Technology AR and VR Optical Components Product Overview
Table 123. Dongguan Lianlong Photoelectric Technology AR and VR Optical Components Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 124. Dongguan Lianlong Photoelectric Technology Business Overview
Table 125. Dongguan Lianlong Photoelectric Technology Recent Developments
Table 126. Global AR and VR Optical Components Sales Forecast by Region (2025-2030) & (K Units)
Table 127. Global AR and VR Optical Components Market Size Forecast by Region (2025-2030) & (M USD)
Table 128. North America AR and VR Optical Components Sales Forecast by Country (2025-2030) & (K Units)
Table 129. North America AR and VR Optical Components Market Size Forecast by Country (2025-2030) & (M USD)
Table 130. Europe AR and VR Optical Components Sales Forecast by Country (2025-2030) & (K Units)
Table 131. Europe AR and VR Optical Components Market Size Forecast by Country (2025-2030) & (M USD)
Table 132. Asia Pacific AR and VR Optical Components Sales Forecast by Region (2025-2030) & (K Units)
Table 133. Asia Pacific AR and VR Optical Components Market Size Forecast by Region (2025-2030) & (M USD)
Table 134. South America AR and VR Optical Components Sales Forecast by Country (2025-2030) & (K Units)
Table 135. South America AR and VR Optical Components Market Size Forecast by Country (2025-2030) & (M USD)
Table 136. Middle East and Africa AR and VR Optical Components Consumption Forecast by Country (2025-2030) & (Units)
Table 137. Middle East and Africa AR and VR Optical Components Market Size Forecast by Country (2025-2030) & (M USD)
Table 138. Global AR and VR Optical Components Sales Forecast by Type (2025-2030) & (K Units)
Table 139. Global AR and VR Optical Components Market Size Forecast by Type (2025-2030) & (M USD)
Table 140. Global AR and VR Optical Components Price Forecast by Type (2025-2030) & (USD/Unit)
Table 141. Global AR and VR Optical Components Sales (K Units) Forecast by Application (2025-2030)
Table 142. Global AR and VR Optical Components Market Size Forecast by Application (2025-2030) & (M USD)
List of Figures
Figure 1. Product Picture of AR and VR Optical Components
Figure 2. Data Triangulation
Figure 3. Key Caveats
Figure 4. Global AR and VR Optical Components Market Size (M USD), 2026-2034
Figure 5. Global AR and VR Optical Components Market Size (M USD) (2026-2034)
Figure 6. Global AR and VR Optical Components Sales (K Units) & (2026-2034)
Figure 7. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 8. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 9. Evaluation Matrix of Regional Market Development Potential
Figure 10. AR and VR Optical Components Market Size by Country (M USD)
Figure 11. AR and VR Optical Components Sales Share by Manufacturers in 2023
Figure 12. Global AR and VR Optical Components Revenue Share by Manufacturers in 2023
Figure 13. AR and VR Optical Components Market Share by Company Type (Tier 1, Tier 2 and Tier 3): 2023
Figure 14. Global Market AR and VR Optical Components Average Price (USD/Unit) of Key Manufacturers in 2023
Figure 15. The Global 5 and 10 Largest Players: Market Share by AR and VR Optical Components Revenue in 2023
Figure 16. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 17. Global AR and VR Optical Components Market Share by Type
Figure 18. Sales Market Share of AR and VR Optical Components by Type (2019-2025)
Figure 19. Sales Market Share of AR and VR Optical Components by Type in 2023
Figure 20. Market Size Share of AR and VR Optical Components by Type (2019-2025)
Figure 21. Market Size Market Share of AR and VR Optical Components by Type in 2023
Figure 22. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 23. Global AR and VR Optical Components Market Share by Application
Figure 24. Global AR and VR Optical Components Sales Market Share by Application (2019-2025)
Figure 25. Global AR and VR Optical Components Sales Market Share by Application in 2023
Figure 26. Global AR and VR Optical Components Market Share by Application (2019-2025)
Figure 27. Global AR and VR Optical Components Market Share by Application in 2023
Figure 28. Global AR and VR Optical Components Sales Growth Rate by Application (2019-2025)
Figure 29. Global AR and VR Optical Components Sales Market Share by Region (2019-2025)
Figure 30. North America AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 31. North America AR and VR Optical Components Sales Market Share by Country in 2023
Figure 32. U.S. AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 33. Canada AR and VR Optical Components Sales (K Units) and Growth Rate (2019-2025)
Figure 34. Mexico AR and VR Optical Components Sales (Units) and Growth Rate (2019-2025)
Figure 35. Europe AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 36. Europe AR and VR Optical Components Sales Market Share by Country in 2023
Figure 37. Germany AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 38. France AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 39. U.K. AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 40. Italy AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 41. Russia AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 42. Asia Pacific AR and VR Optical Components Sales and Growth Rate (K Units)
Figure 43. Asia Pacific AR and VR Optical Components Sales Market Share by Region in 2023
Figure 44. China AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 45. Japan AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 46. South Korea AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 47. India AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 48. Southeast Asia AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 49. South America AR and VR Optical Components Sales and Growth Rate (K Units)
Figure 50. South America AR and VR Optical Components Sales Market Share by Country in 2023
Figure 51. Brazil AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 52. Argentina AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 53. Columbia AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 54. Middle East and Africa AR and VR Optical Components Sales and Growth Rate (K Units)
Figure 55. Middle East and Africa AR and VR Optical Components Sales Market Share by Region in 2023
Figure 56. Saudi Arabia AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 57. UAE AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 58. Egypt AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 59. Nigeria AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 60. South Africa AR and VR Optical Components Sales and Growth Rate (2019-2025) & (K Units)
Figure 61. Global AR and VR Optical Components Sales Forecast by Volume (2026-2034) & (K Units)
Figure 62. Global AR and VR Optical Components Market Size Forecast by Value (2026-2034) & (M USD)
Figure 63. Global AR and VR Optical Components Sales Market Share Forecast by Type (2025-2030)
Figure 64. Global AR and VR Optical Components Market Share Forecast by Type (2025-2030)
Figure 65. Global AR and VR Optical Components Sales Forecast by Application (2025-2030)
Figure 66. Global AR and VR Optical Components Market Share Forecast by Application (2025-2030)