Key Statistics
Key Takeaways
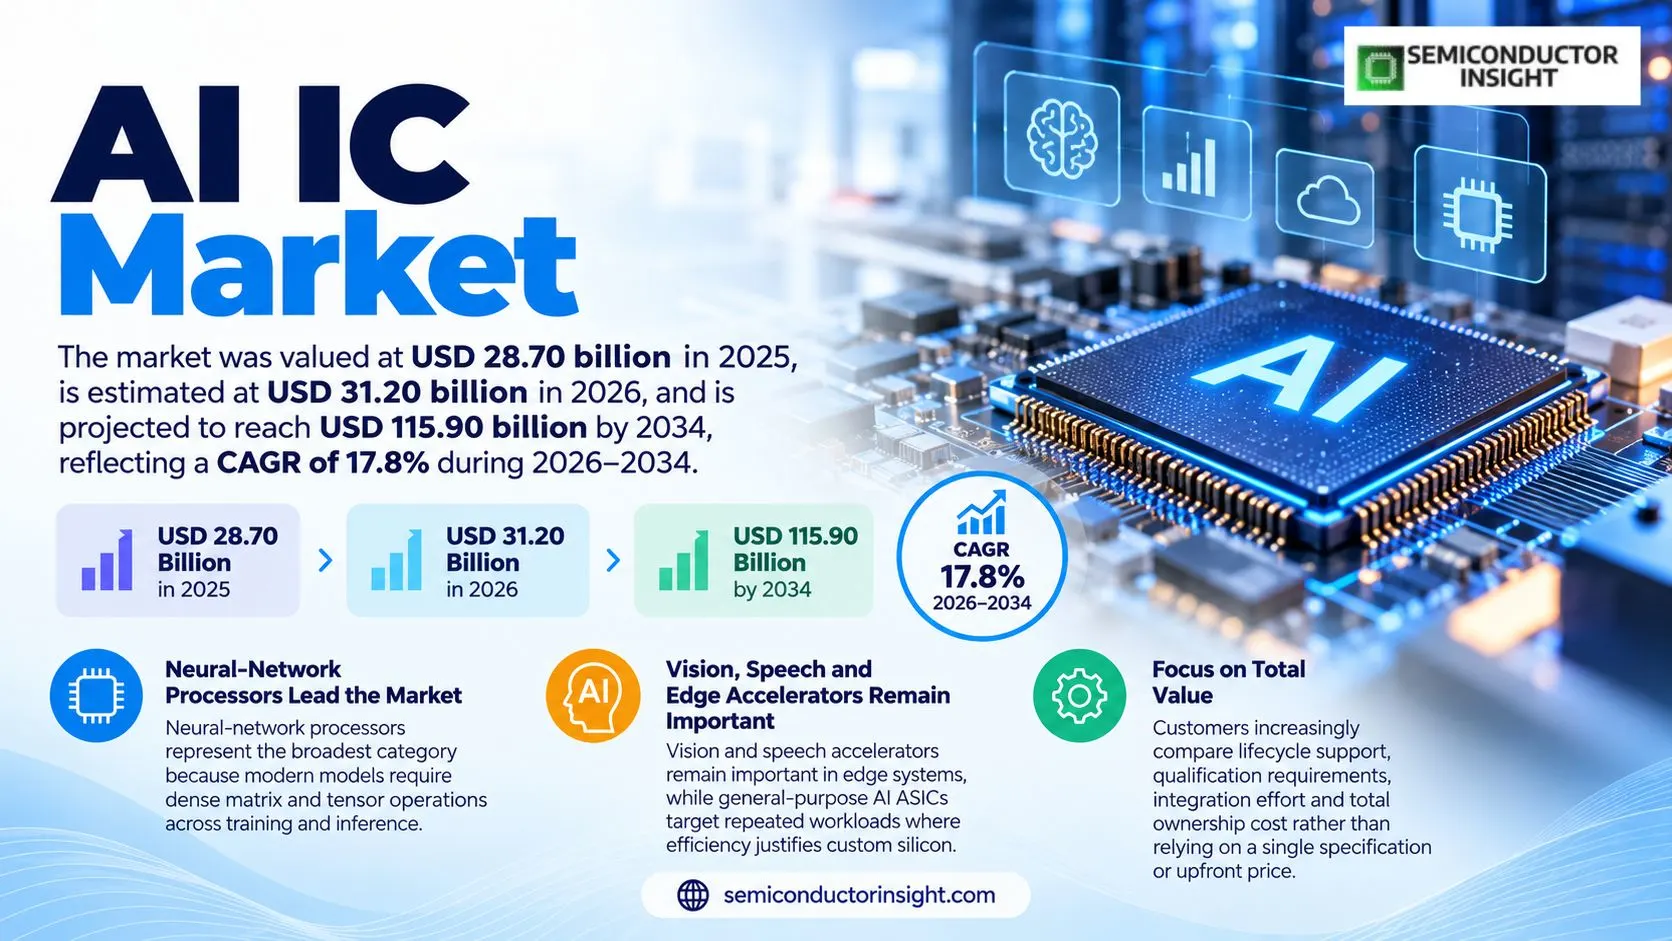
- The market is valued at USD 28.70 billion in 2025 and is projected to reach USD 115.90 billion by 2034, representing a 17.8% CAGR over 2026–2034.
- Neural-Network Processors is a major product segment, while adjacent variants are expanding as performance, integration and cost requirements evolve.
- Edge AI is a leading application area, supported by demand across Data-Center Acceleration, Autonomous Vehicles.
- North America is the largest market in 2025 based on current demand, manufacturing concentration and ecosystem maturity.
AI IC Market Overview
AI IC devices are specialized integrated circuits designed to accelerate neural-network training and inference through high-density matrix, tensor or vector compute, large memory bandwidth and optimized interconnect. The category spans data-center GPUs and TPUs, custom ASICs, edge accelerators and specialized vision or speech processors. Commercial adoption of AI IC products therefore depends on system-level productivity, integration requirements, reliability expectations and the economics of replacing established alternatives in real operating environments.
The market is expanding rapidly as generative AI, agentic systems, autonomous machines and on-device intelligence push compute demand across cloud and edge environments. Architectural competition now extends beyond raw FLOPS to memory capacity, interconnect, precision formats, compiler quality and energy efficiency because total system cost increasingly determines adoption. Suppliers that translate technical improvements into measurable gains in efficiency, uptime, cost, throughput or workflow simplicity are better positioned to win long-duration programs and repeat purchases.
Segment Analysis: By Type
Neural-network processors represent the broadest category because modern models require dense matrix and tensor operations across training and inference. Vision and speech accelerators remain important in edge systems, while general-purpose AI ASICs target repeated workloads where efficiency justifies custom silicon. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Type | Market relevance |
|---|---|
| Neural-Network Processors | Broadest deep-learning compute category. |
| Vision-Specific Accelerators | Computer vision and imaging workloads. |
| Speech-Optimized Engines | Voice and audio inference. |
| General-Purpose AI ASICs | Workload-specific efficiency and scale. |
Data-center acceleration captures the largest value because frontier training and large-scale inference require enormous compute and memory bandwidth. Edge AI is the broadest unit opportunity, while autonomous vehicles need deterministic low-latency processing and consumer electronics favor low-power on-device inference. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Application | Market relevance |
|---|---|
| Edge AI | High-unit-count low-power inference. |
| Data-Center Acceleration | Largest revenue and leading-edge silicon demand. |
| Autonomous Vehicles | Safety-critical real-time perception. |
| Consumer Electronics | Phones, PCs, wearables and smart devices. |
Segment Analysis: By Architecture
GPU-based accelerators dominate current revenue through software ecosystem and programmability, TPU-style engines provide highly optimized matrix compute, FPGAs serve reconfigurable deployments and dedicated ASICs maximize efficiency for stable high-volume workloads. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Architecture | Market relevance |
|---|---|
| GPU-Based Accelerators | Largest software ecosystem and training base. |
| TPU-Style Accelerators | Highly optimized matrix and tensor compute. |
| FPGA-Based AI Engines | Reconfigurable acceleration. |
| Dedicated ASICs | Highest efficiency for fixed workloads. |
Segment Analysis: By Deployment
Cloud-based AI services lead value because hyperscalers deploy accelerators at massive scale. On-premise and edge systems are growing where latency, privacy or data-locality requirements are stronger, while hybrid architectures split training and inference across cloud and local compute. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Deployment | Market relevance |
|---|---|
| On-Premise / Edge | Privacy and low-latency processing. |
| Cloud-Based AI Services | Largest hyperscale compute pools. |
| Hybrid Edge-Cloud | Training in cloud with local inference. |
Regional Analysis
North America leads in 2025 because NVIDIA, Google, AMD, Intel, Qualcomm and major hyperscalers are concentrated in the United States. Asia Pacific is the manufacturing center and is positioned for faster long-term growth through foundry, memory and consumer-electronics scale. Regional share also reflects supplier depth, engineering support, manufacturing concentration and the speed at which new AI IC designs can move from evaluation into repeat deployment.
| Region | 2025 Position | Growth Outlook | Demand Profile |
|---|---|---|---|
| North America | Largest | Very strong | Hyperscale cloud and accelerator design led |
| Asia Pacific | Manufacturing center | Very strong | Foundry, HBM and electronics led |
| Europe | Specialty and sovereign-AI market | Strong | Automotive, industrial and research led |
| South America | Emerging | Strong from smaller base | Cloud consumption led |
| Middle East & Africa | Developing | Very strong from smaller base | Sovereign AI and cloud infrastructure led |
Detailed Regional Blocks
Why is North America important to this market?
North America leads because U.S. companies control many of the most widely deployed AI accelerator architectures and cloud platforms. The region also hosts the largest concentration of model developers and AI infrastructure spending. In North America, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| United States | Largest global market | NVIDIA, Google, hyperscalers and AI startups drive demand. |
| Canada | AI research and cloud demand | Research clusters and enterprises support accelerator deployment. |
| Mexico | Server manufacturing adjacency | Assembly creates downstream consumption. |
- NVIDIA DGX B300 uses eight Blackwell Ultra GPUs and provides 2.1 TB of total GPU memory for enterprise AI workloads.
- Google’s eighth-generation TPU 8t architecture was introduced in April 2026 for reasoning-heavy and large-scale AI workloads.
- North American hyperscalers increasingly co-design chips, networks and software to optimize fleet-level cost per token.
Why is Asia Pacific important to this market?
Asia Pacific supplies the majority of advanced logic manufacturing, HBM memory and electronics assembly required for AI accelerators. China, South Korea, Taiwan and Japan also have growing domestic AI-chip ecosystems. In Asia Pacific, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Taiwan | Leading foundry and packaging hub | Advanced-node AI dies depend heavily on regional capacity. |
| South Korea | HBM and memory hub | High-bandwidth memory is critical to accelerator performance. |
| China | Large AI deployment market | Domestic accelerator and edge-chip programs expand rapidly. |
| Japan | Semiconductor and robotics ecosystem | Industrial and edge AI support specialized devices. |
- Advanced AI accelerators increasingly require HBM and large 2.5D packages, tying compute growth to Asian packaging capacity.
- Edge AI creates high-volume opportunities beyond data centers in cameras, vehicles and consumer devices.
- Regional supply constraints can affect global AI IC availability even when accelerator design occurs elsewhere.
Why is Europe important to this market?
Europe is smaller in hyperscale accelerator design but strong in automotive, industrial AI and sovereign-compute initiatives. Customers emphasize energy efficiency, privacy and deterministic operation in embedded systems. In Europe, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Germany | Automotive and industrial AI | Edge accelerators support robotics and vehicles. |
| France | Sovereign compute and research | National AI infrastructure expands accelerator demand. |
| United Kingdom | AI design ecosystem | Startups and Arm-based platforms support innovation. |
- European AI systems often prioritize efficient edge inference alongside centralized cloud training.
- Automotive platforms require long qualification cycles and functional-safety support.
- Sovereign AI investments create new regional infrastructure demand.
Why is South America important to this market?
South America is mainly a downstream market where Brazil and Chile host growing cloud and data-center infrastructure. Most AI IC value is imported inside servers, PCs and edge devices. In South America, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Brazil | Largest regional AI market | Cloud and enterprise AI drive accelerator consumption. |
| Chile | Data-center market | New facilities increase server demand. |
| Argentina | Research niche | Universities and software firms create smaller demand. |
- Cloud access allows regional companies to use proprietary accelerators without owning hardware.
- Enterprise inference is expanding faster than local chip design.
- Edge AI in cameras and industrial systems offers a lower-capital entry point.
Why is Middle East & Africa important to this market?
Middle East and Africa demand is rising through sovereign AI programs, hyperscale cloud expansion and smart-city investment in Gulf countries. Most chips are imported inside complete server systems. In Middle East & Africa, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| United Arab Emirates | Sovereign AI investment | Large data-center projects drive accelerator demand. |
| Saudi Arabia | AI infrastructure growth | National programs expand compute capacity. |
| Israel | Semiconductor design hub | AI and networking startups support custom silicon expertise. |
- Rack-scale AI systems require very high power and cooling density, making infrastructure part of chip adoption economics.
- Regional buyers increasingly procure complete AI factories rather than standalone accelerator cards.
- Israel contributes design expertise despite limited leading-edge manufacturing.
Competitive Landscape
NVIDIA, AMD, Intel, Google, Qualcomm, Samsung, Cerebras, Graphcore and custom-silicon partners compete across cloud and edge AI. Competitive advantage depends on compute density, memory bandwidth, interconnect, compiler support, power efficiency and the installed software ecosystem.
| Company | Position | Relevant capability |
|---|---|---|
| NVIDIA | Key participant | Blackwell Ultra platforms dominate high-end merchant AI acceleration and rack-scale systems. |
| AMD | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Intel | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Qualcomm | Key participant | Major edge AI supplier across smartphones, PCs and embedded platforms. |
| Key participant | Eighth-generation TPU 8t and TPU 8i expand proprietary hyperscale AI acceleration. | |
| Samsung Electronics | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Cerebras | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Graphcore | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| MediaTek | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Arm | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Amazon Web Services | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
Production Capacity Analysis
AI IC capacity is constrained by leading-edge foundry wafers, HBM supply, advanced substrates, interposers and packaging such as CoWoS-class 2.5D integration. Even when logic dies are available, memory or packaging bottlenecks can limit complete accelerator output. Scaling output without degrading consistency requires stable upstream materials, disciplined process control and final testing that catches performance drift before products reach high-value customer systems.
Software and system validation are also part of effective capacity. New accelerators require compilers, kernels, networking and framework support before customers can use them efficiently, so production scale alone does not guarantee commercial deployment. Second-source planning and regional technical support therefore become increasingly important as deployments expand and buyers seek supply continuity without repeating lengthy qualification work.
Market Dynamics
The market is shifting from training-dominated demand toward a much larger inference economy. Reasoning models perform substantial compute after deployment, increasing accelerator utilization and changing the optimal balance between memory, interconnect and low-precision arithmetic. This is changing competitive behavior because vendors increasingly sell system-level value, workflow integration and lifecycle economics rather than an isolated component specification.
At the same time, AI compute is spreading to edge devices. Local inference reduces latency, cloud cost and privacy exposure, creating a second growth path for lower-power AI ICs that differs materially from data-center GPU economics. Buyers consequently evaluate total ownership cost, qualification effort and roadmap stability across the life of a program instead of focusing only on initial purchase price.
Market Drivers
| Factor | Analyst Interpretation |
|---|---|
| Generative and agentic AI | Reasoning and multimodal models sharply increase training and inference demand. |
| Hyperscale investment | Cloud providers are building dedicated AI factories at large scale. |
| Edge inference | Phones, PCs, cameras and robots increasingly run AI locally. |
| Custom silicon | Large operators use ASICs to improve power efficiency and workload economics. |
Market Restraints
| Factor | Analyst Interpretation |
|---|---|
| Advanced packaging constraints | HBM and 2.5D capacity can bottleneck accelerator shipments. |
| Extreme power demand | AI racks require substantial power delivery and cooling infrastructure. |
| Software ecosystem lock-in | Developer tools and frameworks can slow migration between architectures. |
| Very high design cost | Leading-edge AI chips require massive engineering and tapeout investment. |
Market Opportunities
| Factor | Analyst Interpretation |
|---|---|
| Reasoning inference | Longer inference workloads create sustained accelerator demand. |
| AI PCs and phones | On-device NPUs expand semiconductor content per endpoint. |
| Custom cloud ASICs | Hyperscalers can optimize cost around recurring internal workloads. |
| Chiplet architectures | Modular compute and I/O dies can improve scalability and product reuse. |
Supply Chain Analysis
The value chain starts with architecture and RTL design, then moves through advanced foundry fabrication, HBM, substrates, 2.5D packaging, server integration and software deployment. Hardware and software are tightly coupled throughout the stack. Traceability and coordination between component suppliers, integrators and end users are important because failures found late in the chain can be far more expensive than the underlying part itself.
| Supply Chain Stage | Role in the Market |
|---|---|
| Architecture and silicon design | GPU, TPU, NPU and ASIC designs optimize target AI workloads. |
| Advanced wafer fabrication | Leading-edge foundries manufacture dense compute dies. |
| HBM and advanced packaging | Memory stacks and interposers provide bandwidth and system integration. |
| Systems and software | Accelerators are deployed in servers, edge devices and cloud platforms with optimized compilers and runtimes. |
Recent Developments
| Date | Development | Source |
|---|---|---|
| April 2026 | Google published a technical deep dive on eighth-generation TPU 8t and TPU 8i architectures for reasoning and large-scale AI workloads. | Google Cloud |
| 2026 | NVIDIA DGX B300 is available with eight Blackwell Ultra GPUs, 2.1 TB GPU memory and 144 PFLOPS of FP4 Tensor Core performance. | NVIDIA |
| July 2026 | Wistron opened a 324,000-square-foot U.S. plant producing NVIDIA Grace Blackwell Ultra systems as part of a USD 700 million manufacturing investment. | NVIDIA |
Report Scope & Segmentation
| Scope Item | Coverage |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 28.70 billion |
| 2026 Estimated Size | USD 31.20 billion |
| 2034 Forecast Size | USD 115.90 billion |
| CAGR (2026–2034) | 17.8% |
| Largest Market in 2025 | North America |
| Category | Integrated Circuits / Artificial Intelligence / AI Accelerators |
| By Type | Neural-Network Processors, Vision-Specific Accelerators, Speech-Optimized Engines, General-Purpose AI ASICs |
| By Application | Edge AI, Data-Center Acceleration, Autonomous Vehicles, Consumer Electronics |
| By Architecture | GPU-Based Accelerators, TPU-Style Accelerators, FPGA-Based AI Engines, Dedicated ASICs |
| By Deployment | On-Premise / Edge, Cloud-Based AI Services, Hybrid Edge-Cloud |
Frequently Asked Questions
What is the 2025 market size of the AI IC market?
The market is valued at USD 28.70 billion in 2025.
What is the projected 2034 market size of the AI IC market?
The market is projected to reach USD 115.90 billion by 2034.
What is the CAGR of the AI IC market from 2026 to 2034?
The market is expected to expand at a CAGR of 17.8% during 2026–2034.
Which region leads the AI IC market?
North America is the largest market in 2025 based on the current demand, manufacturing and deployment structure.
Which type segment is important in the AI IC market?
Neural-Network Processors is a major segment, while adjacent product variants are gaining share as performance and integration requirements evolve.
What is the main application for AI IC products?
Edge AI is a leading application, with additional growth coming from Data-Center Acceleration, Autonomous Vehicles.
What drives growth in the AI IC market?
Reasoning and multimodal models sharply increase training and inference demand.
What is a key restraint for the AI IC market?
HBM and 2.5D capacity can bottleneck accelerator shipments.
Which companies participate in the AI IC market?
Key participants include NVIDIA, AMD, Intel, Qualcomm, Google, alongside other specialized suppliers and system companies.
What technology trend is shaping the AI IC market?
Longer inference workloads create sustained accelerator demand.
Research Sources & Evidence Base
View research sources used for this overview.
- Google Cloud — TPU 8t and TPU 8i Technical Deep Dive: 2026 eighth-generation TPU architecture for reasoning and large-scale AI. Source
- NVIDIA — DGX B300: Current Blackwell Ultra enterprise AI system specifications and use cases. Source
- NVIDIA — Blackwell Ultra Architecture: Current accelerator architecture, memory and interconnect details. Source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF